Sandisk Stock: $8.1 Billion Profit in One Quarter — and Still Cut in Half
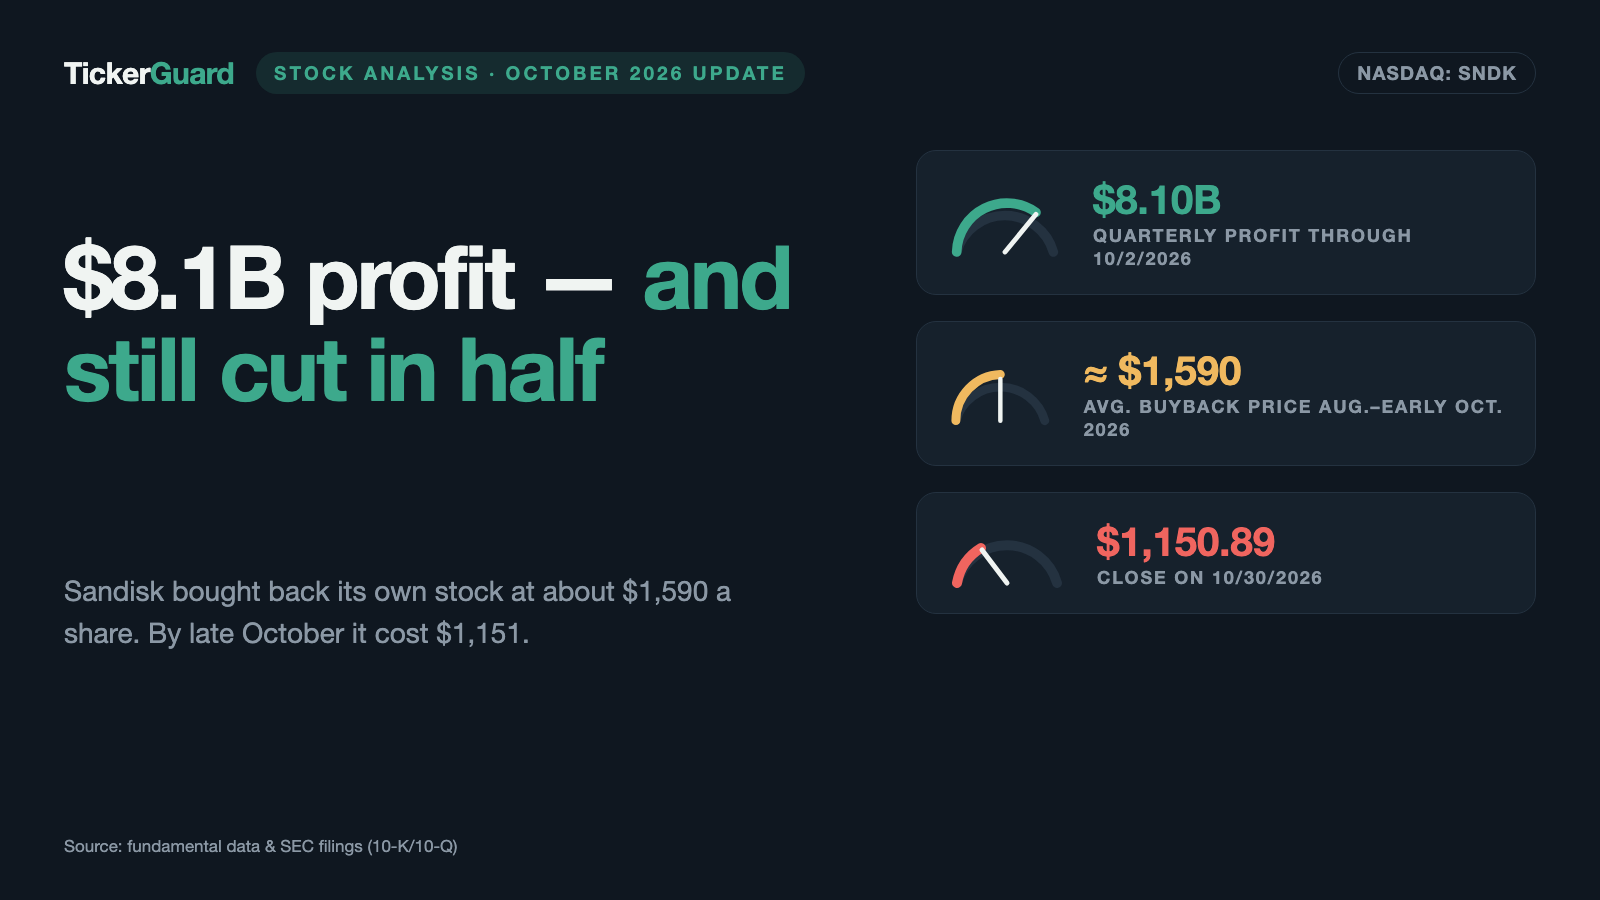
In the first quarter of fiscal 2027 (through October 2, 2026) Sandisk earned $8.10 billion on $11.03 billion of revenue — and the day after those numbers the stock fell 13.5 percent to $1,150.89, half its June 2026 level. Only weeks earlier the company itself had been buying back its shares at about $1,590 apiece. Not investment advice — just a cross-examination of the inner know-it-all who claims all of this was foreseeable.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 30, 2026
- Closing price
- 1,150.90 $ -13.50%
- Market Capitalisation
- 197.4 $B
- P/E
- 39.4
- Growth Score
- 9/10
- AAQS
- 8/10
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 194.40 $ to 2,335.00 $ · Last price: 1,150.90 $ (As of: October 30, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
New on October 31, 2026: Sandisk earned $8.10 billion in the first quarter of fiscal 2027 — and the day after the report the stock fell 13.5 percent, below the price at which the company itself had bought back its own shares only weeks earlier. What lies behind it is in the new chapter on the first quarter.
Updated on October 31, 2026: extended to cover the first quarter of fiscal 2027 (July 4 through October 2, 2026; quarterly report 10-Q of October 30, 2026, earnings release and earnings call of October 29, 2026) and the annual report (10-K) for fiscal 2026 of August 17, 2026. There is a new chapter on the first quarter; the numbers, balance sheet, valuation, opportunities and risks reflect the new state. All per-share figures are before the 8-for-1 stock split announced on October 29. Earlier updates: August 12, 2026 (fiscal Q4 2026, see the look-back chapter) and August 2, 2026 (earnings-calls chapter).
In every investor lives a lodger who never pays rent and is always right: the inner know-it-all. He reliably speaks up when a chart like that of Sandisk (Nasdaq: SNDK) scrolls across the screen — from the lowest close of the twelve months before the high, $40.69 on August 7, 2025, to $2,335.00 on June 25, 2026, a 57-fold move in just under eleven months — and says his favorite sentence: “You could have seen that coming.” He says it about the second act, too: on October 30, 2026, one day after a record quarter, the same stock closed at $1,150.89 — about half its June level, and well below the price at which Sandisk itself had bought back its own shares from August to early October. Psychologists call this lodger hindsight bias: once the outcome is fixed, our memory rebuilds the past so that it marched straight toward it — every low retroactively becomes a signposted entry point. The treacherous part is the conclusion he draws: whoever believes yesterday was recognizable automatically trusts himself to recognize tomorrow, too — and buys. So let’s make a deal: we cross-examine the know-it-all. As evidence we take the documents Sandisk must file truthfully, under penalty of law, with the U.S. securities regulator, the SEC — the annual reports (10-K, the yearly mandatory filing) and the quarterly reports (10-Q). The record speaks clearly: in the spring of 2025, nothing in the documents suggested the stock was seen as a bargain. The market pushed it below its book value. Its own balance sheet had to write off $1.8 billion of goodwill as a result. And the former parent Western Digital began to dispose of its retained stake. And because the know-it-all has since been handed a second act, we cross-examine him twice: since June 25, 2026 the stock has halved — while revenue and profit kept going through the roof. You could have seen that coming too, right? In the end, you decide for yourself what it means for you.
What Sandisk actually does
Sandisk makes NAND flash — the long-term memory of the digital world. NAND cells are the storage cells that remember even without power: they sit in the SSDs of data centers and laptops, in smartphones, memory cards and USB sticks. The company from Milpitas, California (about 11,100 employees in 33 countries, 74 percent of them in Asia-Pacific, as of July 2026) sorts its business into three end markets: “Datacenter” (data centers, formerly called “Cloud”), “Edge” (devices such as PCs and smartphones, formerly “Client”) and “Consumer” (cards, sticks, external drives — the SanDisk products on the electronics-store shelf). The memory wafers are not made in factories of its own but in Flash Ventures — a web of three joint companies with the Japanese partner Kioxia, in each of which Sandisk holds 49.9 percent and whose agreements, since January 2026, run through the end of 2034. Remember this construct, we will come back to it — it is blessing and corset at once.
Two peculiarities you need to know before the numbers make sense. First, the origin: until February 21, 2025, Sandisk was a wholly owned subsidiary of Western Digital; then came the spin-off — WDC distributed 80.1 percent of the Sandisk shares to its own shareholders (one third of a Sandisk share per WDC share) and initially kept 19.9 percent, which, according to the quarterly report as of October 2, 2026, it has since disposed of entirely. As a parting gesture Sandisk took on a $2 billion loan and wired $1.5 billion of it to its parent as a settlement payment — the child moved out with debts whose proceeds largely stayed at the parents’ house. Second, the calendar: Sandisk reports in an offset fiscal year ending on the Friday closest to June 30. “Fiscal year 2026” means June 28, 2025 through July 3, 2026. The first quarter of fiscal 2027, whose numbers Sandisk reported on October 29, 2026, ran from July 4 through October 2, 2026 — on the calendar, essentially the third quarter of 2026. And with that, the central tension that runs through this analysis as its connecting thread: between March 2025 and October 2026 the same market priced the same company first below book value, then at 25 times book value — and then, in the middle of record numbers, cut it back to half. What changed about the business in that time is above all one single variable: the price per gigabyte.
Company history for investors
-
2023
Overcapacity crisis
In fiscal 2023 the later Sandisk division lost $2.1 billion at a 7.1 percent gross margin — the low point before the boom.
-
2025
Spin-off and goodwill write-off
Sandisk has traded on the Nasdaq since February 24, 2025. Its market value fell below book value, and the company wrote off $1.8 billion of goodwill.
-
2026
Loan repaid, first multi-year contracts
By March 4, 2026 the spin-off loan was repaid. Multi-year contracts with major customers secured $59.8 billion of remaining performance obligations by July 3, 2026.
-
2026
Record year and $14 billion for buybacks
Fiscal 2026 brought $11.43 billion of profit. On August 5, 2026 the board authorized another $14 billion for share repurchases.
-
2026
8-for-1 stock split
With the results of October 29, 2026 Sandisk announced a split: seven new shares for every share held, with split-adjusted trading from November 20, 2026.
Where the stock shows up in our scanner
Every day we run about 3,500 stocks through our scanners. Sandisk showed up in the value scanner “Joel Greenblatt: Magic Formula” — right at the top, and the neighborhood was a family photo of the memory industry: as of the July 8, 2026 data cut-off Sandisk stood in second place, framed by Micron above and its own former parent Western Digital below; at the live check on July 14, 2026 it was third, behind both. As of the July 8 cut-off Sandisk additionally led our EBIT-margin ranking — the operating margin of the then last four quarters was around 70 percent. Greenblatt’s formula, in plain words: buy good companies at a fair price, measured by exactly two numbers — return on capital (how much operating profit per dollar of working capital employed?) and earnings yield (how much operating profit per dollar of enterprise value?). A freshly exploded memory maker naturally shines in both disciplines.

We dissected it at length in the Micron analysis and repeat only the core here: with cyclicals, the Magic Formula preferentially fires at the earnings peak, because it treats the most recently reported profits as a permanent state. A memory maker at record prices always looks “cheap” in this arithmetic — until the cycle turns. As of the July 8, 2026 cut-off the remaining metrics were strong in their own right: a Piotroski F-Score of 7 of 9 (a nine-point test of balance-sheet quality — 7 is good), an Altman Z-Score around 13 (a classic early warning of insolvency; danger begins below 1.1 — miles away here), fundamental rating A, relative strength 99: hardly any stock in the market had run better over the preceding twelve months. But that is exactly the point: this is not an overlooked value gem the scanner dug up. This was one of the hottest stocks in the market, waved through by a value filter because of its record profits — in the same week as Micron. The inner know-it-all and the formula make related mistakes: he considers the past to have been predictable, it considers the present to be permanent.
The numbers over the years — honestly appraised
First, what genuinely impresses — and it is one of the steepest staircases we have ever seen in quarterly reports. Fiscal year 2026, quarter by quarter: $2.31 billion of revenue in the first quarter (through October 3, 2025), $3.03 billion in the second (through January 2, 2026), $5.95 billion in the third (through April 3, 2026) and $8.97 billion in the fourth (through July 3, 2026). For the full fiscal year 2026 the annual report therefore shows $20.25 billion of revenue (up 175 percent), $11.43 billion of net income ($73.76 per diluted share), $11.67 billion of operating cash flow and $11.49 billion of free cash flow. And the first quarter of fiscal 2027 (through October 2, 2026) added another step: $11.03 billion of revenue, up 23 percent sequentially and 378 percent year over year, and $8.10 billion of net income — in a single quarter almost three quarters of the entire prior-year profit. Across these five quarters the gross margin climbed from 29.8 via 50.9, 78.4 and 84.6 to 85.0 percent — levels this company had never before seen even from afar. The balance sheet as of October 2, 2026 is unrecognizable within fifteen months: the $2 billion farewell loan is fully repaid (on March 4, 2026, out of cash), zero financial debt stands against $5.14 billion of cash, and equity grew from $9.2 billion (June 27, 2025) to $18.13 billion. The driver is the AI wave: data centers are buying flash SSDs as if there were no tomorrow — datacenter revenue rose from $269 million in the quarter through October 3, 2025 to $4.80 billion in the quarter through October 2, 2026, making up 43.5 percent of revenue.
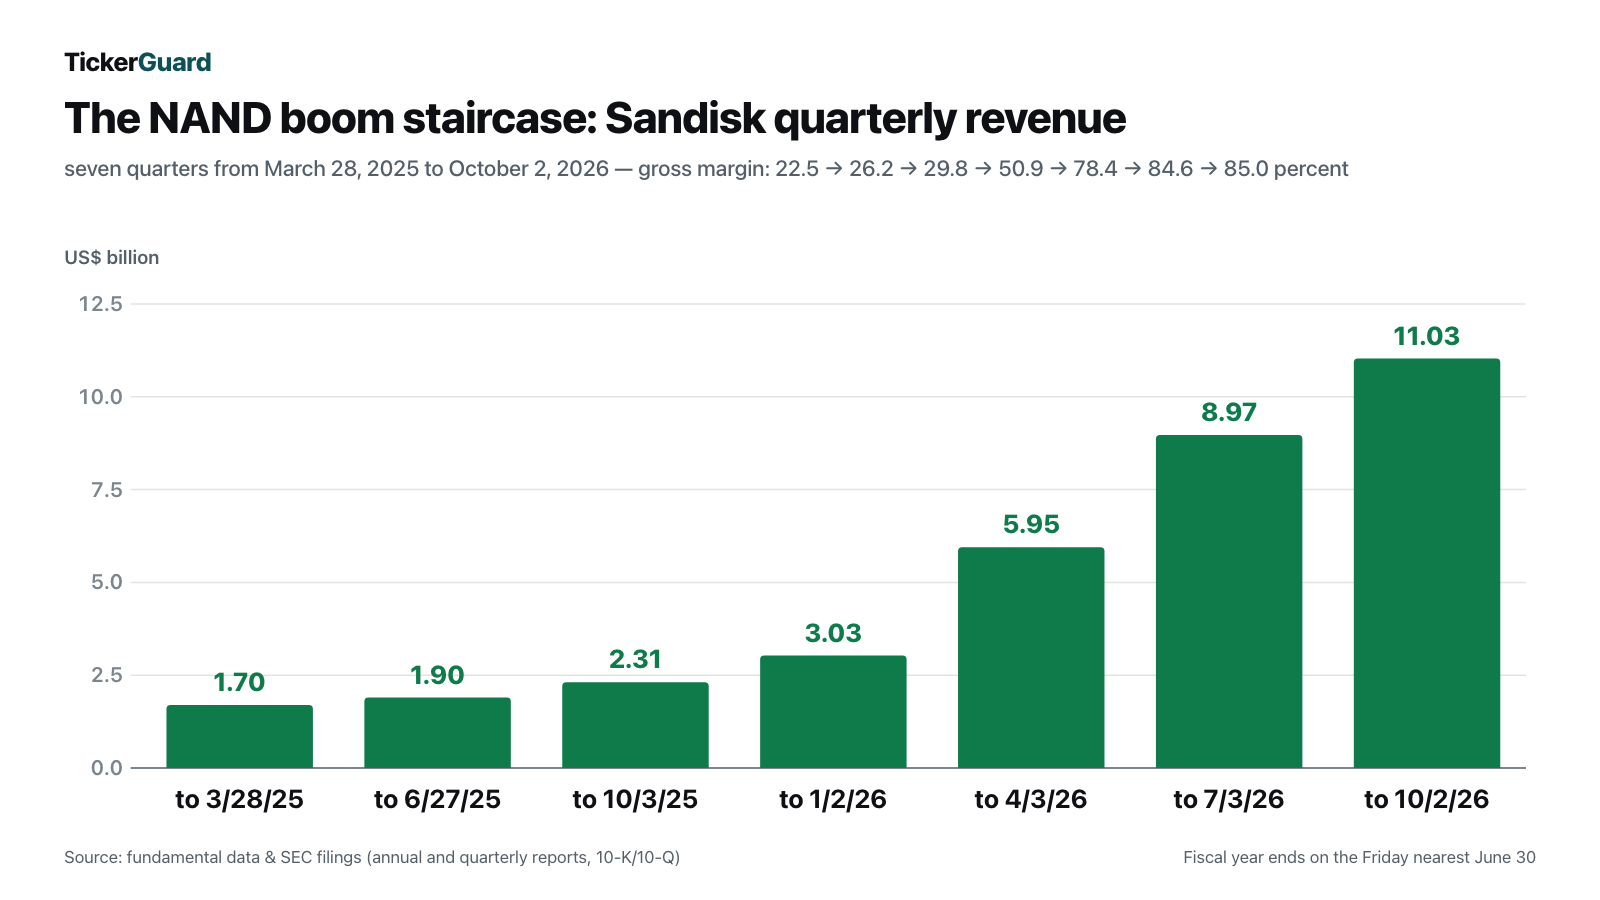
And now the same company, only a few years earlier — because a company’s history does not begin at the low. Fiscal year 2023 (through June 30, 2023): $6.1 billion of revenue, a gross margin of 7.1 percent, a net loss of $2.1 billion — the memory market was stuck in the overcapacity crisis, and the then WDC division additionally wrote down inventories and paid underutilization charges for idle fabs. Fiscal year 2024: minus $672 million. Fiscal year 2025: revenue of $7.4 billion (up 10 percent — 6 points of it volume, 4 points price), a net loss of $1.6 billion, shaped by the goodwill write-off we will get to in a moment; even adjusted, only a wafer-thin operating profit remained. Three fiscal years, three losses, minus $4.5 billion combined — and then, in the fourth year, a profit of $11.43 billion. Put differently: in twelve months Sandisk earned two and a half times what the company had lost in the three preceding years combined. Exactly this sequence is what the next picture shows, and it is the reason we read the filings especially carefully:

What the filings say — the uncomfortable truths
Uncomfortable truth no. 1: revenue up 251 percent — on practically unchanged volume
The quarterly report as of April 3, 2026 dissected the revenue jump itself, in the very first sentence of its revenue analysis — and you should have read this dissection before the inner know-it-all shouts “obvious case”:
“Net revenue increased 251% in the three months ended April 3, 2026 from the comparable period in the prior year, primarily due to a 248% increase in average selling prices (“ASP”) per gigabyte. The exabytes sold remained flat from the comparable period in the prior year.”
— Sandisk Corporation, SEC quarterly report 10-Q as of April 3, 2026, Item 2 MD&A “Net Revenue”

The picture has moved since then — but less than it seems at first glance. Against the respective prior quarter, growth increasingly comes from volume: in the closing quarter of fiscal 2026 roughly one third of the gain came from higher volumes, per the earnings release of August 5, 2026; in the first quarter of fiscal 2027, per CFO Luis Visoso on the earnings call of October 29, 2026, it was already “approximately 60%” — about 60 percent volume, 40 percent price. Against the prior-year quarter, by contrast, the new quarterly report still shows the old pattern:
“Net revenue increased 378%, or $8.7 billion, in the three months ended October 2, 2026 compared to the three months ended October 3, 2025, primarily due to a 1,685% increase in Datacenter revenue and a 320% increase in Edge revenue, which was partially offset by a 39% decrease in Consumer revenue. Total products sold increased by almost 10% on an exabyte basis.”
— Sandisk Corporation, SEC quarterly report 10-Q as of October 2, 2026, Item 2 MD&A “Net Revenue”
Revenue up 378 percent on just under 10 percent more volume: the rest is price. The end-market breakdown makes it plain. In the data-center business, volume (up almost 330 percent) and price per gigabyte (up almost 320 percent) grew together. In the Edge business (PCs, smartphones — at $5.83 billion the quarter’s largest revenue block) the price per gigabyte rose more than 450 percent while the volume sold fell 20 percent. And in the consumer business volume collapsed by more than 70 percent; revenue fell to $397 million in the quarter through October 2, 2026, 29 percent below the prior quarter. CEO David Goeckeler conceded on the call that, for PC unit volumes year over year, the company was “in the teeth of that” — in the sharpest phase of the decline — but sees improvement from here; for 2027 management expects growing volumes in every segment of the NAND market — PCs, smartphones, data centers. A boom that sits to a large extent in the price hangs on the one variable a maker of commodity goods controls least — NAND from Sandisk does the same thing as NAND from Samsung, SK hynix, Kioxia or Micron. What it feels like when it tips over is described with remarkable candor in the risk section of the company’s own annual report, unchanged in the report for fiscal 2026: the memory market has experienced “periods of excess capacity leading to liquidation of excess inventories, inventory write-downs, underutilization charges, significant reductions in average selling prices” — and can experience them again (10-K fiscal year 2026, Item 1A). This is not theory: as recently as fiscal year 2025 Sandisk paid $75 million in underutilization charges for idle capacity and wrote off $24 million of inventories — in the crisis year 2023, still under WDC’s roof, it was $296 million plus $108 million. A price that multiplies within twelve months is not a new law of nature. It is the other half of the same roller coaster.
Uncomfortable truth no. 2: the backlog — at Sandisk, too, “this time it’s different” now comes in contract form
Now the counter-thesis, and it is strong. Since the third quarter of fiscal 2026 Sandisk has been signing multi-year supply agreements with major customers that the company calls “New Business Models” — with fixed and variable price components, prepayments and financial collateral. The punch sits in a footnote of the revenue note, and it has grown quarter after quarter since April: $41.6 billion of remaining performance obligations as of April 3, 2026, $59.8 billion as of July 3, 2026 (known in August only from the earnings call, audited and documented since the annual report of August 17, 2026) — and then this:
“As of October 2, 2026, the transaction price allocated to remaining performance obligations was $88.9 billion, of which $87.4 billion has not yet been billed and $1.5 billion has been recorded as contract liabilities. Approximately 20% of the remaining performance obligations from these contracts with customers are expected to be recognized as revenue over the next twelve months. The remaining performance obligations are entirely related to NBMs.”
— Sandisk Corporation, SEC quarterly report 10-Q as of October 2, 2026, Note 4 “Revenue”

What stands behind it can by now be checked in the filings themselves rather than only in call statements. Customers post collateral in two ways: as a security deposit with Sandisk, which sits on the balance sheet as a “refund liability” and is paid back at the end of the contract ($1.60 billion as of October 2, 2026), and as collateral held at banks, which Sandisk may only draw on if a contract is breached and which therefore stays off the balance sheet — $5.0 billion as of July 3 and $12.8 billion as of October 2, 2026. Add $1.53 billion of prepayments. On the call of October 29, 2026 management gave the booking status: roughly half of the supply volume for fiscal 2027 and roughly two thirds of that for fiscal 2028 are contractually committed; 95 percent of the counterparties hold an investment-grade credit rating, and several customers are already coming back for a second round. CFO Visoso put it this way: “Our NBM pipeline exceeds our supply throughout the end of the decade.”
Be fair to both sides here as well. In favor: $88.9 billion is roughly three times the revenue of the last four quarters ($28.97 billion) — a backlog Sandisk did not report before 2026. Customers who make prepayments, post collateral and commit for years evidently fear the shortage more than the price; we know the pattern from Micron’s 10-Q with its take-or-pay contracts. And per the quarterly report, the contracts contain fixed price components — a genuine buffer against the first part of a price slide. Against it speak three things. First, the duration: only about 20 percent of the backlog is expected to become revenue within twelve months, the rest spreads across many years — a tailwind, but no guarantee for the margin of the moment. Second, the timing: these contracts were signed after prices per gigabyte had risen 248 percent within a year (10-Q as of April 3, 2026) — a price level that is hard to hold in a downturn. The collateral of a little over $14 billion combined covers about one sixth of the backlog; the rest depends on customers’ ability and willingness to pay. The annual report itself warns that a contract breach could lead to disputes, arbitration and Sandisk being unable to sell the volumes elsewhere at comparable prices — so the report itself names the risk that customers may not want to honor contracts from the high-price phase in a downturn. Third, the symmetry: a backlog also binds Sandisk itself — to delivery volumes for which the capacity has yet to be built, together with a partner who is about to become important. A mountain of signed contracts is better than none. But it is a promise about the future, made at the peak of a price boom.
Uncomfortable truth no. 3: the Kioxia corset — half the fixed costs are mandatory, even if Sandisk orders nothing
Sandisk owns no wafer fabs of its own. Practically the entire flash supply comes from the Flash Ventures joint companies with Kioxia in Japan — and the annual report describes very precisely what that means in a downturn. The following sentence stood in the annual report for fiscal 2025 and appears word for word in the one for fiscal 2026:
“The terms of our agreements with Kioxia with respect to Flash Ventures require that substantially all of our flash-based memory be obtained from Flash Ventures [...] For example, we are contractually obligated to pay for 50% of the fixed costs of Flash Ventures regardless of whether we order any flash-based memory, and our orders placed with Flash Ventures on a rolling basis are binding.”
— Sandisk Corporation, SEC annual report 10-K, fiscal year 2026, Item 1A “Risk Factors” (Flash Ventures); identical in the 10-K for fiscal year 2025

Let’s translate the construct into an everyday image: Sandisk has rented a commercial kitchen together with its competitor Kioxia — for decades, with termination clauses that feel more like a marriage; in January 2026 the agreements were extended through the end of 2034, and on top Sandisk pays Kioxia $1.2 billion directly through 2029 for manufacturing services and supply security. When the restaurant is running, the shared kitchen is a cost advantage. When the dining room stays empty, Sandisk still pays half the kitchen rent. That is the irony of this balance sheet: while Sandisk by now has its customers sign multi-year contracts with collateral, it has always carried a built-in take-or-pay toward its own supplier — in a downturn, it pays first. On top come obligations that do not sit on the balance sheet: Sandisk guarantees half of the equipment lease agreements of the Flash Ventures fabs — about $838 million off balance sheet as of October 2, 2026 — and the quarterly report puts the maximum loss scenario from the whole construct (loans, equity stake, guarantees, inventories and prepayments) at $2.94 billion. Contractual payment obligations toward Flash Ventures add up to $7.14 billion at the same date, of which $2.48 billion is due in the remaining nine months of fiscal 2027. And one more clause belongs here: per the risk chapter, the JV agreements could significantly impede a takeover of Sandisk — whoever speculates on a takeover premium is speculating against the fine print. None of this is a problem in the boom, on the contrary: the fabs run full, the shared costs lever the profit. But it means: Sandisk’s cost structure is built for cycle peaks — flexible upward, rigid downward.
Uncomfortable truth no. 4: the balance sheet remembers — a goodwill write-off at the start, growing clusters in the boom
Finally, the truth that convicts the inner know-it-all of outright false testimony. When Sandisk came to the exchange in February 2025, buyers did not find the price attractive — there simply were too few buyers. The share fell so low that the market value slipped below book value, and that forced the freshly spun-off company into a remarkable step in that very quarter:
“Subsequent to the completion of the separation, we identified potential impairment indicators related to the trading price of our common stock and a resulting market capitalization that was below its December 27, 2024 net book value. In accordance with Accounting Standards Codification No. 350, Intangibles - Goodwill and Other, we performed a quantitative test, which indicated that the carrying value of our reporting unit exceeded its estimated fair value resulting in the recognition of a $1.8 billion impairment charge as of, and for the nine months ended, March 28, 2025.”
— Sandisk Corporation, SEC annual report 10-K, fiscal year 2025, Item 1A “Risk Factors” (section “Future material impairments …”)

Goodwill, translated: the premium over substance value that a buyer once paid and that has sat in the balance sheet as a line item of hope ever since — when the hope shrinks, it must be written off. Hold the pictures side by side: in March 2025 the market said this company was worth less than its book value. At the end of June 2026 the same market paid roughly 25 times book value. On October 30, 2026, after the next record quarter, it was nine times. These three valuations are so far apart that at least one of them probably misjudged the cycle — and nothing guarantees the most recent one is right. The former parent belongs in the picture, too: as early as June 2025 — before the price explosion — Western Digital exchanged 14.6 percent of Sandisk for its own debt, as a first step in reducing its retained stake; on February 18, 2026 another 5.8 million shares followed, after which WDC still held about 1.7 million; WDC has not been a related party since July 3, 2026 (annual report 10-K for fiscal 2026). Per the quarterly report as of October 2, 2026, WDC has since disposed of all its Sandisk shares. According to the 10-K, Sandisk bore the costs of the two placements in June 2025 and February 2026.
And the balance sheet as of October 2, 2026 carries boom-typical clusters. Total assets have grown to $25.8 billion, and $5.0 billion of that is still goodwill — just under a fifth. Trade receivables jumped within a single quarter from $4.71 billion to $6.59 billion; here the counter-check is worth doing rather than ringing the alarm bell reflexively: per the quarterly report that equals 54 days outstanding, against 51 a year earlier — receivables are growing roughly at the pace of the business, and on the call the CFO cited a changed customer mix as the reason. Inventories need more explaining: $3.02 billion, which measured against cost of revenue means 166 days of coverage, after 115 days a year earlier — Sandisk is holding considerably more stock, per the report “to meet demand”, that is, to serve the contractually committed volumes. The position that was still puzzling in August, the refund liabilities ($1.60 billion as of October 2, 2026, after $126 million in June 2025), has been explained by the annual report for fiscal 2026:
“Refund liabilities relate to consideration received that is expected to be refunded to the customer, following their satisfaction of all performance conditions, and primarily include security deposits collected under NBMs that must be refunded at the end of the contract term.”
— Sandisk Corporation, SEC annual report 10-K, fiscal year 2026, Note 4 “Revenue”
That is a reassuring answer: a deposit is not a rebate. What remains is concentration, and it is growing. In fiscal 2026 the ten largest customers accounted for 44 percent of revenue (fiscal 2025: 40 percent), and no single customer exceeded 10 percent over the year. For the first quarter of fiscal 2027 the quarterly report for the first time shows two customers at 12 percent each — together about $2.6 billion of quarterly revenue. 65 percent of quarterly revenue came from Asia. None of this is a scandal. But taken together it means: the higher the boom carries, the more concentrated customers, region and contract backlog become.
The first quarter of fiscal 2027 — and what the October 29 call revealed
On October 29, 2026 Sandisk reported its numbers for the first quarter of fiscal 2027 (July 4 through October 2, 2026) as an earnings release attached to a current report (8-K, Item 2.02, Exhibit 99.1); the quarterly report (10-Q) followed a day later. A note on naming: anyone reading about Sandisk’s “third-quarter 2026 results” means this first quarter of the new fiscal year.
What the numbers show
Every figure beat the company’s own guidance of August 5, 2026: $11.03 billion of revenue (guidance $10.30 to $10.80 billion), an adjusted gross margin of 85.1 percent (guidance 83.0 to 85.0 percent; under U.S. accounting rules 85.0 percent against guidance of 83.0 to 84.9 percent) and $49.51 of adjusted earnings per share (guidance $44 to $46). Of every dollar taken in, almost 80 cents were left as operating income (a 79.6 percent operating margin).
“Fiscal first quarter revenue was $11.0 billion, up 23% sequentially, with GAAP net income reported at $8.1 billion ($52.60 diluted net income per share, up 20% sequentially).”
— Sandisk Corporation, SEC earnings release, Exhibit 99.1 to the 8-K of October 29, 2026 (Item 2.02), section “News Summary”
Two details belong to an honest reading. First, the $8.10 billion of net income contains a $513 million book gain on the stake in the Taiwanese memory maker Nanya — money that never flowed; on an adjusted basis Sandisk reports $7.62 billion. Second, the quarter’s cash went almost entirely back to shareholders: $6.36 billion of operating cash flow, of which $5.0 billion went into share repurchases and another $755 million into taxes on vested employee shares. Cash therefore grew by only $374 million to $5.14 billion. Working capital also weighed on cash flow: receivables up $1.88 billion, inventories up $318 million. The inventories deserve a second look: per the quarterly report, days of inventory rose to 166 from 115 a year earlier — intended to serve contract volumes, but also the line where a dip in demand would show first. By segment: Datacenter $4.80 billion (up 61 percent sequentially), Edge $5.83 billion (up 7 percent), Consumer $397 million (down 29 percent). For the second quarter (through early January 2027) Sandisk expects $12.2 to $12.6 billion of revenue and $55 to $57 of adjusted earnings per share before the split.
What the call revealed
Three observations from the earnings call of October 29, 2026 (public transcript), where the Q&A revealed more than the prepared remarks. First, the shift in the driver: in August management had still attributed two thirds of the gain to price; this time CFO Visoso cited “approximately 60% of the increase attributable to volume growth and 40% to higher pricing”. For the second quarter he guided to only “modest” price increases. Second, visibility: “over four years of committed” volumes in August became demand for multi-year contracts that, per management, exceeds the company’s own supply through the end of the decade; even so, the plan remains volume growth in the “mid to high teens” percent range, with capital spending at a mid-single-digit percentage of revenue. Third, the caution behind the optimism: asked about the third fiscal quarter (January to March 2027), Visoso reminded analysts that shipped volume had fallen 19 percent sequentially in that quarter a year earlier: “I would be conservative in your sequential growth from Q2 to Q3.” And on capital allocation, CEO Goeckeler stuck to the line of staying debt-free and returning “100% of excess cash” to shareholders.
The 8-for-1 stock split
Along with the results, Sandisk announced an 8-for-1 stock split (8-K of October 29, 2026, Item 8.01): whoever holds a share on November 9, 2026 receives seven additional shares after the close of trading on November 19; from November 20, 2026 the stock trades split-adjusted. The value of your stake does not change — the cake is simply cut into eight times as many pieces, each one eighth the size. Important for reading this analysis: all prices and per-share figures in this text are pre-split. To compare them with prices from November 20 onward, divide by eight — $1,150.89 becomes about $143.86, and per management the earnings guidance of $55 to $57 per share becomes $6.88 to $7.13.
What the share price made of it
On October 29, 2026, before the results, the stock closed at $1,330.05. The day after — following a quarter above every one of the company’s own forecasts — it fell 13.5 percent to $1,150.89, 51 percent below the June 25, 2026 high and 39 percent below the interim high of September 22, 2026 ($1,887.04). Filings give no reasons for daily moves, and we invent none. What the filings do show is a different punchline: from August to early October Sandisk itself bought back $5.0 billion of its own shares, at average prices of $1,551 and $1,638 apiece — a volume-weighted average of about $1,587 across both periods, rounded to about $1,590 in this text. A buyback is not a price target; at the October 30 close, however, the company could have bought the same shares for a good quarter less — arithmetically, the little over 3.15 million repurchased shares are worth about $1.4 billion less at that price than Sandisk paid for them. The inner know-it-all would have known, of course — afterwards.
Valuation: what the commodity of the digital economy costs
First the arithmetic itself, so you can check it. On October 30, 2026 the Sandisk stock closed at $1,150.89; the cover page of the quarterly report lists 142.3 million shares outstanding as of October 26, 2026 (pre-split). That gives a market value of about $164 billion; our fundamental-data feed shows a similar value, so the cross-check passes. On this basis Sandisk costs 5.7 times the revenue of the last four quarters ($28.97 billion), 9 times equity ($18.13 billion) and about 8.4 times the earnings of the last four quarters ($19.42 billion). Take instead the company’s own guidance for the second quarter of fiscal 2027 ($55 to $57 of adjusted earnings per share, pre-split) and simply annualize it, and you land at a price-to-earnings ratio of about five.
Five. You recognize the pattern from the Micron analysis: the further you extend the recent past, the cheaper the stock becomes. The inner know-it-all eagerly does the math along — and with cyclicals this very calculation is the classic trap, because it takes the earnings peak as its base. So hold the other end of the roller coaster next to it: in fiscal year 2023 the same company earned nothing but lost $2.14 billion, at a gross margin of 7.1 percent. Calculated on that year’s numbers, there would be no price-to-earnings ratio at all. The truth lies somewhere in between, and nobody knows where — not even the 25 analysts in our fundamental data, 21 of whom rate the stock a buy, three a hold and one a sell (data as of October 31, 2026; third-party opinions, not a recommendation from TickerGuard). A price-to-earnings ratio of about eight can be read as the market not trusting these earnings to last.
What sits on the substance side of the scale has, however, grown heavier since the summer: zero financial debt, an undrawn $1.5 billion credit line (extended through 2031 in September), $5.14 billion of cash, $11.49 billion of free cash flow in fiscal 2026 and another $6.31 billion in the first quarter, an $88.9 billion contract backlog with collateral — and a buyback program with $10.5 billion of remaining volume, which at a $164 billion market value would cover a little over six percent of all shares. That is considerably more substance than the market credited this company with in the spring of 2025, when it valued it below book value. On the other side of the scale sits the fact that even this lower price presupposes a gross margin around 85 percent holding for a while — for a product whose price per gigabyte, per the company’s own risk chapter, regularly races in the other direction too. How the market prices perfection and what remains of it when one detail wobbles is something we dissected at the chip inspector KLA.
Opportunities and risks at a glance
What speaks for Sandisk:
- A genuine scarcity tailwind: AI data centers are driving NAND demand; datacenter revenue rose from $269 million in the quarter through October 3, 2025 to $4.80 billion in the quarter through October 2, 2026 and makes up 43.5 percent of revenue (10-Q as of October 2, 2026).
- Historic earnings power: $11.03 billion of quarterly revenue at an 85.0 percent gross margin and $8.10 billion of net income in the first quarter of fiscal 2027, all above the company’s own guidance; $11.49 billion of free cash flow in fiscal 2026.
- A lightning-renovated balance sheet: zero financial debt, $5.14 billion of cash, $18.13 billion of equity (October 2, 2026); $5.0 billion of share repurchases in the quarter and $10.5 billion of remaining buyback authorization.
- A contractual backbone: the contract backlog from uncomfortable truth no. 2 ($88.9 billion as of October 2, 2026); per management, roughly half of fiscal 2027’s and roughly two thirds of fiscal 2028’s supply volume is committed.
- Growth is turning toward volume: in the first quarter of fiscal 2027, per the CFO, about 60 percent of the sequential gain came from volume (closing quarter of 2026: one third).
What speaks against it:
- Year over year, price remains the main driver: revenue up 378 percent on just under 10 percent more volume in the quarter through October 2, 2026; in the Edge business a more than 450 percent higher price per gigabyte on 20 percent lower volume — and the company’s own risk chapter describes overcapacity phases with price crashes as a recurring industry pattern (10-K fiscal year 2026).
- A brake mark at the end customer: the consumer business fell to $397 million (down 29 percent sequentially and 39 percent year over year), volume by more than 70 percent; for the PC market, management conceded falling unit volumes.
- A short, red history: fiscal years 2023 through 2025 brought a combined $4.5 billion of losses. As a standalone company Sandisk has not yet lived through a single complete downturn; the CFO himself urged caution for the seasonally weak third fiscal quarter.
- The Kioxia corset: a purchase obligation for practically the entire flash supply, 50 percent of the fixed costs due even without orders, $838 million of off-balance-sheet lease guarantees, a $2.94 billion maximum loss scenario and $7.14 billion of payment obligations toward Flash Ventures (each as of October 2, 2026) — plus JV clauses that make a takeover harder.
- Growing clusters: two customers at 12 percent of quarterly revenue each, 65 percent of revenue from Asia, 166 days of inventory coverage after 115 a year earlier, $5.0 billion of goodwill.
- The share price remains a roller coaster: 51 percent below the June 25, 2026 high, down 13.5 percent the day after a record quarter; even the company’s own buybacks (see the conclusion) are now under water.
Looking back: what the closing quarter of 2026 changed about this analysis (update of August 12, 2026)
This analysis originally stood on the July 14, 2026 state of knowledge — the quarterly report as of April 3, 2026. On August 5, 2026 Sandisk reported the numbers for the closing quarter and the complete fiscal year 2026 (earnings release as Exhibit 99.1 to an 8-K, Item 2.02). The company itself calls this period “fiscal fourth quarter ended July 3, 2026” — it is the fourth quarter of fiscal 2026. The annual report (10-K) for fiscal 2026 had not yet been filed at that update’s cut-off (August 12, 2026); it followed on August 17, 2026 and is incorporated into this version.
What was surprising back then
Three things. First, the sheer size: $8.97 billion of quarterly revenue came in well above the company’s own guidance of $7.75 to $8.25 billion, and the gross margin rose from 78.4 to 84.6 percent. Of every dollar taken in, 78 cents were left as operating income — a margin normally reported by software houses, not by makers of memory chips. Second, the beginning reversal in the driver: for the first time, roughly one third of the gain came from volume. Third, the capital return: Sandisk repurchased $4.52 billion of its own shares in the closing quarter, and on August 5, 2026 the board added $14 billion; at that point $15.5 billion of authorization remained. For a company that had moved out in February 2025 with a loan in order to wire its parent $1.5 billion, that is a remarkable reversal of roles.
“Fiscal fourth quarter revenue was $8.97 billion, up 51% sequentially, with GAAP net income reported at $6.90 billion ($43.97 diluted net income per share). Sequential revenue growth came approximately one-third from higher volumes and two-thirds from higher pricing.”
— Sandisk Corporation, SEC earnings release, Exhibit 99.1 to the 8-K of August 5, 2026 (Item 2.02), section “News Summary”
What the share price made of it back then
Price remained the main driver at the time — two thirds of the gain — and the consumer business collapsed 32 percent sequentially to $556 million. From the high on June 25, 2026 (closing price $2,335.00) to August 11, 2026 ($1,271.05) the stock lost 46 percent, even though the business delivered records; the day after the results it fell 6.8 percent (closing price August 5: $1,350.50; August 6: $1,258.58). Sandisk has since beaten its guidance at the time for the first quarter of fiscal 2027 ($10.30 to $10.80 billion of revenue) — and at the end of October the next slide followed anyway.
What the Earnings Calls Reveal
We reviewed the public transcripts of Sandisk’s earnings calls in chronological order — first the three calls covering fiscal quarters 2026-Q1 through 2026-Q3 (November 2025 to April 2026), and since October 31, 2026 also the calls of August 5, 2026 (closing quarter of fiscal 2026) and October 29, 2026 (first quarter of fiscal 2027). The overall picture is unusually clear: in each of the five quarters management beat its own guidance by a wide margin and delivered its major announcements on schedule. Revenue in 2026-Q1 came in at $2.31 billion versus a guided $2.1 to $2.2 billion, 2026-Q2 delivered $3.03 billion versus $2.55 to $2.65 billion, 2026-Q3 reached $5.95 billion versus $4.4 to $4.8 billion, the closing quarter $8.97 billion versus $7.75 to $8.25 billion, and the first quarter of fiscal 2027 $11.03 billion versus $10.30 to $10.80 billion.
The central test case was the shift to multi-year contracts. In 2026-Q1 management openly admitted it had virtually no volume or price commitments beyond a single quarter and merely announced talks. By 2026-Q2 the first contract was signed, by 2026-Q3 there were five, by August eight customers — and in October management reported that one of its largest customers had already signed a second tranche. CEO David Goeckeler commented on the April 30, 2026 call (2026-Q3): “I’ve had a lot of people tell me in the last year, it’s never gonna happen. It’s happening.” The promised disclosures now appear in the quarterly report as remaining performance obligations and can therefore be checked: $41.6 billion, $59.8 billion and $88.9 billion at three consecutive reporting dates.
The other datable commitments also hold up under scrutiny: the sequential data-center growth promised for fiscal 2026 was delivered, and the announced capital allocation sequence — invest first, then net cash, then returns — culminated in full debt repayment and share repurchases of $9.5 billion combined in two quarters. The record is not flawless. For 2026-Q3, management had guided bit shipments down by a mid-single-digit percentage; in reality, shipped bits fell sequentially by a high-teens percentage — in October the CFO himself put it at 19 percent. On the August 5, 2026 call, CFO Luis Visoso guided to a gross margin of about 80 percent for the multi-year contracts (“not to pick a specific number, but we do expect to be around 80% for the new business models”), and CEO Goeckeler called a gross margin in the mid-80s a fair return (“I think mid-80s gross margin, I would characterize as a fair return”). Eight days later, at its investor day on August 13, 2026, that became a fixed long-term target: the financial model presented there for fiscal 2028 through 2030 calls for revenue growth in the mid-to-high teens, a non-GAAP gross margin of about 80 percent and a non-GAAP operating margin of about 75 percent (press release of August 13, 2026, not a document filed with the SEC). The target sits below the 85 percent just achieved — management itself is not planning on record margins as a permanent state.
Finally, the forecasting environment deserves context: the company’s own estimate for 2026 data-center exabyte growth rose from the mid-20s (August 2025) via the mid-to-high 40s (November 2025) to the high 60s percent (January 2026) — as the CEO recapped on the January 29, 2026 call. On the April 30, 2026 call he raised it to the mid-70s percent; in October 2026 the CFO spoke of more than a doubling in 2026, and for 2027 he cites about 40 percent. Every revision was disclosed openly — but anyone revising upward that sharply simply has limited visibility. In an upcycle this looks like deliberately cautious guidance; in a downturn the same dynamic can run in reverse just as quickly. After five calls our interim verdict reads: no broken promise, no silent target corrections, a narrative that stayed consistent across all quarters — and in October, for the first time, a CFO explicitly urging analysts to be cautious about the next seasonal low.
A human conclusion
Back to the inner know-it-all and his favorite sentence: “You could have seen that coming.” The cross-examination is over, and the record speaks against him. The record shows no one who openly flagged the spring 2025 low as an opportunity: the market valued the company below book value. The company itself drew the accounting consequence and wrote off $1.8 billion of goodwill. The former parent began disposing of its retained stake months before the explosion. And the autumn of 2026 contradicted him twice more: on October 29 Sandisk delivered the next record quarter — and the next day the stock fell 13.5 percent, to half its June high. Even the company that knows its business better than any outsider bought its own shares from August to early October at about $1,590 apiece, shares that cost $1,151 at the end of October. A buyback is not a price target — but if not even the company itself can see tomorrow, the claim that it is clearly recognizable is exactly that: a claim. Whether a gross margin around 85 percent is a plateau or the top of the roller coaster, nobody knows — not the Greenblatt scanner, not the 25 analysts, not we ourselves, and least of all the know-it-all; in two years he will simply tell you the story differently again. What the filings can give you are the two scales: here a debt-free manufacturer with $8.1 billion of profit in a single quarter, $88.9 billion of contractually committed revenue and growth that, for the first time, leans more on volume — there a commodity producer with three loss years in a row, a fixed-cost corset, two key customers with an eighth of revenue each, and a profit that, year over year, still comes mainly from price. Which scale weighs more for you is your decision — in full knowledge that it is a decision under uncertainty, not one that was obvious in hindsight. And that is exactly as it should be.
Sources
All original documents used in this analysis — to read for yourself:
- Sandisk Corporation — SEC quarterly report 10-Q as of October 2, 2026 (first quarter of fiscal 2027, filed October 30, 2026)
- Sandisk Corporation — SEC earnings release for the first quarter of fiscal 2027, Exhibit 99.1 to the 8-K of October 29, 2026
- Sandisk Corporation — SEC Form 8-K of October 29, 2026, Item 2.02 (results) and Item 8.01 (8-for-1 stock split)
- Sandisk Corporation — SEC annual report 10-K for fiscal year 2026, ended July 3, 2026 (filed August 17, 2026)
- Sandisk Corporation — SEC Form 8-K of September 11, 2026, Item 1.01 ($1.5 billion credit line through 2031)
- Sandisk Corporation — SEC earnings release for the fourth quarter and fiscal year 2026, Exhibit 99.1 to the 8-K of August 5, 2026
- Sandisk Corporation — SEC Form 8-K of August 5, 2026, Item 2.02 (results) and Item 8.01 ($14 billion share repurchase program)
- Sandisk Corporation — SEC annual report 10-K for fiscal year 2025, ended June 27, 2025 (filed August 21, 2025)
- Sandisk Corporation — SEC quarterly report 10-Q as of April 3, 2026 (filed May 1, 2026)
- Sandisk Corporation — SEC quarterly report 10-Q as of January 2, 2026 (filed January 30, 2026)
- Sandisk Corporation — SEC quarterly report 10-Q as of October 3, 2025 (filed November 7, 2025)
- Sandisk Corporation — SEC quarterly report 10-Q as of March 28, 2025 (filed May 12, 2025)
- Sandisk’s complete SEC filing history: EDGAR overview (sec.gov)
- Earnings call transcripts 2026-Q1 through 2026-Q3 (public transcripts, 3 calls) — review as of August 2, 2026
- Sandisk earnings calls of August 5, 2026 and October 29, 2026 (public transcripts; management statements are labeled as call statements in the text and are not used as filing evidence).
- Sandisk Corporation — Press release “Sandisk Details Growth Strategy and Long-Term Financial Model at 2026 Investor Day,” August 13, 2026 (financial model for fiscal 2028 through 2030; not an SEC filing)
- Fundamental data (metrics, quarterly series, price history, analyst ratings; price as of October 30, 2026, analyst data as of October 31, 2026), reconciled with the SEC filings.
- Screener and rating data: our in-house stock scanner (data as of July 8, 2026; scanner membership checked live on July 14, 2026).
Transparency & disclaimer: This analysis is a journalistic contextualization of publicly available information and is not investment advice, not a financial analysis in the regulatory sense, and not a solicitation to buy or sell securities. Stock investments carry substantial risks up to total loss. All information without guarantee; the data cut-off is noted in the text in each case. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this analysis.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2022 | 2023 | 2024 | 2025 | 2026 |
|---|---|---|---|---|---|
| Revenue | 9,754.0 | 6,086.0 | 6,663.0 | 7,355.0 | 20,248.0 |
| Operating Income (EBIT) | 1,200.0 | -2,035.0 | -468.0 | -1,377.0 | 12,389.0 |
| Net Income | 1,064.0 | -2,143.0 | -672.0 | -1,641.0 | 11,433.0 |
| Net Margin | 10.9% | -35.2% | -10.1% | -22.3% | 56.5% |
| Earnings Per Share | 7.39 $ | -14.88 $ | -4.67 $ | -11.32 $ | 73.76 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
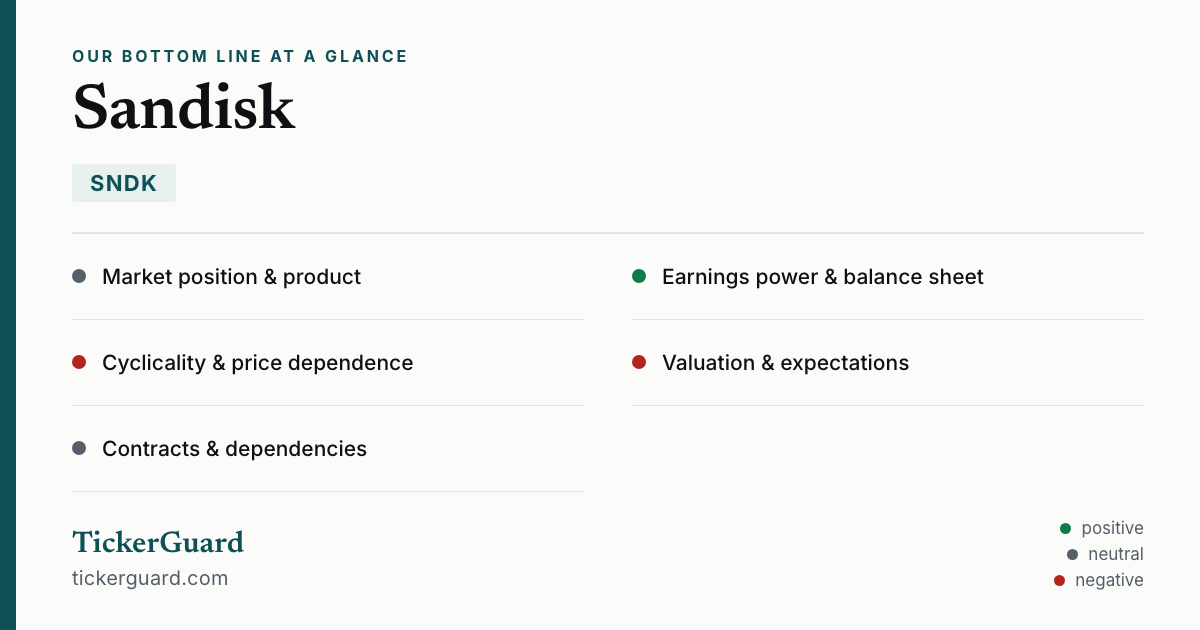
Our Bottom Line at a Glance
- Market position & product neutral
- One of only a few NAND makers in the world, with secured manufacturing access through the Kioxia joint venture. The data-center business grew from $269 million in the quarter through October 3, 2025 to $4.80 billion in the quarter through October 2, 2026 and makes up 43.5 percent of revenue — but the product remains a commodity, and the consumer business shrank 39 percent year over year in the same quarter.
- Earnings power & balance sheet positive
- In the first quarter of fiscal 2027, $11.03 billion of revenue, an 85.0 percent gross margin, $8.10 billion of net income and $6.31 billion of free cash flow; $11.49 billion of free cash flow in fiscal 2026. As of October 2, 2026, zero financial debt, $5.14 billion of cash and $18.13 billion of equity.
- Cyclicality & price dependence negative
- Per the CFO, about 60 percent of the sequential gain in the first quarter of fiscal 2027 came from volume. Year over year, however, volume rose just under 10 percent per the quarterly report against a 378 percent revenue gain. Fiscal 2023 through 2025 brought a combined $4.5 billion of losses, and as a standalone company Sandisk has not yet been through a complete downturn.
- Valuation & expectations neutral
- About $164 billion of market value (closing price $1,150.89 on October 30, 2026 × 142.3 million shares), 8.4 times the earnings and 5.7 times the revenue of the last four quarters. Such a low multiple can be read as doubt about how long the earnings will last; the day after the record quarter the stock fell 13.5 percent.
- Contracts & dependencies neutral
- $88.9 billion of remaining performance obligations as of October 2, 2026, backed by $12.8 billion of bank-held collateral and $1.6 billion of deposits — a genuine first. Against it: the fixed-cost obligation toward Kioxia (maximum loss scenario $2.94 billion) and two customers with 12 percent of quarterly revenue each.
Sandisk is the proof that the same market can price the same company completely differently within twenty months: first the spurned spin-off below book value with a $1.8 billion goodwill write-off, in June 2026 at 25 times book value — and on October 30, 2026, one day after the next record quarter, at nine times. The first quarter of fiscal 2027 brought $11.03 billion of revenue, an 85.0 percent gross margin and $8.10 billion of profit; the contract backlog grew to $88.9 billion, and sequential growth for the first time rests mainly on volume. Even so, the core question stays open: year over year the earnings jump still comes mainly from price, three loss years are only just behind the company, the fixed-cost corset toward Kioxia works against Sandisk in a downturn, and two customers carry almost a quarter of revenue. Whether an 85 percent gross margin is a plateau or the top of the roller coaster will be decided by the memory cycle — not by hindsight bias’s “you could have known”. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
Yellow, because earning power across a full memory cycle is unproven — fiscal 2023 through 2025 produced a combined loss of $4.5 billion — and nearly all flash supply comes from the Kioxia joint venture; red would require a substantive finding, and there is none: as of October 2, 2026 Sandisk is debt-free and holds $5.14 billion in cash.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- Sandisk reports in an offset fiscal year (ending: the Friday closest to June 30). The results reported on 29.10.2026 cover the FIRST quarter of FY 2027 (04.07. through 02.10.2026), on the calendar essentially the third quarter of 2026. All periods are explicitly dated in the text.
- 8-for-1 stock split: split-adjusted trading from 20.11.2026. All prices, share counts and per-share values in this analysis are PRE-split; to compare with later prices, divide by eight (or multiply share counts by eight).
- The source of the first-quarter FY 2027 figures is the quarterly report (10-Q as of 02.10.2026, filed 30.10.2026) and the earnings release (Exhibit 99.1 to the 8-K of 29.10.2026). The points left open in August (remaining performance obligations of $59.8 billion, refund liabilities) are documented in the annual report (10-K) for FY 2026 of 17.08.2026.
- Figures on the sequential volume/price split (about 60/40), on the booking status of 2027/2028 supply volumes and on the credit quality of the counterparties come from the earnings call of 29.10.2026 (public transcript), not from a filed report — they are labeled as such in the text.
- Price and valuation figures are dated October 30, 2026 (closing price $1,150.89, 142,289,365 shares per the 10-Q cover page as of 26.10.2026, about $164 billion of market value; the feed value passes the cross-check). An earlier version cited a feed market value of about $400 billion that failed the cross-check. Analyses are evergreen; daily prices are not a buy argument.
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of October 31, 2026. Stock Watch will tell you what's changed at SNDK since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Sandisk Corp (SNDK), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Sandisk (Nasdaq: SNDK) of Milpitas, California, makes NAND flash memory — the chips in SSDs, smartphones and memory cards. Its end markets are called Datacenter, Edge and Consumer. The memory wafers are made in the Flash Ventures joint venture with Kioxia in Japan. In fiscal year 2026 (ended July 3, 2026) Sandisk generated $20.25 billion of revenue, and in the first quarter of fiscal 2027 (through October 2, 2026) alone $11.03 billion.
Sandisk was a subsidiary of Western Digital until February 2025. On February 21, 2025 WDC spun off the flash business; SNDK has traded on the Nasdaq since February 24, 2025. Afterwards the share price fell so low that the market value sat below book value. The mandatory test showed an impairment: Sandisk wrote off $1.8 billion of goodwill in the quarter through March 28, 2025. As of October 2, 2026, $5.0 billion of goodwill remains on the balance sheet.
The results for the first quarter of fiscal 2027, July 4 through October 2, 2026 — on the calendar essentially the third quarter of 2026, because Sandisk’s fiscal year ends in early July. Revenue was $11.03 billion (up 23 percent sequentially), the gross margin 85.0 percent, net income $8.10 billion, or $7.62 billion adjusted. Every figure beat the company’s own guidance. The quarterly report (10-Q) followed on October 30, 2026.
On October 29, 2026 Sandisk announced it would split each share into eight: shareholders of record on November 9, 2026 receive seven additional shares per share after the close of trading on November 19; from November 20, 2026 the stock trades split-adjusted. The value of a holding does not change. All prices and per-share figures in this analysis are pre-split; divide them by eight to compare them with later prices.
Since early 2026 Sandisk has been signing multi-year supply contracts with major customers, which it calls “New Business Models”. Per the quarterly and annual reports, the resulting remaining performance obligations rose from $41.6 billion (April 3) via $59.8 billion (July 3) to $88.9 billion (October 2, 2026); about 20 percent is expected to become revenue within twelve months. Customers backed this with $12.8 billion of collateral at banks and $1.6 billion of deposits with Sandisk.
Very: Sandisk holds 49.9 percent of three Flash Ventures joint companies with Kioxia (agreements through 2034) and must obtain substantially all of its flash memory from them. Sandisk carries 50 percent of the fixed costs — even if it orders nothing —, guaranteed about $838 million of fab equipment leases as of October 2, 2026 and puts the maximum loss scenario from the construct at $2.94 billion. The agreements can also make a takeover harder.
That depends on the yardstick. On October 30, 2026 the stock closed at $1,150.89; at 142.3 million shares that is about $164 billion of market value — 5.7 times the revenue and 8.4 times the earnings of the last four quarters. Annualizing the guidance for the second quarter gives a price-to-earnings ratio of about five. That is exactly the cyclical trap: the same company still lost $2.14 billion in fiscal year 2023.
Yes. In all five reviewed quarters (fiscal 2026 and the first quarter of fiscal 2027), revenue, margin and earnings beat the company’s own guidance — most recently $11.03 billion of revenue versus a guided $10.30 to $10.80 billion. The promise to sign multi-year contracts was kept. Caveats: the shipment volume guided for the third quarter of fiscal 2026 was missed. A fixed margin target has only existed since the August 13, 2026 investor day: a non-GAAP gross margin of about 80 percent for fiscal 2028 through 2030 — below the 85 percent just achieved.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.