Duos Technologies: A Record Profit From a Sale, Not From AI Rent
Duos Technologies' GPU program lasted one quarter, its rail unit went to a company half-owned by the then interim CFO, and its record first-half 2026 profit of $44.4 million came, according to its filings with the U.S. securities regulator, the SEC, from the sale of a stake — after losses in every year from 2019 through 2025. What remains is a landlord of data center space for AI workloads whose large leases pay only after acceptance. Add a partner in four roles and more than four times as many shares as in spring 2024. Not investment advice — just an attempt to look past the new address and into the moving boxes.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 30, 2026
- Closing price
- 6.20 $ -4.02%
- Market Capitalisation
- 0.2 $B
- P/E
- 5.2
- Growth Score
- 6/10
- AAQS
- 5/10
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 5.40 $ to 14.60 $ · Last price: 6.20 $ (As of: October 30, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
From May 28 to October 30, 2026, shares of Duos Technologies (Nasdaq: DUOT) fell from $14.64 to $6.20 (closing prices per fundamental data), a decline of 58 percent. At the same time, according to fundamental data (as of November 1, 2026), about 24 percent of the free float was sold short — nearly one in four freely tradable shares is a bet on further declines. Behind this sits an investor trap that starts with a move. A company relocates from a dull old address to the hottest street in town — and everyone stares at the new nameplate on the door. Nobody notices that the moving boxes are full of old bills, or that the move itself was paid for at a steep price. Call it the moving-day trap. In 2026, the hottest street on the stock market is called “AI data centers.” Duos, based in Jacksonville, Florida, moved there in just over two years: a maker of portals that scan moving railcars with cameras and artificial intelligence became a landlord of data center space. Its October 20, 2026, investor presentation sums up the new model in one line: “We own the building. Our customers bring the compute.” Before you let the new nameplate guide you, let’s open the boxes together: the annual report (10-K) for 2025, the quarterly reports (10-Q) through June 30, 2026, and the current reports (8-K) since. Anyone who files false statements with the U.S. securities regulator, the SEC, risks penalties — which makes these filings some of the most reliable sources there are. In the end, you decide.
What Duos Technologies Actually Does — From Railcar Scanner to Data Center Landlord
For many years, the heart of Duos was the Railcar Inspection Portal: a gate of cameras and computers that freight trains roll through at full speed while it automatically flags damage on every car. The 10-Q for June 30, 2026, calls this the “founding and legacy business,” which accounted for the “substantial majority of its operations, revenues and workforce.” From 2024 on, Duos built three new legs. In July 2024 came Duos Edge AI, which sets up small modular data centers in rural areas and rents out data center space. Late 2024 brought Duos Energy: Duos helped investment firm Fortress buy about 850 megawatts of mobile gas turbines from APR Energy, then ran the fleet under an asset management agreement and received a 5 percent stake in the parent company. In 2025, the third leg followed: the Technology Solutions sourcing business, which procures and delivers equipment for data center operators; in 2026, it became its own subsidiary, Duos Technology Solutions, Inc., and was expanded.
Then things moved fast. On July 14, 2026, Duos bought its first own data center in Columbus, Georgia — according to the 10-Q for $30.0 million: $15.0 million in cash and up to $15.0 million through a note to the seller that is only payable as additional power reaches the site and that the seller may also take in Duos shares at $10.50 (8-K of July 20, 2026). On August 5, 2026, Duos sold the rail business; on September 30, 2026, the GPU program it had only just built. Put simply: Duos wants to be the owner of a parking garage for high-performance computers. It provides the building, power, cooling and security; the tenants bring their own servers and pay rent per kilowatt. That defines the central tension of this analysis, and it runs through every chapter: Duos’s story is new and is about years of AI rent — but the numbers in its filings so far come from asset sales, equity raises and a business that no longer exists.
Company history for investors
-
2024
Duos Edge AI and the APR contract
Duos Edge AI is formed in July; in late December comes the contract to run Fortress's gas turbines plus a 5% stake. For shareholders: a second leg next to rail technology.
-
2025
Revenue nearly quadruples, the loss remains
Revenue rises to $27.0 million, with 69% and 13% coming from two related-party customers. The bottom line still shows a $9.8 million loss.
-
2026
About $120 million of fresh equity
About $65 million at $7.50 in March, about $55 million at $9.50 in June. For shareholders: plenty of cash, but many more shares.
-
2026
Rail unit and GPU program sold
On August 5, the rail unit goes to a company half-owned by the then interim CFO; on September 30, the GPU program goes to Axe Compute. What remains is the data center landlord.
How the Stock Landed on Our Desk
Duos Technologies made our research list through our in-house Reddit hype scanner — though it is hardly a storm. According to ApeWisdom, the stock had one mention in 24 hours on November 1, 2026, and two the day before. Another figure stands out more: according to fundamental data (as of November 1, 2026), about 5.8 million Duos shares were sold short, roughly 24 percent of the free float. Short sellers bet on falling prices — so nearly one in four freely tradable shares is a bet against the relocation story. The price path fits: from the year’s highest close ($14.64 on May 28, 2026) the stock fell to $6.20 by October 30, 2026, a decline of 58 percent. Classic ratios from our scanners mislead at Duos: the price-to-earnings ratio looks low because a one-time gain inflates earnings. So keep this in mind from the start: At Duos, past profit does not matter — what matters is whether the signed leases actually turn into payments from late 2026 on.
The Numbers Over the Years — An Honest Look
First, what Duos really achieved in 2026 — and it is a lot. Cash grew from $15.5 million at the end of 2025 to $112.3 million as of June 30, 2026, and equity from $48.6 million to $207.4 million. Gross margin of continuing operations was 54.1 percent in the first half of 2026. In the second quarter, continuing operations posted a small operating profit of about $49,000 — on a full-year basis, Duos had an operating loss in every fiscal year from 2018 through 2025. The Technology Solutions sourcing business brought in $3.2 million in the second quarter, becoming the largest revenue line; its backlog stood at about $28 million according to the August 17, 2026, results release. And there are signed contracts: besides the Axe Compute agreements for 55 megawatts, a five-year agreement with a large cloud provider (a “hyperscaler”) for 10 megawatts in Columbus with a total contract value of more than $111 million (presentation of October 20, 2026).
The chart shows where Duos is coming from — net income since 2019:
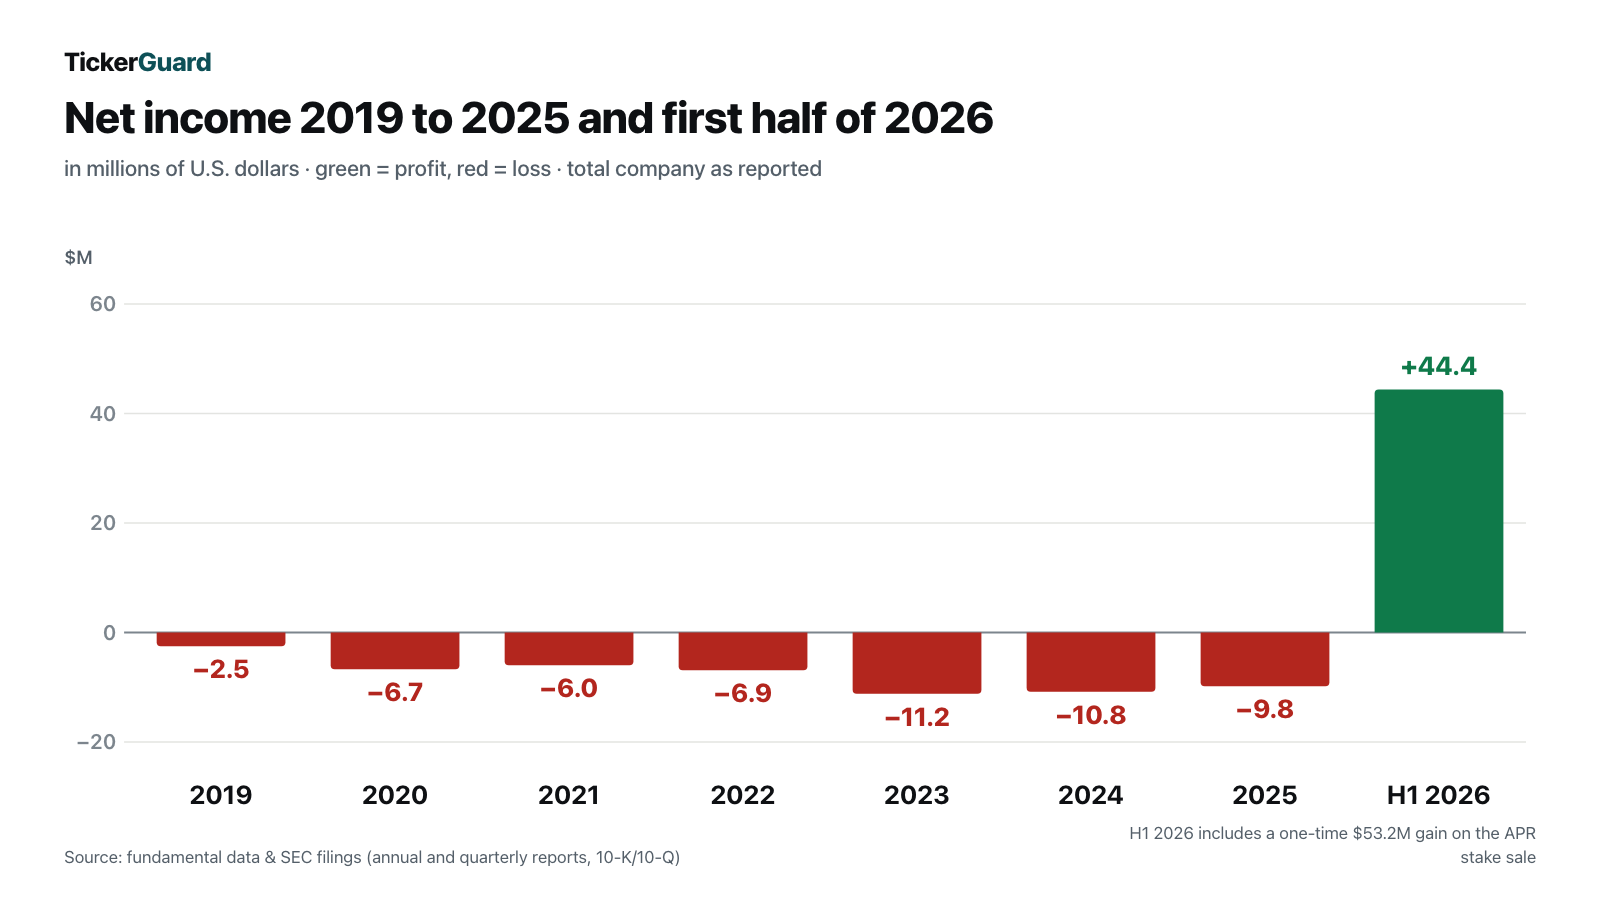
The seven red bars add up to a loss of about $53.9 million — almost exactly the one-time gain of $53.2 million that carries the green bar. Cash flow from operations was negative in every year from 2018 through 2025 as well. In the first half of 2026 it was a positive $11.4 million; the 10-Q attributes this mainly to collected related-party receivables and customer prepayments, including the GPU customer’s $18.8 million deposit. In short: Duos’s coffers are full in 2026 — but they were filled by shareholders, a stake sale and customer deposits, not by rent.
What the Filings Say — The Uncomfortable Truths
Uncomfortable Truth No. 1: The Record Profit Is a Gain on a Sale
The $44.4 million first-half profit looks like proof that the move worked. The 10-Q tells a different story. Fortress’s company New APR Energy sold substantially all of its assets in May 2026, and Duos cashed in on its 5 percent stake:
“In the second quarter of 2026, substantially all of New APR’s assets were sold to a third party, and the Company realized the value of its 5% ownership interest in Sawgrass Parent in the amount of approximately $60 million, consisting of approximately $50.4 million of cash distributions received and approximately $10.0 million withheld to satisfy potential indemnification and other obligations, which will be distributed to the Company following the holdback period (see Note 8).”
— Duos Technologies Group, Inc., 10-Q for June 30, 2026, Note 1
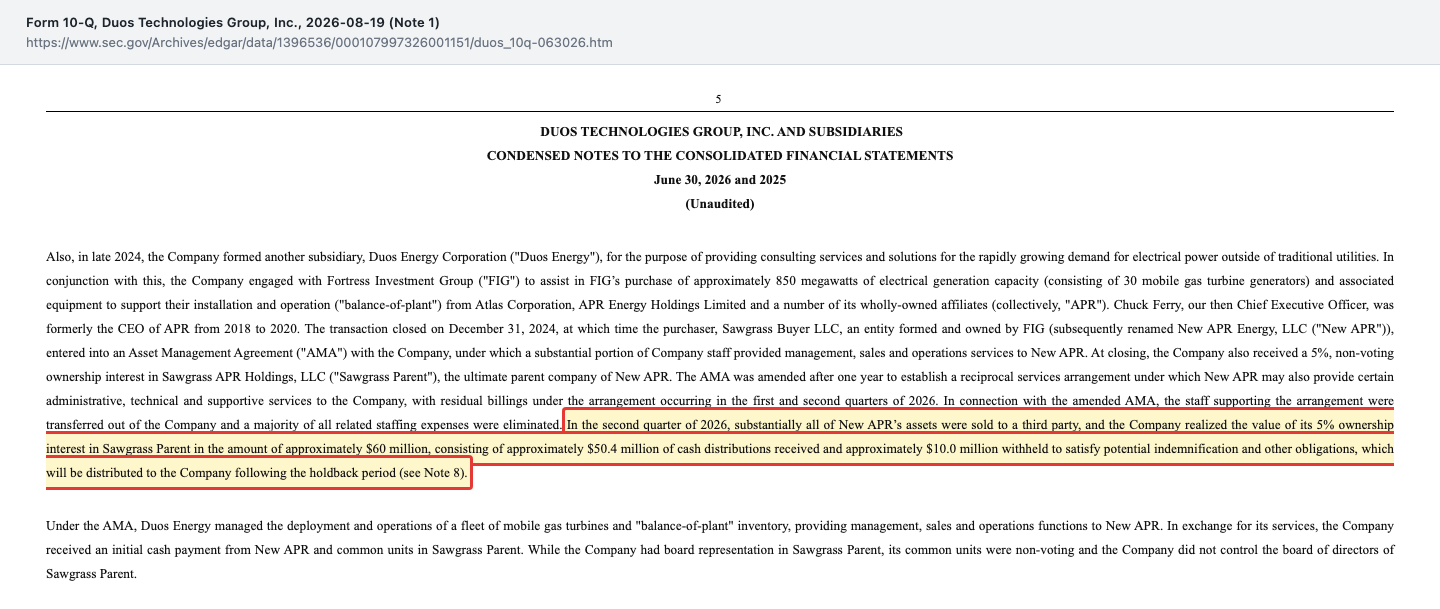
The stake was carried at $7.2 million, leaving a book gain of $53.2 million; income taxes of just under $5.0 million followed. Without that item, continuing operations had a $3.1 million operating loss in the first half of 2026. Revenue has a catch, too: of the $8.32 million of first-half revenue, $4.46 million came from services to related parties around New APR — a business that winds down with the sale. According to the 10-Q, Chuck Ferry, Duos’s CEO at the time, was CEO of APR from 2018 to 2020. Put simply: Duos did not pay for its new house with rent, but by selling a family heirloom. An heirloom can only be sold once.
Uncomfortable Truth No. 2: The GPU Program — Deposited, Budgeted, Sold After One Quarter
In spring 2026, Duos built its own GPU program — GPUs being the specialized chips on which AI models are trained and run. Through the operator Hydra Host, Duos committed about $145 million for servers with 2,304 NVIDIA B300 chips and had already deposited $68.8 million by June 30, 2026. The tenant was a single customer, which paid an $18.8 million deposit in May 2026. The 10-Q names the risk plainly:
“Revenue will be significantly concentrated with a single customer agreement for use of all purchased GPU servers. In the arrangement, the Company bears the full risk of customer nonpayment, as the third party operator, Hydra Host, does not guarantee customer credit performance.”
— Duos Technologies Group, Inc., 10-Q for June 30, 2026, Note 13
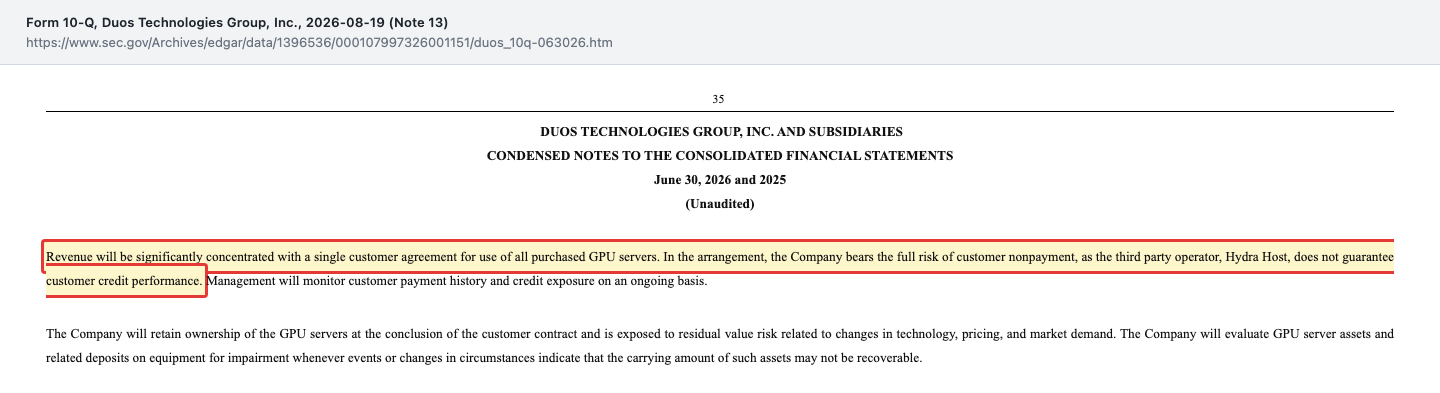
On the second-quarter call on August 17, 2026, this program was still the main pillar of the outlook. Then interim CFO Adrian Goldfarb laid out that about $26 million of the targeted 2026 revenue of more than $50 million would come from GPU rentals. Six weeks later, the program was sold:
“As consideration, Axe (i) repaid in full the SPV’s pre-existing debt of approximately $87.8 million and (ii) agreed to pay the Company a deferred purchase price of $715,000 per month for a period of 60 months, which must be repaid within the earlier of 12 months following closing of the transaction or the date that Axe or any of its affiliates enters into a loan or other financing secured by the cluster.”
— Duos Technologies Group, Inc., 8-K of October 5, 2026, Item 1.01
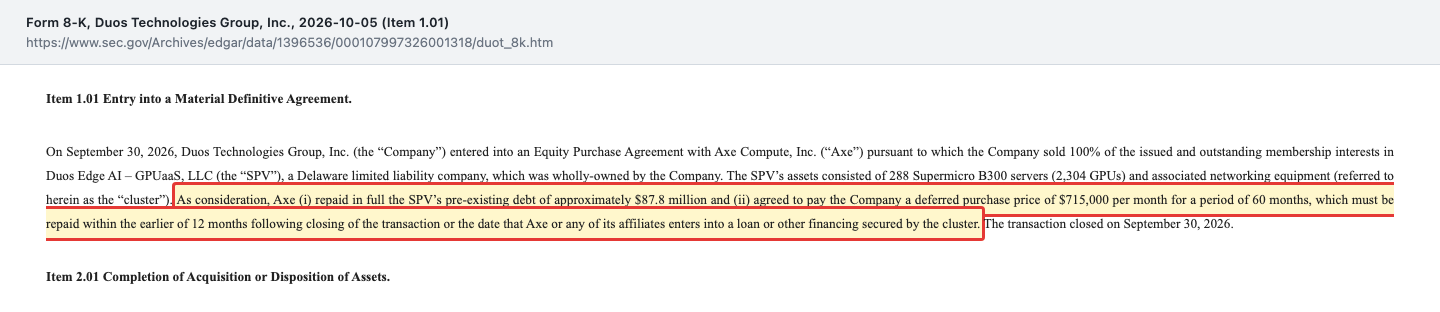
Duos presents the sale as a liberation: about $98.1 million of planned equipment financing is gone, and capital now goes into buildings instead of servers. That may be right. But two figures belong side by side: $68.8 million of its own deposits as of June 30, 2026, and $42.9 million of purchase price in installments. What sits in between — such as the customer’s $18.8 million deposit — whether the deal ends in a loss or a gain, and whether the outlook of more than $50 million of revenue holds without its own GPU business will only be visible in the 10-Q for September 30, 2026, which had not been filed as of November 1, 2026. New CFO Chris DeAlmeida nevertheless confirmed the outlook unchanged on October 5, 2026; according to the release, a revised five-year agreement with the existing GPU customer in Columbus is even expected to increase the revenue Duos recognizes from it over the contract’s life. According to CEO Doug Recker on the August 17, 2026, call, this customer is a large cloud provider that Duos does not name. Its agreement is separate from the agreement for another 10 megawatts of pure colocation with a large cloud provider in the same building; whether the same company stands behind both agreements, Duos does not disclose.
And the installment clause in plain words: the 60 monthly installments would be spread over five years, but per the 8-K, Axe must repay the deferred purchase price no later than twelve months after closing — or earlier, as soon as Axe takes out a loan secured by the computers. Whether the full $42.9 million or a discounted remaining balance is then due, the filing does not say.
Uncomfortable Truth No. 3: One Partner, Four Roles
The buyer of the GPU entity is Axe Compute, Inc. (Nasdaq: AGPU). But since fall 2026, Axe is far more than a buyer for Duos. It is also the debtor on the $42.9 million purchase price, the supplier of the compute capacity Duos now leases to keep serving the existing GPU customer in Columbus, and above all the largest customer: in August 2026, two Duos project entities signed five-year hosting agreements for a combined 55 megawatts with more than $500 million of base payments, announced on August 17, 2026. The filing contains an important caveat:
“Billing under each agreement is subject to successful completion, ready-for-service testing, and Axe Compute’s written acceptance of the applicable deployment.”
— Duos Technologies Group, Inc., 8-K of August 17, 2026, Exhibit 99.1
Duos has not yet disclosed the sites for the 55 megawatts; they are to be ready from late 2026 into early 2027. Put simply: Duos sold its computers to a partner, leases compute capacity from it, gets paid for them in installments — and at the same time is building that partner a large new house, for which rent is due only after the partner accepts it. That can be a strong partnership. For you as a shareholder, though, it means: a large part of Duos’s future depends on the ability and willingness of a single company to pay. More on this concentration risk in our side-finds entry.
Uncomfortable Truth No. 4: The Founding Business Went to a Company Half-Owned by the Then Interim CFO
The rail unit, Duos Technologies, Inc., was the heart of the old company. On August 5, 2026, it changed hands — to a company half-owned by the then interim CFO himself:
“The Purchaser is owned 50% by Adrian Goldfarb, the Company’s Interim Chief Financial Officer and the Managing Member of the Purchaser, and 50% by Javier G. Acosta, a private investor. Accordingly, the Divestiture is a related party transaction.”
— Duos Technologies Group, Inc., 8-K of August 11, 2026, Item 2.01
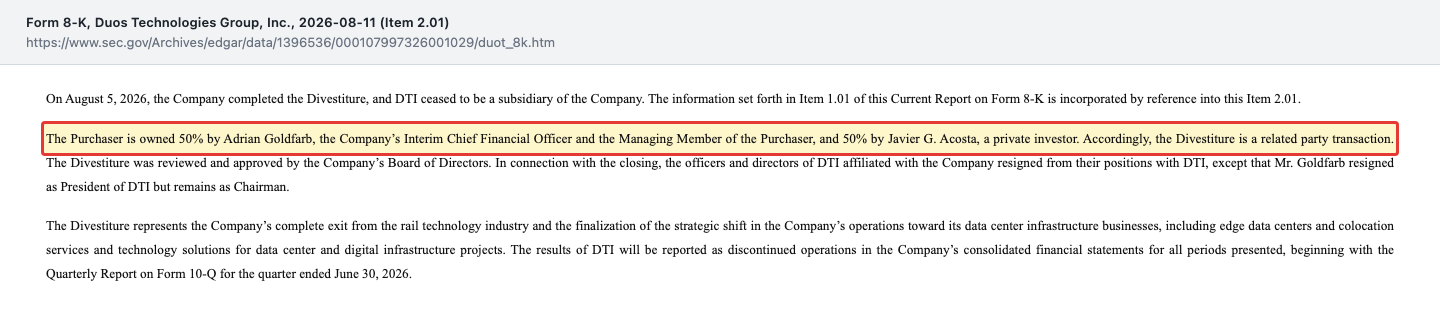
The terms per the 8-K: before the sale, Duos put $3.5 million of cash into the rail unit and received in return a promissory note for $5.44 million, bearing 5 percent interest and not due until August 5, 2031. The amount can still shrink if completing inspection portals for customers in New York and Maryland costs more than those customers pay. The board reviewed and approved the deal, and Duos earns a 5 percent fee on transition services through the end of 2026. With related-party transactions, it remains hard for shareholders to verify whether the price matches a sale to an outside buyer; according to the 10-Q, Duos plans to report the result of the sale in the third quarter of 2026. Since August 24, 2026, Goldfarb has been back as an advisor to the CEO; the CFO is now Chris DeAlmeida.
Uncomfortable Truth No. 5: The Move Was Paid For With New Shares
Every move costs money. Duos paid for this one mainly with new shares. Put simply: when a company issues new shares, the same cake is cut into more slices — your slice gets smaller even if the cake grows. In March 2026, Duos sold 8.67 million new shares at $7.50 (about $65 million); in June 2026, another 2.0 million shares and 3.8 million pre-funded warrants at $9.50 (about $55 million). The chart shows the result:
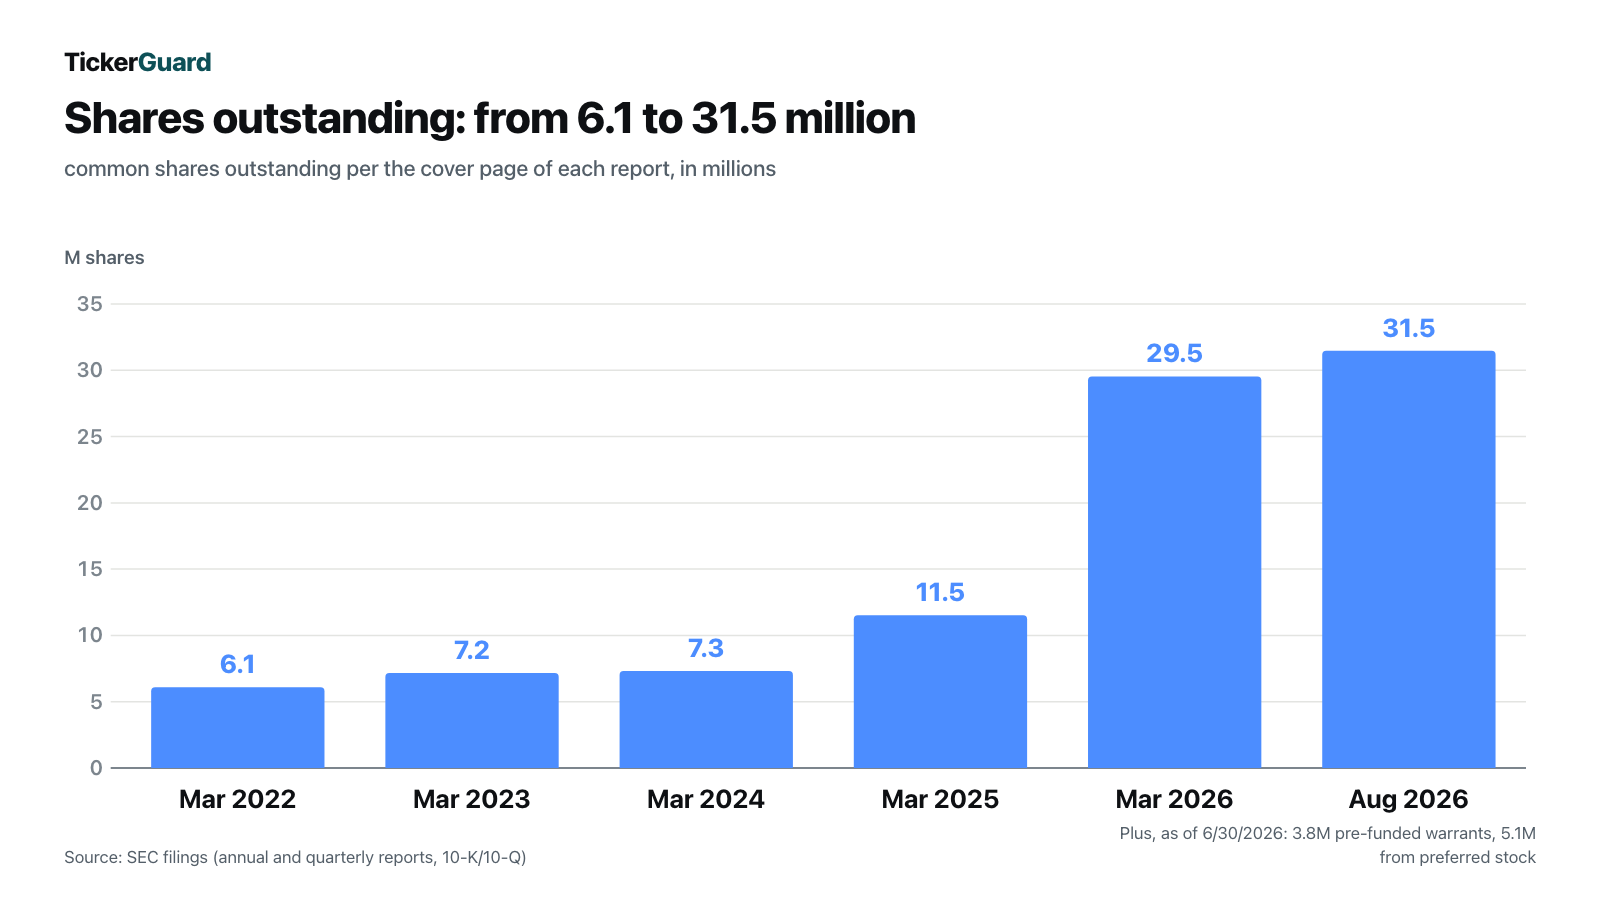
Add up everything that can become stock — 31.47 million shares outstanding (August 18, 2026), 3.8 million pre-funded warrants at $0.001, about 5.1 million shares from Series D and E preferred stock, 0.73 million warrants and about 0.2 million employee options (each as of June 30, 2026) — and you get about 41 million shares. On top come equity grants to management: under his agreement of August 17, 2026, CEO Doug Recker can receive up to 880,000 more shares, with the performance portion able to vest at up to double on outperformance; the CFO and COO each received 200,000. And the seller of the Columbus data center may take his up to $15 million in shares at $10.50. To be fair: Recker himself bought 9,250 shares at an average of $9.14 on September 22, 2026, and chairman James Craig Nixon bought about 5,800 shares at $8.50 to $8.60 on September 18 (insider filings, Form 4). Measured against the October 30, 2026, close ($6.20, per fundamental data), these purchases at $8.50 to $9.14 were about 27 to 32 percent under water. Remember: Anyone who owns a Duos share today shares the success with more than four times as many co-owners as in spring 2024.
Valuation: Roughly Book Value — but What Is in the Books?
At $6.20 (close on October 30, 2026), Duos had a market value of about $195 million, or about $219 million including the pre-funded warrants. Equity stood at $207.4 million as of June 30, 2026 — so the stock trades at roughly book value, meaning what remains on the balance sheet after all liabilities. That sounds like a safety net, but it is only a snapshot: as of June 30, the books held $68.8 million of GPU deposits that have since been replaced by a $42.9 million installment receivable from Axe, plus $10.0 million of APR purchase price held back. Since then, Duos paid the cash portion of the Columbus purchase ($15.0 million, $2.8 million of which had already been placed in escrow as a deposit) and transferred $3.5 million into the rail unit it sold. How much cash was left as of September 30, 2026, will only show in the next quarterly report. Measured against the 2026 revenue outlook of more than $50 million, the market pays about four times revenue. Whether that is cheap or expensive depends solely on whether the outlook holds without its own GPU business. The view of the pros: according to fundamental data (as of November 1, 2026), three analysts are covered — too few for a reliable picture. We have walked through how markets treat landlords of AI data centers whose rent still has to start flowing in our analyses of Applied Digital and Soluna: what matters is not the size of the contracts but the day the first rent is paid.
Upside and Risks at a Glance
What speaks for Duos Technologies:
- Plenty of cash and hardly any debt: $112.3 million of cash and $207.4 million of equity as of June 30, 2026; Axe took over the GPU program’s equipment financing. The only open item is a contingent note to the seller of the Columbus data center of up to $15 million, payable only once additional power reaches the site.
- Signed contracts: 55 megawatts with Axe Compute (more than $500 million of base payments over five years) and 10 megawatts with a large cloud provider in Columbus (more than $111 million).
- Its own operating data center in Columbus, Georgia, and a fast-growing sourcing business (Technology Solutions: $3.2 million of revenue in the second quarter of 2026, backlog about $28 million).
- Gross margin of 54.1 percent in the first half of 2026 and a small operating profit in the second quarter; insider purchases by the CEO and the chairman in September 2026.
What speaks against it:
- The 2026 profit is a one-time gain: $53.2 million from the APR sale; every year from 2019 through 2025 was a loss, and operations still lost money in the first half of 2026 (−$3.1 million).
- Concentration risk Axe Compute: buyer, installment debtor ($42.9 million), supplier and largest customer at once; rent flows only after acceptance.
- Open outlook: about $26 million of the more than $50 million of 2026 revenue was to come from the GPU business that has since been sold; the 10-Q for September 30, 2026, was still outstanding as of November 1, 2026, and the 10-Q for June 30 came only after a filing extension.
- Heavy dilution (7.3 to 31.5 million shares since March 2024, potentially about 41 million) and a sale of the rail unit to a company half-owned by the then interim CFO.
- High short interest (about 24 percent of the free float according to fundamental data, November 1, 2026) and a 58 percent price decline between late May and late October 2026.
A Human Conclusion
Back to the moving-day trap from the beginning. Its core is not that the new address is bad — data center space for AI is in demand in 2026, and Duos has its own building there, cash on hand and signed contracts. Its core is that the new nameplate makes you forget what is in the moving boxes: seven loss years, a profit from a one-time sale, a GPU program handed off again after one quarter, a founding business that went to a company half-owned by the then interim CFO, and more than four times as many shares as in spring 2024. So the honest question for you is not “Is AI the future?” but: Would you buy Duos if it still scanned railcars and showed the same numbers? If your answer changes only because of the new nameplate, you are buying the address, not the business. Three numbers will decide whether the move becomes a fresh start: 2026 revenue against the promised more than $50 million, the first billed rent from the Axe agreements, and cash at year-end. What you make of it is your decision. And that is how it should be.
Sources
All primary documents used in this analysis — to read for yourself:
- Duos Technologies Group, Inc. — SEC quarterly report 10-Q for June 30, 2026 (filed August 19, 2026)
- Duos Technologies Group, Inc. — SEC current report 8-K of August 19, 2026, Exhibit 99.1 (second-quarter results, 2026 outlook) and Exhibit 99.2 (transcript of the August 17, 2026, call)
- Duos Technologies Group, Inc. — SEC quarterly report 10-Q for March 31, 2026 (filed May 15, 2026)
- Duos Technologies Group, Inc. — SEC annual report 10-K for 2025 (filed March 31, 2026)
- Duos Technologies Group, Inc. — SEC prospectus supplement 424B5 of June 17, 2026 (offering at $9.50)
- Duos Technologies Group, Inc. — SEC current report 8-K of July 20, 2026 (Columbus data center purchase)
- Duos Technologies Group, Inc. — SEC current report 8-K of August 11, 2026 (rail divestiture)
- Duos Technologies Group, Inc. — SEC current report 8-K of August 17, 2026, Exhibit 99.1 (hosting agreements with Axe Compute)
- Duos Technologies Group, Inc. — SEC current reports 8-K on management changes of August 18, August 26, September 17 and October 13, 2026
- Duos Technologies Group, Inc. — SEC current report 8-K of October 5, 2026 (sale of the GPU entity) with Exhibit 99.1
- Duos Technologies Group, Inc. — SEC current report 8-K of October 20, 2026, Exhibit 99.1 (LD Micro presentation)
- Full SEC filing history including insider filings (Form 4): EDGAR overview Duos Technologies (sec.gov)
- Fundamental data (prices, short interest, analyst targets; as of November 1, 2026), cross-checked against the SEC filings and the SEC’s XBRL data series.
- Reddit mentions: ApeWisdom (retrieved November 1, 2026); surfaced by our in-house Reddit hype scanner.
Transparency & disclaimer: this analysis is journalistic commentary on publicly available information. It is not investment advice, not a regulated investment research product and not a solicitation to buy or sell securities. Equity investments carry substantial risk up to and including total loss. All information is provided without warranty; the as-of date for each figure is stated in the text. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this analysis.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 8.3 | 15.0 | 7.5 | 7.3 | 27.0 |
| Operating Income (EBIT) | -7.5 | -6.9 | -11.4 | -11.0 | -9.8 |
| Net Income | -6.0 | -6.9 | -11.2 | -10.8 | -9.8 |
| Net Margin | -72.7% | -45.7% | -150.5% | -147.8% | -36.4% |
| Earnings Per Share | -1.63 $ | -1.11 $ | -1.56 $ | -1.39 $ | -0.64 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
Our Bottom Line at a Glance
- Business model neutral
- Landlord of data center space for AI workloads with its own site in Columbus and agreements for 55 megawatts (Axe Compute) and 10 megawatts (hyperscaler); rent from the large agreements only flows after acceptance, targeted from late 2026.
- Earnings quality negative
- First-half 2026 profit of $44.4 million comes from the APR stake sale ($53.2 million book gain) — the one-time gain exceeds the entire first-half profit, so without it there would be a loss; continuing operations −$3.1 million; losses in every year from 2019 through 2025.
- Balance sheet & liquidity positive
- $112.3 million of cash and $207.4 million of equity as of June 30, 2026, no meaningful financial debt apart from a contingent note to the seller of the Columbus data center of up to $15 million (payable only once additional power arrives, also payable in shares at $10.50); Axe took over the GPU financing. Cash as of September 30, 2026, not yet reported.
- Customer concentration negative
- Axe Compute is buyer, installment debtor ($42.9 million), supplier and largest customer at once; in the first half of 2026, $4.46 million of $8.32 million of revenue still came from related parties around New APR.
- Governance & dilution negative
- Rail unit sold to a company half-owned by the then interim CFO (8-K of August 11, 2026); share count up from 7.3 (March 2024) to 31.5 million (August 2026), potentially about 41 million.
Duos Technologies is the moving-day trap in its purest form: the new nameplate reads AI data center, cash is plentiful at $112.3 million, and there are agreements with a combined contract value of more than $600 million. The filings, however, show a profit from a one-time stake sale, seven loss years, a GPU program sold after one quarter, a partner in four roles and a share count that more than quadrupled. Buyers are betting that the leases actually turn into payments from late 2026 on. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
The balance sheet is healthy as of June 30, 2026, but the new business has not yet proven that it makes money: the 2026 profit comes from a one-time sale, the large leases are billed only after acceptance and depend heavily on Axe Compute. Yellow because the turnaround is unproven and customer concentration is high, without a documented existential risk such as over-indebtedness or a going-concern warning. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- This analysis was triggered by our in-house Reddit hype scanner; per ApeWisdom (retrieved 11/01/2026), 1 mention in 24 hours, 2 the day before. Shares sold short about 5.8 million, or about 24% of the free float (fundamental data, as of 11/01/2026). Price references: $14.64 (close 05/28/2026), $11.68 (06/12/2026, per 424B5), $6.20 (close 10/30/2026).
- Data as of: the latest periodic report is the 10-Q for 06/30/2026 (filed 08/19/2026 after an NT 10-Q); the 10-Q for 09/30/2026 had not been filed as of 11/01/2026. Earnings for 2019 through 2025 refer to the total company as reported (including the rail unit); the first-half 2026 operating result covers continuing operations only. The sum of losses 2019 through 2025 ($53.9 million) and the potential share count (about 41 million) are our own calculations from the filings.
- Not to be confused: Duos Technologies Group (DUOT) is the listed parent; Duos Edge AI is a subsidiary, not a separately listed company. Axe Compute (AGPU) is an independent Nasdaq-listed company.
Stock Watch
This analysis is as of November 1, 2026. Stock Watch will tell you what's changed at DUOT since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Duos Technologies Group Inc (DUOT), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Duos Technologies Group (Nasdaq: DUOT) of Jacksonville, Florida, rents out data center space for AI workloads: Duos provides the building, power, cooling and security, and customers bring their own servers. It also runs the sourcing service Duos Technology Solutions. Its first owned data center has been in Columbus, Georgia, since July 14, 2026. The former rail unit, which made AI-based inspection portals for railcars, was sold on August 5, 2026.
The $44.4 million of net income in the first half of 2026 comes from a one-time item: Duos sold its 5 percent stake in New APR Energy and booked a $53.2 million gain — more than the entire first-half profit. Without it, there would be a loss; continuing operations had a $3.1 million operating loss. From 2019 through 2025, Duos lost money every year, about $53.9 million in total.
By June 30, 2026, Duos had deposited about $68.8 million toward servers with 2,304 NVIDIA B300 chips. On September 30, 2026, it sold the entity holding them to Axe Compute. Axe repaid about $87.8 million of debt and pays Duos $42.9 million in 60 monthly installments of $715,000, due per the 8-K within twelve months at the latest or upon a financing. Duos keeps serving the existing GPU customer in Columbus with capacity leased from Axe.
Axe Compute (Nasdaq: AGPU) is the buyer of Duos's GPU entity, the debtor on a $42.9 million purchase price, the supplier of the leased compute capacity and the largest customer: the August 2026 hosting agreements for 55 megawatts are to bring more than $500 million of base payments over five years. Billing, however, starts only after completion and Axe's written acceptance.
Shares outstanding rose from 7.31 million (March 2024) to 31.47 million (August 18, 2026). As of June 30, 2026, there were also 3.8 million pre-funded warrants, about 5.1 million shares from preferred stock, 0.73 million warrants and about 0.2 million employee options — about 41 million potential shares in total. Equity raises in 2026: about $65 million at $7.50 in March and about $55 million at $9.50 in June.
Duos expects more than $50 million of revenue and positive adjusted EBITDA for 2026, confirmed on October 5, 2026. On the August 17, 2026, call, about $26 million of that was to come from the GPU business that has since been sold. For 2027, management gave an early framework of at least $160 million of revenue — including a full year of the since-sold GPU program. First-half 2026 revenue was $8.32 million.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.