Kontron: Roughly EUR 9 Million of VW Invoices in the Quarterly Result - Whether They Count, the CEO Leaves Open
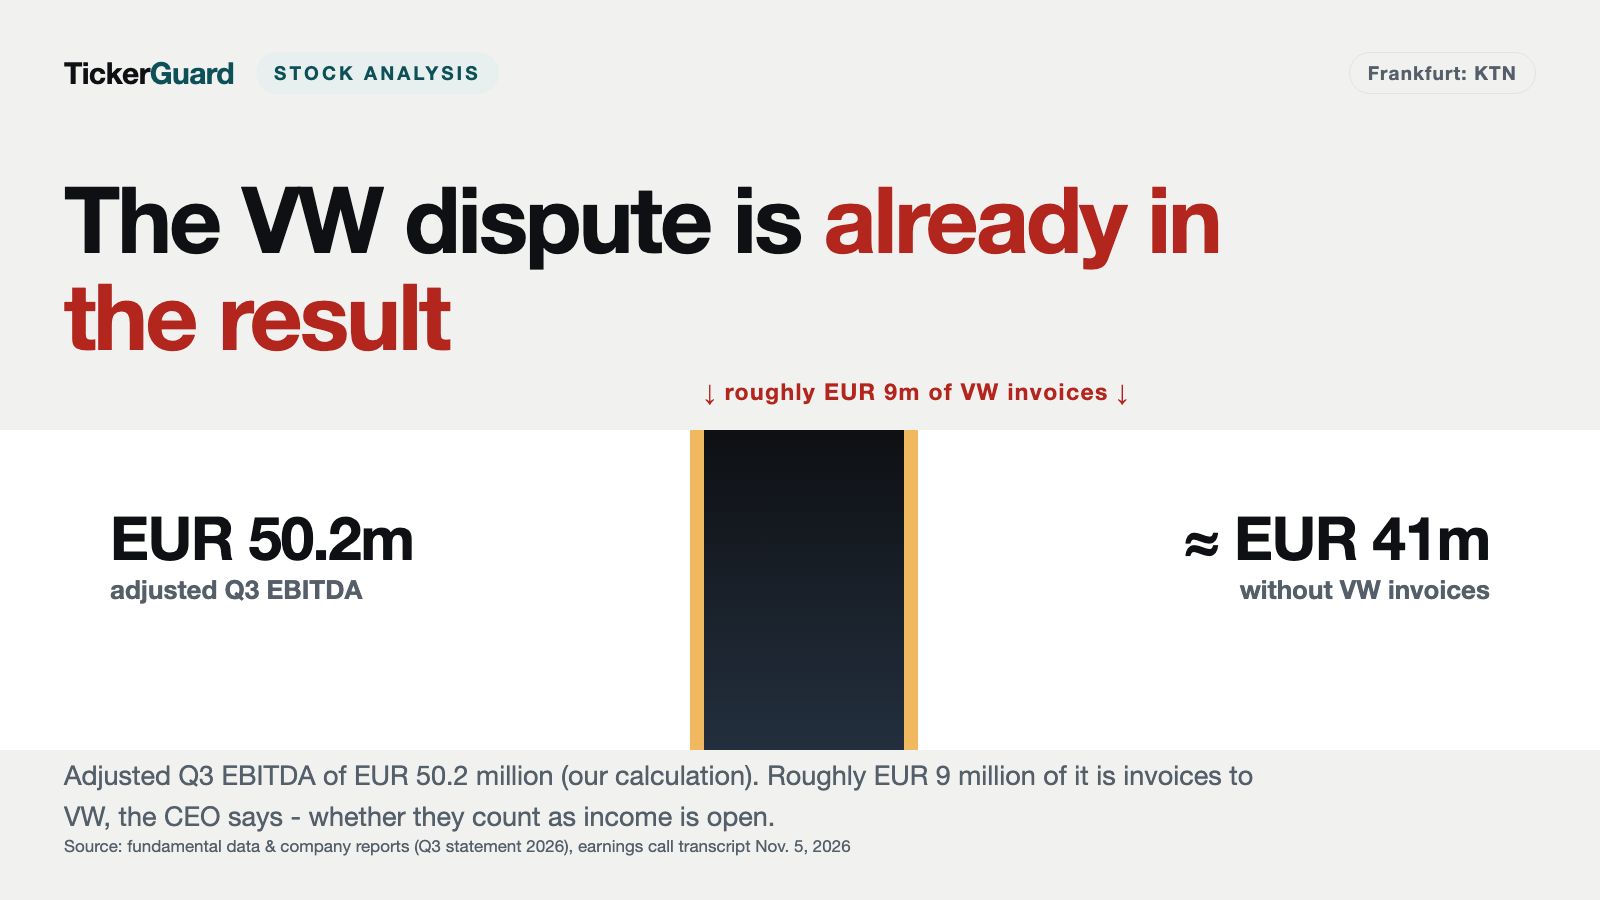
According to the CEO, Kontron has invoiced Volkswagen roughly EUR 9 million as costs and compensation and booked it as other income in the third quarter - in a dispute over wallboxes that VW, by Kontron's account, is not taking. Whether the income stands still has to be settled with the auditor. On the day of the numbers the stock fell 7.4 percent and the CEO bought 4,000 shares; the confirmed full-year target still needs roughly EUR 74 million of EBITDA in the final quarter.
 Thomas Mücke
Founder & Publisher
Chart
Interactive price chart (TradingView).
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
On November 5, 2026, on the earnings call, an analyst asked what was behind the unusually high other income - the income statement shows EUR 12.7 million for the third quarter, after EUR 0.2 million a year earlier. CEO Hannes Niederhauser answered, according to the transcript, that it contained invoices to Volkswagen, and added: "It's also not sure if this will qualify at the end for the income or not." He spoke of compensation invoices; the background is the dispute over wallboxes that, by Kontron's account, the VW Group is not taking despite a binding order. Asked again later, he put the invoices at roughly EUR 9 million. The same day the stock fell 7.4 percent on XETRA, and Niederhauser bought 4,000 shares at EUR 19.01, according to the mandatory disclosure - roughly EUR 76,000.
This is more than a bookkeeping question. It is a textbook case of an investor trap that springs precisely when a company is doing honest work: it rebuilds itself. It sells one division, buys another, redraws its segments and cuts jobs - all traceable, all justified. And because the house keeps running during the rebuild, the reports cheerfully keep comparing everything to "the prior year." Except that prior year no longer exists. Call it the rebuild trap: you diligently check the new number and miss that the bar it is measured against has quietly moved. In miniature it is already there in the November 5 scene: you see a quarterly result and miss that it contains money that is still being negotiated.
At Kontron AG this trap can be recalculated, and since November 5, 2026 in three places: a confirmed full-year target that, by the CEO's account, already contains the VW invoices; net debt that fell in the third quarter by less than a single one-off payment brought in; and prior-year figures that change from report to report.
One thing at a time. The 2026 half-year financial report of August 6, 2026 states adjusted EBITDA of EUR 90.9 million for the first half of 2025 on page 2. Two pages later the same report does its math with a different number, as shown further down. Since November 5, 2026 the quarterly statement as of September 30, 2026 has been on the table: it answers part of that question and moves the bar again somewhere else. So let us make a deal: we read the reports ourselves - the 2026 Q3 statement, the 2026 half-year financial report and the 2025 annual report - and for every percentage figure we check first what it is being measured against. That sets the tension of this analysis: Kontron reports a record order backlog - and the comparative figures change from report to report.
The Third Quarter of 2026: Debt Falls, Kontron Reports a Dispute With VW, and Everything Rides on the Final Quarter
On November 5, 2026 Kontron published its quarterly statement as of September 30, 2026 - it contains no audit opinion. The short version: in the first nine months of 2026, revenue fell 6.7 percent to EUR 1,102.9 million (prior-year period: EUR 1,181.9 million); adjusted for divestments and the COM deconsolidation, a decline of 1.8 percent remains (comparative: EUR 1,123.6 million). EBITDA came in at EUR 125.9 million after EUR 193.6 million, or EUR 151.0 million before EUR 25.1 million of restructuring costs - up 7.8 percent on an adjusted prior-year figure of EUR 140.1 million. Shareholders were left with EUR 52.7 million (prior-year period: EUR 110.8 million), or EUR 0.85 per share after EUR 1.80.
The third quarter on its own: EUR 365.8 million in revenue (third quarter of 2025: EUR 400.8 million), EUR 41.5 million of EBITDA (EUR 47.6 million) and EUR 17.9 million of profit attributable to shareholders (EUR 21.9 million). Strip out the quarter's restructuring costs - EUR 8.7 million, the difference between EUR 25.1 million after nine months and EUR 16.4 million after six - and by our calculation EBITDA is EUR 50.2 million (presentation: EUR 50 million), a margin of 13.7 percent. Less pleasing: by our calculation from the segment table, the quarter's gross margin was 40.4 percent (EUR 147.7 million on EUR 365.8 million), after 43.4 percent in the prior-year quarter and 42.2 percent in the first half of 2026. On the earnings call an analyst raised that decline, according to the transcript; CEO Hannes Niederhauser replied, per the transcript, that the margin is in the same range as last year - true over nine months at 41.6 percent, while for the quarter alone the segment table shows the gap described.
The good news is on the balance sheet. Cash rose from EUR 171.5 million at the half-year mark to EUR 246.1 million, the equity ratio from 41.7 percent to 43.4 percent, and on debt Kontron writes:
"Net debt, however, continued to go down and stood at just EUR 135.2 million at the end of Q3 2026 (December 31, 2025: EUR 147.1 million)."
- Kontron AG, Quarterly statement Q3 2026, section "Solid financial position," page 6
The word "continued" deserves a second look. Three months earlier, on June 30, 2026, net debt had still stood at EUR 253.1 million. The decline comes essentially from a single payment: in the third quarter of 2026 the outstanding payment from the sale of the COM business arrived, and on September 30, 2026 Kontron announced the receipt of a EUR 126 million payment; the cash flow statement in the quarterly statement shows a net inflow of EUR 120.9 million for the third quarter in the line for the sale of subsidiaries. The statement does not explain the difference. The math on that is further down, under Uncomfortable Truth No. 2. Operating cash flow was positive again in the third quarter at plus EUR 18.2 million (third quarter of 2025: EUR 33.5 million). After nine months that leaves plus EUR 4.3 million - against EUR 49.7 million in the prior-year period.
The supply chain, meanwhile, is jammed worse than in the summer. Products worth EUR 68.6 million could not be delivered as of September 30, 2026, after EUR 50.4 million at the half-year mark; the earnings call presentation puts the EBITDA delayed as a result at EUR 24 million. In turn, inventories rose from EUR 318.5 million at the turn of the year to EUR 400.3 million.
New in This Statement: A Dispute With Volkswagen
In this statement Kontron names a customer and accuses it of not taking the quantities it ordered. In the foreword, CEO Hannes Niederhauser writes:
"With the completion of the programme, there could be a need for devaluation in the valuation of intangible assets of up to EUR 25 million. This depreciation is not cash and does not affect EBITDA. This was triggered by settlement talks with the VW Group, which is not accepting the agreed quantities despite a binding order. As a further consequence, we have reduced the reported order backlog for VW in the amount of EUR 130 million. We expect an agreement on VW's damages payment before the end of 2026."
- Kontron AG, Quarterly statement Q3 2026, foreword, page 3
The product is wallboxes, meaning home charging stations for electric cars - the business of the GreenTec unit, whose restructuring Kontron says in its press release of November 5, 2026 it completed as planned in the third quarter; the foreword of the quarterly statement says the cost saving program was "largely completed". The earnings call presentation puts what Kontron describes as a binding order at EUR 250 million, of which only about 10 percent has been delivered so far; on the call Niederhauser spoke, according to the transcript, of EUR 260 million to EUR 270 million for close to 500,000 charging stations for VW subsidiary Elli. How the EUR 130 million taken out of the backlog relates to that total order, neither the statement nor the presentation explains. All of this is Kontron's account; we have no statement from Volkswagen on it. On the call itself Niederhauser was blunter, according to the transcript:
"Volkswagen will have to pay a compensation. I expect that to happen in Q4, but you never know."
- Hannes Niederhauser, CEO, Q3 2026 earnings call, November 5, 2026 (third-party transcript)
An analyst followed up on how much of that compensation is already included in EBITDA guidance. The answer is the sentence to remember from this chapter:
"We have already invoiced some costs to them, so this is included. That is probably 30%-40% of the total amount what we expect. The rest is not included."
- Hannes Niederhauser, CEO, Q3 2026 earnings call, November 5, 2026 (third-party transcript)
According to the transcript, Niederhauser expects compensation significantly exceeding EUR 20 million - when an analyst followed up, on top of the amounts already invoiced. And by his account the invoices already issued are not only in guidance but already in the third-quarter result. That is the scene from the top of this analysis, here in his words:
"We have invoices to Volkswagen in. It's also not sure if this will qualify at the end for the income or not. We have to discuss that for auditor. There is already compensation invoices to Volkswagen in, and that replaces the revenues, let's say, what we didn't do with Volkswagen, as well as the depreciation and damage what we had."
- Hannes Niederhauser, CEO, Q3 2026 earnings call, November 5, 2026 (third-party transcript)
He gave the order of magnitude only when the same analyst asked again later: "We invoiced probably in the range of nine" and "This were other income."
For you this means three things. First: the backlog of EUR 2,751.9 million, a record according to the presentation, is already net of VW orders totaling EUR 130 million. Second: a write-down of up to EUR 25 million would not hit EBITDA, but it would hit the bottom line - on a pre-tax basis and measured against the EUR 52.7 million of the first nine months, that would be nearly half. Third: by the CEO's account, third-quarter EBITDA and confirmed guidance already contain the invoices issued to VW - roughly EUR 9 million per the transcript, about 30 to 40 percent of the expected compensation - whose treatment is still open. Remember: when a full-year target depends on a negotiation, it is no longer a pure operating result.
What Else Has Been Settled Since August
The mandatory offer by Taiwanese shareholder Ennoconn has settled. Per the voting rights notification of August 24, 2026, Ennoconn has held 48.00 percent of voting rights since August 21, 2026 - just short of a majority. The share buyback program ended on September 30, 2026; in total Kontron repurchased 1,431,736 of its own shares for EUR 30.06 million. In its place comes a new dividend policy: the presentation accompanying the Q3 statement names a dividend proposal for fiscal 2026 expected at EUR 0.65 per share, with the note that Ennoconn asks for dividends rather than share buybacks. Nothing has been resolved; that is for the annual general meeting to decide. And since September 30, 2026 the Executive Board has included a chief technology officer, Dr.-Ing. Martin Rausch.
The market reacted clearly to the numbers: the XETRA close fell from EUR 20.42 to EUR 18.91 on November 5, 2026, a drop of 7.4 percent; the CEO bought at EUR 19.01 (see above). A good week later, on November 13, 2026, the close was back at exactly EUR 18.91. What the quarter means for the full-year target is worked through further down - under Uncomfortable Truth No. 4.
Company history for investors
-
2017
Ennoconn consolidates Kontron in full for the first time
Since July 1, 2017 the Taiwanese shareholder has carried the group on its own balance sheet on the basis of de facto control - without a voting majority; as of December 31, 2025 the stake was 27.90 percent.
-
2024
Revenue peak of EUR 1,684.8 million
The highest annual revenue in the 2022 to 2025 period covered here. Anyone reading only the 2025 EBITDA increase misses that revenue slipped 4.6 percent against this figure.
-
2025
COM business deconsolidated, profit jump reported
One-off effects of an implied EUR 32.4 million (141.1 - 108.7) lifted the result to EUR 141.1 million. Adjusted, EUR 108.7 million remained - making the comparative base for 2026 a matter of interpretation.
-
2026
GreenTec restructuring and a new segment structure
Two new segments have applied since January 1, 2026; in parallel, a planned 500 positions were being cut into the third quarter, which Kontron says is now complete (details in Uncomfortable Truth No. 4). For shareholders that means key prior-year figures (revenue, EBITDA, net result) have since also appeared in adjusted form in the reports.
-
2026
Ennoconn mandatory offer at EUR 23.50 per share
After the June 10, 2026 notice that the 30 percent threshold had been crossed, the offer was published on June 29, 2026; since settlement Ennoconn has held 48.00 percent per the voting rights notification (as of August 21, 2026) - and the offer price no longer anchors the share price.
-
2026
Q3 statement: COM payment cuts debt, VW dispute goes public
On November 5, 2026 Kontron reports net debt of EUR 135.2 million after EUR 253.1 million at the half-year mark, removes EUR 130 million of VW orders from its backlog and confirms guidance - for which roughly EUR 74 million of EBITDA is still missing in the final quarter.
What Kontron Actually Does - Computers for Places No PC Survives
Kontron AG, headquartered in Linz, is an Austrian company whose shares trade in Frankfurt. It builds what a consumer never sees: computers and communications equipment for environments where an ordinary office machine would give up within a week. Picture it this way - when the passenger display in a high-speed train runs, when data converges in an aircraft cockpit, or when a hundred machines in a factory report their readings, there is an industrial computer behind it that tolerates heat, vibration and continuous operation, and that still gets spare parts and security updates years after purchase. That promise is what Kontron sells.
Since January 1, 2026 the group has reported in two segments. Smart IoT bundles hardware, software and services around connected machines - industrial automation, 5G communications, medical technology, plus the ODM business (design and manufacturing on customer order) and group headquarters. Software + Solutions holds the higher-margin business: the proprietary KontronOS operating system, industrial software and the solutions businesses for rail, avionics and defense. In the first nine months of 2026, Smart IoT generated EUR 722.8 million in revenue (prior-year period: EUR 837.3 million) and Software + Solutions EUR 380.1 million (prior-year period: EUR 344.7 million). Gross margin shows the difference plainly: 36.9 percent in the first segment, 50.6 percent in the second.
Cutting across those, Kontron names three growth markets, and all three grew in the first nine months of 2026: Transportation (high-speed trains and public transit) with EUR 178.0 million in external revenue, up 4.8 percent; Aerospace and Defense with EUR 123.6 million, up 35.6 percent according to Kontron - Kontron states it supplies NATO states only; and Cyber Solutions with EUR 103.1 million, up 14.5 percent according to Kontron. As of September 30, 2026 the group employed 6,296 people on a full-time equivalent basis. As of June 30, 2026 it comprised 52 fully consolidated companies.
Why There Is No 10-K Here - and Where the Numbers Come From Instead
One note up front, because it shapes the entire evidence base: there is no SEC filing for Kontron. Kontron is an Austrian stock corporation listed in the regulated market (Prime Standard) of the Frankfurt Stock Exchange and included in the TecDAX and SDAX indices - not a U.S. reporting issuer, so there is no annual report on Form 10-K, no quarterly report on Form 10-Q and no EDGAR identifier. Only the annual accounts are audited: of the half-year report Kontron states in the document itself that the interim consolidated financial statements as of June 30, 2026 "have been subject to neither an audit nor an auditor's review," and the quarterly statement of November 5, 2026 contains no audit opinion. The figures in this analysis accordingly carry "Source: fundamental data & company reports (quarterly statement, half-year/annual report, Frankfurt Stock Exchange)".
Kontron shares that setup with many European industrial names, HENSOLDT among them (see our analysis). And because Kontron has repeatedly named missing chips as a brake in 2026, our Infineon analysis is worth a look alongside it - that is the other end of the same supply chain.
How This Stock Landed on Our Desk
Honestly: not through a fundamentals screen, but through a ranking of attention. As of the August 17, 2026 cut-off, Kontron ranked high among the most-discussed stocks in the wallstreet-online forum - the place where retail investors are talking loudest about a stock right now. That is an attention signal and explicitly not a buy argument.
In Kontron's case the occasion back then was fairly obvious: in August 2026 the mandatory offer by Taiwanese shareholder Ennoconn settled. For us such a list is only a topic radar. What counts are the original reports - and because a new one, the Q3 statement, has been available since November 5, 2026, we brought this analysis up to date on November 15, 2026.
The Numbers Over the Years - Given Their Due
First the genuinely impressive part. Kontron rebuilt itself over four years, and the result of that rebuild shows in its earnings power. Revenue rose from EUR 1,063.7 million in 2022 via EUR 1,225.9 million in 2023 to EUR 1,684.8 million in 2024, and stood at EUR 1,607.3 million in 2025. EBITDA - earnings before interest, taxes, depreciation and amortization, so roughly the operating performance before all financing and accounting effects - grew over the same period from EUR 109.5 million via EUR 126.0 million and EUR 191.8 million to EUR 237.4 million. Two footnotes belong here: according to the annual report, the 2022 figure is adjusted for special effects, and the EUR 237.4 million for 2025 includes one-off effects from the COM deconsolidation and the group realignment - adjusted, Kontron states EUR 220.5 million. The EBITDA margin climbed from 10.3 percent to 14.8 percent, or 13.7 percent using the adjusted figure. That is the real achievement: revenue rose by about half, and earnings roughly doubled even on an adjusted basis.

The order book grew steadily too: backlog rose from EUR 1,686.2 million at the end of 2023 via EUR 2,077.9 million (end of 2024) and EUR 2,495.3 million (end of 2025) to EUR 2,750.5 million as of June 30, 2026 and EUR 2,751.9 million as of September 30, 2026 - a record according to Kontron, even though VW orders totaling EUR 130 million were taken out. Equity grew from EUR 604.0 million (2023) via EUR 652.3 million (2024) to EUR 746.1 million (2025) and stood at EUR 777.1 million as of September 30, 2026; an equity ratio of 43.4 percent is comfortable for a technology company. And in 2025 Kontron earned EUR 141.1 million for its shareholders, after EUR 90.7 million the year before - earnings per share of EUR 2.29.
Except that this handsome figure is the first example of our rebuild trap. Of the EUR 141.1 million, EUR 32.4 million came from one-off effects of the COM deconsolidation and the group realignment. Kontron discloses this itself and gives the adjusted figure: EUR 108.7 million. So the EUR 2.29 per share is not wrong - just short of a quarter of it did not come from ongoing operations.
What the Reports Say - The Uncomfortable Truths
Uncomfortable Truth No. 1: The Half-Year Report Gives Two Different Prior-Year Values for the Same Metric
Here it becomes concretely checkable. The key figures table on page 2 of the 2026 half-year financial report states adjusted EBITDA of EUR 90.9 million for the first six months of 2025. Page 4 then carries this sentence:
"EBITDA fell by 13.9% to EUR 84.4 million (6M 2025: EUR 90.9 million adjusted; unadjusted, EBITDA stood at EUR 146.0 million). Restructuring expenses totaled EUR 14.4 million in the first half of 2026. Taking these restructuring expenses into account, EBITDA amounted to EUR 101.4 million."
- Kontron AG, Half-year report 2026, group interim management report, page 4 (English version); the authoritative German version states EUR 16.4 million and EUR 100.8 million at the same spot

Let us do the math. From EUR 90.9 million to EUR 84.4 million is minus 7.2 percent, not minus 13.9. From EUR 90.9 million to EUR 100.8 million is plus 10.9 percent, not plus 2.8. Both percentages only work if the prior-year base is taken to be roughly EUR 98.0 million: 98.0 less 13.9 percent gives 84.4, and 98.0 plus 2.8 percent gives 100.7 - the report's 100.8, give or take rounding. That EUR 98.0 million appears nowhere in the report. The management report is internally consistent - it simply calculates against a different comparative than the company's own key figures table two pages earlier.
And there is a language layer: the English version quoted above says EUR 14.4 million instead of EUR 16.4 million of restructuring expenses - the German version prevails according to the imprint, and only it adds up (84.4 plus 16.4 equals 100.8).
What does that mean for you? Nothing on the balance sheet is wrong because of it, and nobody hid anything - the unadjusted figure sits in the same sentence. But it does mean this: at Kontron you cannot take a percentage figure from the management report at face value, because the base behind it shifts within the same document. Remember: when you find two numbers for the same prior year, the problem is not the number - it is knowing which one is embedded in the next guidance.
What the Q3 statement of November 5, 2026 says about it. In August we said we would check which comparative base Kontron uses in its next statement. The result has three parts. First: at nine-month level the math is unambiguous this time. The key figures table states adjusted EBITDA of EUR 140.1 million for the first nine months of 2025, and the text an increase of 7.8 percent "on a like-for-like basis" - and from EUR 140.1 million to EUR 151.0 million is exactly 7.8 percent. Second: the language question is settled. Both versions of the Q3 statement give EUR 25.1 million of restructuring costs after nine months, and that fits the adjusted quarterly EBITDA of around EUR 50 million from the presentation only with the EUR 16.4 million of the German half-year version (41.5 plus 25.1 minus 16.4 equals 50.2).
Third - and this is the uncomfortable part: the half-year base itself is not resolved; it has acquired a third value. Take the adjusted nine-month figure for 2025 (EUR 140.1 million) and subtract third-quarter 2025 EBITDA (EUR 47.6 million, which the Q3 presentation also uses as the comparative for adjusted quarterly EBITDA in 2026), and what remains for the first half of 2025 is an implied EUR 92.5 million - neither the EUR 90.9 million from the half-year key figures table nor the roughly EUR 98.0 million behind its percentages. And a year ago, in the Q3 statement 2025 (German version), Kontron had still put operating EBITDA for those same nine months of 2025 at roughly EUR 147.6 million; today it is EUR 140.1 million. None of these shifts is explained. So the rebuild trap has not snapped shut and gone away - it travels along from report to report.
Uncomfortable Truth No. 2: Revenue Falls, Inventory Grows - and Debt Fell Thanks to a One-Off Payment
The record order backlog Kontron reports is in the headline. The other set of numbers sits three chapters further back - first in the half-year report, then in the Q3 statement. Revenue in the first half of 2026 fell 5.6 percent to EUR 737.1 million. Kontron explains this credibly: the COM business, which still contributed EUR 38.9 million in the prior-year half, has been deconsolidated; stripping it and the divested IT service units out, revenue actually rose slightly (EUR 737.1 million against EUR 729.0 million adjusted). Then came the chip shortage: missing components left Kontron unable to deliver products worth EUR 50.4 million - the report calls this the "delinquent backlog," which stood at zero in the prior-year period.
On cash it gets less comfortable. Operating cash flow - the money the ongoing business actually brings in, not the accounting profit - came in at minus EUR 13.8 million in the first half of 2026, after plus EUR 16.3 million a year earlier. By June 30, 2026 cash had fallen from EUR 263.5 million to EUR 171.5 million. And net debt, meaning financing liabilities less cash, rose sharply in the first half:
"As of June 30, 2026, the Kontron Group reported net debt of EUR 253.1 million (December 31, 2025: net debt EUR 147.1 million | March 31, 2026 net debt EUR 190.5 million). This increase is chiefly due to cash outflows for investments, increased inventories, and share buybacks."
- Kontron AG, Half-year report 2026, section "Solid asset position," page 6


Part of the first-half increase was explicable and deliberate. Inventories rose 14.9 percent to EUR 366.1 million by June 30, 2026 - during a chip shortage a manufacturer stocks up on purpose. And Kontron spent EUR 30.1 million on its own shares in the first half of 2026; treasury stock rose from 1,109,815 to 2,519,051 shares as of June 30, 2026, or 3.94 percent of share capital. That is a return of capital to shareholders, not a failure - but it is money that left the till.
Kontron had announced that net debt would fall in the second half of 2026 - and it delivered: EUR 135.2 million as of September 30, 2026, with EUR 246.1 million of cash. The how is worth a look, though. The EUR 117.9 million decline since the half-year mark is smaller than the EUR 120.9 million that, per the cash flow statement, came in from the COM sale in the third quarter. (The company announcement of September 30, 2026 says EUR 126 million; Kontron does not explain the difference of roughly EUR 5 million - we use the smaller figure from the cash flow statement.) Without that one-off payment, net debt would not have fallen in the third quarter - it would have edged up. Ongoing operations brought in EUR 18.2 million in the quarter, while inventories grew by roughly another EUR 34 million to EUR 400.3 million - up 25.7 percent since the turn of the year.
For the fourth quarter, CFO Clemens Billek set the bar himself on the earnings call:
"We expect a significant cash in on the operating side, significant operating cash flow of around EUR 100 million in Q4 alone, in line with the last years, where always Q4 was by far the strongest quarter in terms of operating cash flow."
- Clemens Billek, CFO, Q3 2026 earnings call, November 5, 2026 (transcript)
By his account net debt is to come in at around EUR 100 million or below at year-end. That is a clear, checkable statement: after nine months the books show EUR 4.3 million of operating cash flow - the 2026 annual accounts will show whether the final quarter delivers more than twenty times that.
Uncomfortable Truth No. 3: On Paper, Kontron Has Belonged to Ennoconn's Scope of Consolidation Since 2017 - and Thus to the Foxconn Orbit
Anyone who regards Kontron as an independent German-Austrian technology company should read the notes to the accounts. In accounting terms that has not been true for nine years. The notes to the 2025 annual report state:
"The business relationships with the parent company or its controlling company refer to Ennoconn Corporation, Taiwan, which holds a 27.90% stake in Kontron AG as of December 31, 2025 and in whose scope of consolidation the Kontron Group has been included on the basis of de facto control since July 1, 2017, and Hon Hai Precision Industry Co, Ltd, the largest single shareholder of Ennoconn Corporation with a 25.19% stake."
- Kontron AG, Annual report 2025, notes to the consolidated financial statements no. 10, page 195

In plain terms: Ennoconn has been consolidating Kontron fully into its own group accounts since 2017 because it effectively controls the company - even without a voting majority. That is possible when a shareholder regularly commands a majority of the votes present at annual general meetings; at the annual general meeting of June 11, 2025, according to the 2025 annual report (German version, page 65), around 41 percent of subscribed capital was represented. Ennoconn in turn is a quarter owned by Hon Hai Precision Industry Co., Ltd., better known as Foxconn. The supervisory board spells it out in its own self-assessment:
"According to the assessment of the Supervisory Board, its composition as of December 31, 2025 meets the membership targets set out above with the exception of the independence of the three members with business relationships with Ennoconn Corporation, contrary to Principle 12, Recommendation C.7. Ennoconn Corporation is to be regarded as the controlling shareholder."
- Kontron AG, Annual report 2025, corporate governance report, page 44

Since June 2026 that proximity has been formal as well: on June 10, 2026 Ennoconn informed Kontron that it had crossed the 30 percent threshold, and it had to make the remaining shareholders a mandatory offer at EUR 23.50 per share. After the acceptance period ended on July 27, 2026, mandatory disclosures initially reported 12,468,867 tendered shares, about 19.5 percent of share capital; after withdrawals covering 229,365 shares (disclosure of August 14, 2026) and a further 1,000 shares (disclosure of August 21, 2026), the final figure was 12,238,502 shares, about 19.2 percent. On August 10, 2026 Kontron announced that all offer conditions had been met and that German foreign investment control had given its blessing. After settlement, per the voting rights notification of August 24, 2026, Ennoconn has held 48.00 percent of voting rights since August 21, 2026 - 30,654,099 of 63,860,568 shares. Ennoconn therefore does not command a voting majority. According to Kontron no further increase is planned: that is what the company announcement of August 10, 2026 says, and on the November 5, 2026 earnings call Kontron CFO Billek said, per the transcript, that Ennoconn does not want to go above 50 percent. We have no statement of Ennoconn's own on this.
This is not a disaster headline - it is a fact with two sides. On one side Kontron is, according to management, to gain access to Foxconn's manufacturing capacity and to customers in Asia; CEO Hannes Niederhauser writes in the half-year report foreword of EUR 40 million in expected annual synergies and frames the ambition as follows: "With the support of Foxconn, we can jointly win blue-chip customers with a volume of over EUR 1 billion." The presentation accompanying the Q3 statement turns that into a stepped plan: the contribution to Kontron's EBIT is put at EUR 14 million in 2027, EUR 28 million in 2028 and EUR 36 million in 2029 - so the EUR 40 million is a target for later years, not a figure for 2027. In the foreword to the Q3 statement management rolls synergies and GreenTec savings into an expected additional earnings increase of EUR 70 million per year "in the coming years"; it gives no date for that. On the other side, a growing share of the future rests on a shareholder whose home base Kontron itself flags as a geopolitical flashpoint in its own risk section - "tensions in Asia (China vs. Taiwan - Taiwan, for example, is home to Ennoconn, Kontron's largest shareholder)."
Uncomfortable Truth No. 4: The Full-Year Target Now Rides on a Single Quarter
Kontron confirmed its 2026 guidance again on November 5, 2026: revenue at prior-year level of around EUR 1.6 billion, and EBITDA of EUR 200 million or EUR 225 million before restructuring charges. In August, after six months, we showed here that the second half would have to deliver roughly EUR 115.6 million unadjusted and roughly EUR 124.2 million adjusted. The third quarter contributed EUR 41.5 million and EUR 50.2 million of that respectively. That leaves roughly EUR 74 million of EBITDA for the fourth quarter - on either reading, because at EUR 25.1 million the restructuring costs have already reached the planned envelope of around EUR 25 million. On revenue, roughly EUR 497 million is still missing to reach the EUR 1.6 billion mark.
That is not impossible, and management gives reasons. Restructuring is complete according to the EQS news and the presentation of November 5, 2026 (the foreword to the quarterly statement says "largely completed"): headcount is down by 400 since the turn of the year to 6,296 full-time equivalents as of September 30, 2026; per the CEO (transcript), 44 further departures are contractually agreed. The presentation and the CFO speak of 444 of the 500 planned positions; the presentation builds that number from both (6,696 to 6,296, plus 44 departures). Per the foreword, personnel costs fell from EUR 113 million in the second quarter to EUR 108 million in the third. The EUR 68.6 million of delinquent orders is, according to the company, to be shipped mostly in the fourth quarter. And the presentation shows that the EUR 511 million of backlog scheduled for 2026 plus nine-month revenue adds up to EUR 1,614 million.
But the math has three catches. First, the order of magnitude: EUR 74 million would be 47 percent more than the adjusted EUR 50.2 million of the third quarter, and revenue would have to jump from EUR 365.8 million to roughly EUR 497 million - in the final quarter of 2025 it was EUR 425.4 million. Second, the bar, and here it moves again: Kontron reported EBITDA of EUR 43.8 million for the fourth quarter of 2025 (EUR 237.4 million for the year less EUR 193.6 million after nine months). But the 2025 annual report also gives adjusted EBITDA of EUR 220.5 million for the full year; subtract the EUR 140.1 million the Q3 statement now carries as the adjusted nine-month figure, and the same quarter comes out at an implied EUR 80.4 million. Measured against one number, the fourth-quarter 2026 target would be a jump of 69 percent; measured against the other, a decline of 8 percent. One caveat belongs here: Kontron states the EUR 80.4 million nowhere itself, it is our difference between two reports - and the reports do not say whether both adjusted figures rest on the same adjustments. So the two readings are not equivalent; only the EUR 43.8 million is reported. Third, Volkswagen: by the CEO's account, the roughly EUR 9 million of VW invoices from the chapter above sit in the third quarter and in guidance, although their recognition as income is open. Without them, adjusted quarterly EBITDA would by our rough calculation be around EUR 41 million rather than EUR 50.2 million, and the distance to EUR 74 million correspondingly larger.
So more than ever: guidance confirmed after nine months is not a result, it is a promise about a single quarter. And how big that promise is depends on which prior-year figure you put next to it - which brings us back to the rebuild trap.
Valuation: Low Multiples - Depending on Which Year You Pick
The usual valuation metrics come out low for Kontron - and the share price is below where it stood at the first edition of this analysis. On November 13, 2026 the shares closed at EUR 18.91 on XETRA, 14.9 percent below the August 14, 2026 close (EUR 22.22). Across 63,860,568 shares that gives a market capitalization of roughly EUR 1,208 million, treasury shares included. How many treasury shares Kontron currently holds is not stated in the Q3 statement: as of June 30, 2026 it was 2,519,051 shares, and in the third quarter their carrying amount on the balance sheet fell from EUR 52.0 million to EUR 38.4 million. Per the cash flow statement nothing more was repurchased in the third quarter; the same statement shows EUR 9.6 million of inflows from the settlement of stock options. What the treasury shares were used for is not explained in the statement. Measured against 2025 revenue of EUR 1,607.3 million, the market value corresponds to a price-to-sales ratio of about 0.75 - the market pays three quarters of one year's revenue.
On the price-to-earnings ratio, the choice of number matters again. On reported 2025 earnings per share of EUR 2.29 the multiple is about 8. Using the adjusted result of EUR 108.7 million, or roughly EUR 1.76 per share (EUR 108.7 million divided by 61.685 million average shares outstanding), it is about 11. Both are low values for a technology company with a gross margin of around 42 percent - but the gap between the two is just under a third.
Enterprise value is more informative: market capitalization (roughly EUR 1,208 million) plus net debt (EUR 135.2 million as of September 30, 2026) gives roughly EUR 1,343 million. Against 2025 EBITDA of EUR 237.4 million that is about 5.7 times; against the company's own adjusted 2026 guidance (EUR 225 million) about 6.0 times, and against the unadjusted figure (EUR 200 million) about 6.7 times. For context on what professional observers thought before the quarterly numbers arrived: the presentation accompanying the Q3 statement lists ten analyst firms as of September 18, 2026 - nine at "Buy," one at "Hold," with an average price target of EUR 29.69. Average means all ten targets added up and divided by ten, so a single very high or very low target moves it noticeably. That is a snapshot compiled by the company, not a current consensus and not a statement from us.
One valuation anchor from the summer is now history: the mandatory offer price of EUR 23.50 per share. The November 13, 2026 close sits 19.5 percent below it. What is new is the prospect of a dividend. There was none for 2025 - the annual general meeting of June 30, 2026 resolved to carry the full retained profit of EUR 147,330,587.59 forward. For 2026 Kontron signals a proposal expected at EUR 0.65 per share; at the November 13, 2026 price that would be roughly 3.4 percent. None of it has been resolved.
Opportunities and Risks at a Glance
What speaks for Kontron:
- Order backlog of EUR 2,751.9 million as of September 30, 2026, which Kontron calls a record - more than 1.7 times 2025 revenue and up 10.3 percent from the turn of the year (EUR 2,495.3 million), even though EUR 130 million of VW orders were taken out.
- All three growth markets expanded in the first nine months of 2026: Aerospace and Defense up 35.6 percent to EUR 123.6 million in revenue (EBITDA EUR 23.3 million after EUR 17.6 million), Cyber Solutions up 14.5 percent to EUR 103.1 million, Transportation up 4.8 percent to EUR 178.0 million.
- The higher-margin Software + Solutions segment grew nine-month revenue by 10.3 percent (EUR 380.1 million after EUR 344.7 million) and EBITDA as well (EUR 67.7 million after EUR 63.7 million). Group EBITDA before restructuring costs rose to EUR 151.0 million (adjusted prior-year figure: EUR 140.1 million).
- The balance sheet carries: EUR 777.1 million in equity against total assets of EUR 1,791.0 million, an equity ratio of 43.4 percent, EUR 246.1 million in cash, and nine-month EBIT of EUR 70.6 million against EUR 19.4 million in finance expenses - interest covered more than three times over. At EUR 135.2 million, net debt is below its level at the turn of the year.
- Restructuring is complete according to the company: headcount is down by 400 full-time equivalents since the turn of the year, costs stayed within the planned envelope at EUR 25.1 million, and Kontron puts annual savings at more than EUR 30 million from 2027. For fiscal 2026 a dividend proposal has been signaled (expected at EUR 0.65 per share).
What speaks against it:
- Ongoing operations brought in very little cash: EUR 4.3 million of operating cash flow after nine months (prior-year period: EUR 49.7 million). The third-quarter drop in net debt came from the one-off COM payment (uncomfortable truth no. 2).
- The full-year target rides on one quarter - and partly on Volkswagen: on invoices whose recognition as income is open, and on a write-down of up to EUR 25 million that Kontron says is possible (uncomfortable truth no. 4).
- The comparative base remains movable: there are now three values for the same adjusted first-half 2025 EBITDA (uncomfortable truth no. 1).
- The supply chain is jammed worse than in the summer: EUR 68.6 million of overdue orders as of September 30, 2026 (June 30, 2026: EUR 50.4 million), inventories up 25.7 percent since the turn of the year, and by our calculation third-quarter gross margin was three percentage points below the prior-year quarter.
- Ownership is unusually concentrated: Ennoconn has held 48.00 percent since August 21, 2026 per the voting rights notification, has consolidated Kontron fully since July 1, 2017, had three non-independent supervisory board members attributed to it as of December 31, 2025 and is called a "controlling shareholder" in the annual report itself. The group simultaneously buys manufacturing services from Ennoconn and Hon Hai - worth EUR 27.9 million in 2025.
- There was no dividend for 2025, and the proposal for 2026 has been signaled, not resolved. On top of that comes potential dilution from two stock option programs with a combined 2,532,500 outstanding or not-yet-allocated option rights (as of June 30, 2026) - roughly 4 percent of share capital.
A Human Conclusion
Back to the rebuild trap. Kontron really did rebuild itself in recent years, and the rebuild worked: a broadly diversified group with a 10.3 percent EBITDA margin (2022) became a focused supplier at 14.8 percent (2025) - after nine months of 2026 it is 13.7 percent before restructuring costs and 11.4 percent including them - with an order book covering more than a year and a half of revenue and three growth markets that are all expanding, two of them at double-digit rates. That is no small thing, and it belongs in the headlines.
Read on, and the same reports carry the second set of numbers: operating cash flow of EUR 4.3 million after nine months, net debt that fell only thanks to a one-off payment, EUR 68.6 million of orders that could not be shipped for want of components, a dispute with Volkswagen - and a full-year target riding on a single quarter. Plus a large shareholder from Taiwan who has held just under half the voting rights since August 21, 2026 and who has been carrying Kontron on its own group balance sheet since 2017 anyway.
None of this refutes the growth story. But both sets of numbers sit in the same documents, and only one of them makes the headline. If you take a single sentence away from this analysis, make it this one: for every percentage figure, check first what it is being measured against. At Kontron, the half-year report offered two answers, and the Q3 statement has put a third next to them. For the 2026 annual report that means, very concretely: check whether the roughly EUR 9 million of VW invoices stayed in income, whether the write-down of up to EUR 25 million was booked - and which fourth quarter of 2025 Kontron measures its final quarter against. What you make of that is your decision. And that is exactly as it should be.
Sources
Every original document used in this analysis, for you to read yourself:
- Kontron AG - Quarterly statement Q3 2026 as of September 30, 2026 (published November 5, 2026) - latest period report, unaudited; source of all nine-month and quarterly figures and of the foreword on the VW dispute
- Kontron AG - Quartalsmitteilung Q3 2026 (German version of the same statement) - used for the language-version comparison on restructuring costs
- Kontron AG - Presentation for the November 5, 2026 earnings call - delinquent backlog, dividend policy, stepped plan for the Ennoconn synergies, VW order, analyst overview
- Kontron AG Q3 2026 earnings call of November 5, 2026 - transcript at stockanalysis.com (third-party transcript; quotes from Hannes Niederhauser and Clemens Billek)
- Kontron AG - EQS news of November 5, 2026: figures for the first nine months of 2026, forecast confirmed
- Kontron AG - EQS news of September 30, 2026: EUR 126 million cash inflow from the COM sale and a new chief technology officer
- Kontron AG - Voting rights notification of August 24, 2026: Ennoconn has held 48.00 percent since August 21, 2026
- Kontron AG - Completion notice of October 5, 2026 for share buyback program I 2026 and managers' transactions disclosure of November 5, 2026 on the CEO's share purchase
- Kontron AG - Q3 statement 2025 (German version) - the operating EBITDA figure given back then for the first nine months of 2025
- Kontron AG - Half-year financial report 2026 as of June 30, 2026 (published August 6, 2026), authoritative German version - source of all half-year figures
- Kontron AG - Half-year report 2026 (English version of the same report) - used for the language-version comparison on restructuring expenses
- Kontron AG - Annual report 2025 (audited IFRS consolidated financial statements), English version - multi-year comparison, chapter "The Kontron share," corporate governance report, notes no. 10
- Kontron AG - Annual report 2025, authoritative German version - source of the highlighted excerpts on pages 44 and 195
- Kontron AG - Q1 statement 2026 as of March 31, 2026 - GreenTec restructuring plan, solar revenue series, KontronOS and Kontron AIShield
- Kontron AG - EQS news of August 10, 2026: all conditions of the Ennoconn mandatory tender offer met, settlement announced for August 20, 2026
- Kontron AG - EQS managers' transactions disclosure of August 14, 2026: withdrawal for 229,365 of the initially 12,468,867 tendered shares and EQS managers' transactions disclosure of August 21, 2026: withdrawal for a further 1,000 shares, a final 12,238,502 tendered shares
- Investor relations pages at kontron.com/en/group/investors - financial reports, financial calendar, mandatory disclosures
- Fundamental data (price, 52-week range; data as of November 13, 2026), reconciled with the annual report, the half-year report and the Q3 statement.
- Hook: ranking of the most-discussed stocks in the wallstreet-online forum, cut-off August 17, 2026 - used as an attention signal, not as a source for company figures.
Transparency & disclaimer: This analysis is journalistic commentary on publicly available information. It is not investment advice, not a financial analysis in the regulatory sense, and not a solicitation to buy or sell securities. Equity investments carry substantial risk up to and including total loss. All information without warranty; the date of each figure is noted in the text, and the overall cut-off for this edition is November 15, 2026 (first edition: August 17, 2026). The next period report is the 2026 annual report; the financial calendar in the Q3 statement did not yet give a date for it. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this deep dive.
Our Bottom Line at a Glance
- Order book and growth markets positive
- The order backlog stood at EUR 2,751.9 million as of September 30, 2026, after EUR 2,495.3 million at the turn of the year and EUR 2,077.9 million a year before that - even though EUR 130 million of VW orders were taken out. All three stated growth markets expanded in the first nine months of 2026: Aerospace and Defense up 35.6 percent, Cyber Solutions up 14.5 percent, Transportation up 4.8 percent.
- Earnings quality neutral
- EBITDA before restructuring costs rose to EUR 151.0 million in the first nine months of 2026 (adjusted prior-year figure: EUR 140.1 million); the higher-margin Software + Solutions segment grew revenue by 10.3 percent and EBITDA from EUR 63.7 million to EUR 67.7 million. Gross margin after nine months was 41.6 percent, on a par with the prior year; in the third quarter it was 40.4 percent by our calculation, after 43.4 percent in the prior-year quarter.
- Cash flow and debt neutral
- Net debt fell from EUR 253.1 million (June 30, 2026) to EUR 135.2 million (September 30, 2026), and cash rose from EUR 171.5 million (June 30, 2026) to EUR 246.1 million. What carried it was the EUR 120.9 million net inflow from the COM sale; operating cash flow was plus EUR 18.2 million in the third quarter and EUR 4.3 million after nine months (prior-year period: EUR 49.7 million). Inventories rose to EUR 400.3 million.
- Traceability of the reporting negative
- The Q3 statement is consistent at nine-month level (adjusted 9M 2025 EBITDA of EUR 140.1 million, up 7.8 percent to EUR 151.0 million; the presentation from the same day says plus 7.5 percent) and confirms the restructuring costs of the German half-year version. But that leaves three values for the first half of 2025: EUR 90.9 million (half-year key figures table), roughly EUR 98.0 million (its percentages) and an implied EUR 92.5 million (from the Q3 statement). Kontron has not explained this.
- Guidance quality neutral
- Guidance for 2026 was confirmed on November 5, 2026: revenue of around EUR 1.6 billion, EBITDA of EUR 200 million or EUR 225 million before restructuring. After nine months EUR 125.9 million and EUR 151.0 million are on the books - so the fourth quarter would have to deliver roughly EUR 74 million, 47 percent more than the implied adjusted EUR 50.2 million of the third quarter. By the CEO's account per the transcript, guidance also contains the invoices already issued to VW (roughly EUR 9 million, about 30 to 40 percent of the expected compensation).
- Ownership and balance sheet neutral
- The balance sheet is solid: EUR 777.1 million in equity, a 43.4 percent equity ratio, nine-month EBIT of EUR 70.6 million against EUR 19.4 million in finance expenses. Ownership is unusual: Ennoconn has held 48.00 percent since August 21, 2026 per the voting rights notification, has consolidated Kontron fully since July 1, 2017, had three non-independent supervisory board members attributed to it as of December 31, 2025 and is a supplier at the same time.
After nine months of 2026 Kontron shows an order backlog of EUR 2,751.9 million that it calls a record, EBITDA before restructuring costs up to EUR 151.0 million and net debt down to EUR 135.2 million - which, however, arithmetically rests on the EUR 120.9 million net inflow from the COM sale, while operating cash flow stands at EUR 4.3 million. Roughly EUR 74 million of EBITDA is still missing in the final quarter for the confirmed full-year target, a dispute with Volkswagen is open, and largest shareholder Ennoconn has held 48.00 percent of voting rights since August 21, 2026. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
Yellow here is not about an existential question - the balance sheet as of September 30, 2026 carries, with a 43.4 percent equity ratio and an order backlog Kontron calls a record. Yellow stands because three operating questions are open: net debt fell, arithmetically, only thanks to a one-off payment from the COM sale, the full-year target still needs roughly EUR 74 million of EBITDA in the final quarter with the dispute with Volkswagen unresolved, and the reports now yield three different values for the same prior-year EBITDA. The next checkable milestone is the 2026 annual report. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- The latest period report evaluated is the quarterly statement Q3 2026 as of September 30, 2026, published on November 5, 2026 (unaudited). All EQS disclosures from August 17 through November 15, 2026 were reviewed and incorporated where they change the picture: the managers' transactions disclosure of August 21, 2026 (a final 12,238,502 tendered shares), the voting rights notification of August 24, 2026 (Ennoconn 48.00 percent), the EQS news of September 30, 2026 (EUR 126 million cash inflow, new chief technology officer), the buyback completion notice of October 5, 2026 and the EQS news of November 5, 2026. The next period report is the 2026 annual report.
- The statements from the November 5, 2026 earnings call come from a third-party transcript (stockanalysis.com), not from a company document; the speakers (Hannes Niederhauser, Clemens Billek) are identified by name there. The expected compensation in the VW dispute (significantly more than EUR 20 million, per the transcript on top of the roughly EUR 9 million already invoiced) and the portion included in guidance are statements by the CEO, not audited figures. The information on the binding order and on VW not taking delivery is likewise Kontron's account; we have no statement from Volkswagen on it.
- The contradictions in the prior-year base are our own calculations: the key figures table of the 2026 half-year financial report states adjusted EBITDA of EUR 90.9 million for 6M 2025, while the percentages in the interim management report (minus 13.9 percent to EUR 84.4 million, plus 2.8 percent to EUR 100.8 million) only add up against roughly EUR 98.0 million. The Q3 statement 2026 implies EUR 92.5 million (EUR 140.1 million adjusted after nine months less EUR 47.6 million in the third quarter of 2025). Also our own calculations: adjusted quarterly EBITDA of EUR 50.2 million, the quarterly gross margin of 40.4 percent, and the comparatives for the fourth quarter of 2025 (reported EUR 43.8 million, implied adjusted EUR 80.4 million).
- The price anchor and all valuation metrics refer to the XETRA closing price of EUR 18.91 on November 13, 2026. Market capitalization of roughly EUR 1,208 million follows from 63,860,568 no-par shares including treasury shares; their number as of September 30, 2026 is not stated in the Q3 statement (June 30, 2026: 2,519,051 shares).
- The hook for this analysis is the ranking of most-discussed stocks in the wallstreet-online forum with an August 17, 2026 cut-off - an attention signal, not a source for company figures and not a buy argument. All figures come from Kontron AG's own reports.
- Note on identifiers: the ticker KTN.DE used here is shorthand for "Kontron, listed in Germany" and not an official exchange code. The shares are listed in the Prime Standard of the Frankfurt Stock Exchange and trade on XETRA, among other venues. On the company's history, CEO Hannes Niederhauser writes in the foreword to the 2026 half-year report that in 2016 the takeover of "the listed Kontron AG" by "our company at the time, S&T AG" was on the table, and that Ennoconn instead became the largest shareholder of "today's Kontron AG" that year - so the present issuer is the former S&T AG, not the company acquired back then.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace.
Frequently Asked Questions
Kontron, headquartered in Linz, Austria, builds industrial computers, embedded computing platforms, communications equipment and security software for environments where ordinary computers fail: trains, aircraft, factories, medical devices. It reports in two segments, Smart IoT and Software + Solutions, and employed 6,296 people on a full-time equivalent basis as of September 30, 2026.
Revenue fell 6.7 percent to EUR 1,102.9 million in the first nine months of 2026, or 1.8 percent adjusted for divestments and the COM deconsolidation. EBITDA came in at EUR 125.9 million, or EUR 151.0 million before EUR 25.1 million of restructuring costs. The order backlog stood at EUR 2,751.9 million as of September 30, 2026, and operating cash flow at EUR 4.3 million after EUR 49.7 million in the prior-year period.
The 2026 half-year report states adjusted EBITDA of EUR 90.9 million for the first half of 2025, but its percentages only add up against roughly EUR 98.0 million. The Q3 statement of November 5, 2026 is consistent at nine-month level (EUR 140.1 million, up 7.8 percent to EUR 151.0 million). Subtract the third quarter of 2025 (EUR 47.6 million) and the half-year comes out at an implied EUR 92.5 million - a third value. Kontron has not explained the differences.
Per the Q3 statement of November 5, 2026, the VW Group is not taking the agreed quantities despite a binding order; according to the CEO on the earnings call, the product is home charging stations (wallboxes) for VW subsidiary Elli. Kontron has therefore removed EUR 130 million from its order backlog and flags a possible write-down of up to EUR 25 million on intangible assets, which would not affect EBITDA. Kontron expects an agreement on damages before the end of 2026. Per the CEO (earnings call transcript), roughly EUR 9 million of VW invoices are already booked as other income in the third quarter; whether they qualify as income is still to be settled with the auditor. This is Kontron's account; we have no statement from Volkswagen.
The largest shareholder is Taiwan-based Ennoconn Corporation, whose own largest single shareholder is Foxconn parent Hon Hai. Following the mandatory offer at EUR 23.50 per share, Ennoconn has held 48.00 percent since August 21, 2026 per the voting rights notification - not a voting majority. On its group balance sheet, however, Ennoconn has carried the Kontron Group since July 1, 2017, on the basis of de facto control (annual report 2025, page 195).
Kontron confirmed on November 5, 2026 that it expects revenue of around EUR 1.6 billion and EBITDA of EUR 200 million, or EUR 225 million before restructuring. After nine months the books show EUR 125.9 million and EUR 151.0 million. The fourth quarter would therefore have to deliver roughly EUR 74 million of EBITDA and roughly EUR 497 million of revenue - after an implied adjusted EUR 50.2 million (presentation: EUR 50 million) and EUR 365.8 million in the third quarter. For comparison: for the fourth quarter of 2025 Kontron reported EBITDA of EUR 43.8 million (237.4 - 193.6), while the adjusted figures imply EUR 80.4 million (220.5 - 140.1) - so the missing roughly EUR 74 million would be 69 percent more or 8 percent less, respectively. The EUR 80.4 million is our own calculation from two reports, not a figure Kontron states.
Not for 2025: the annual general meeting resolved on June 30, 2026 to carry the full retained profit of EUR 147,330,587.59 forward; instead, Kontron bought back a total of 1,431,736 of its own shares for EUR 30.06 million through September 30, 2026. For fiscal 2026 the presentation accompanying the Q3 statement names a dividend proposal expected at EUR 0.65 per share. That has not been resolved yet.
Kontron is an Austrian stock corporation listed in the Prime Standard of the Frankfurt Stock Exchange, not a U.S. reporting issuer - there is no 10-K and no 10-Q. Its mandatory reporting consists of an audited IFRS annual report, a half-year financial report and unaudited quarterly statements. The half-year report itself is not audited: Kontron notes in it that the interim financial statements were subject to neither an audit nor an auditor's review. This analysis draws on the 2025 annual report, the 2026 half-year financial report and the Q3 statement of November 5, 2026.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.