Hensoldt Stock: The Order Backlog Passes €10 Billion — and the Cash Pays for It
Hensoldt builds radar, optronics and electronic-warfare systems for the battlefield — and on June 30, 2026 its order backlog passed €10 billion for the first time, at €10,356 million. Order intake doubled in the same half-year to €2,812 million, revenue grew 23.6 percent and adjusted EBITDA 28.5 percent. And still the cash went out: free cash flow of minus €255 million, with net financial debt including leases climbing from €701 million to €1,101 million in two quarters. Not a buy or sell recommendation — just the question of which of the two sets of numbers turns out to be right at year-end.
 Thomas Mücke
Founder & Publisher
Chart
Interactive price chart (TradingView).
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
There is an investor trap that catches the best-humored readers of all: looking in the rearview mirror. A stock newsletter celebrates last year's spectacular gains, and your mind instantly assumes the ride continues unchanged. Call it the rearview-mirror trap: what lies behind you says nothing about what lies ahead, but it feels reliable because it already happened once. A reader sent us issue 24 of the "Hot Stocks Europe" newsletter dated November 28, 2025 (B-Inside International Media GmbH, Freiburg, author Michael Calivas). On page 1, in a look back at the top performers of 2025, one single sentence mentions today's company: "Hensoldt and Renk: share-price gains of 100 to 300 percent." That is the entire hook - no company figure, no forecast, just a price range from the past. So let's make a deal: we leave that price range exactly where it belongs - in the past - and read the filings instead. The 2025 annual report (March 26, 2026), the quarterly statement as of March 31, 2026 (May 6, 2026) and, since July 31, 2026, the semi-annual financial report 2026. And that last one hands us the tension this analysis turns on: the order book has never been fuller - and the cash box has never been emptier.
What Hensoldt actually does - sensors and software for the battlefield
Hensoldt AG, headquartered in Taufkirchen near Munich, is a specialized provider of electronic sensor solutions for defense and security. Picture it this way: if a modern battlefield were a nervous system, Hensoldt builds the sense organs - radar, electronic warfare, avionics and optronics that tell a fighter jet, a frigate or an infantry fighting vehicle what is happening around it before it can see it directly. The company is a manufacturer-agnostic system integrator: it supplies sensor technology for platforms from different manufacturers - fighter jets, unmanned aerial vehicles, helicopters, ships and submarines, armored vehicles and satellites - to governments and supranational organizations such as NATO, either directly or through consortia such as Euroradar, which develops the Eurofighter's nose radar.
Reporting runs across two segments: Sensors (radar and electronic warfare, multi-domain solutions, services and training) and Optronics (optronics - sighting systems, periscopes, thermal imagers - complemented by radar and services). Well-known products include the TRML-4D radar (part of the IRIS-T SLM air-defense system, also deployed in Ukraine since the start of the war), the Eurofighter's ECRS Mk1 nose radar, the Spexer radar (offered as a naval solution against drones since 2025), and the PEGASUS signals-intelligence platform, where Hensoldt acts as consortium leader. With its MDOcore software suite, Hensoldt is also positioning itself as a provider of software-defined defense solutions, networking sensor and effector systems across domains. As of June 30, 2026, the group employed 9,679 people - 780 new hires since the turn of the year alone (December 31, 2025: 9,362). Self-funded research and development cost €93 million in the first half of 2026, equal to 8.0 percent of revenue.
Why there is no SEC filing here - and where the numbers come from instead
One point up front, because it shapes the entire evidence chain of this analysis: Hensoldt files no 10-K, no 10-Q. The company is not a U.S. registrant - a search of EDGAR, the electronic filing system of the U.S. securities regulator, the SEC, for the tickers HAG and HAGHY returns no usable filing. The one linked SEC identifier (CIK 0001856488, under the name "Hensoldt AG/ADR") contains nothing but F-6 forms, through which a depositary bank registers an American Depositary Receipt - not a single periodic report. Hensoldt's mandatory disclosures instead run through the regulated market (Prime Standard) of the Frankfurt Stock Exchange: an audited IFRS annual report, a half-year report subject to an auditor's review, and short, unaudited quarterly statements. Every figure in this analysis therefore carries "Source: fundamental data & company reports (annual/quarterly report, Frankfurt Stock Exchange)", not "SEC filings" - the same narrative logic ("a filing made under penalty of law is honest") still applies to an audited IFRS statement, just under German and European capital-markets law (Section 114 WpHG) rather than U.S. law.
This combination - MDAX member, yet not an SEC filer - is one Hensoldt shares with a number of other German industrial names. Our analysis of PFISTERER, also Xetra-listed and also without a 10-K or 10-Q, ran its entire evidence chain through the company's own annual and quarterly reports rather than sec.gov.
How the stock landed on our desk
Honesty first: the hook for this analysis is about as thin as it gets. A reader sent us issue 24 of the "Hot Stocks Europe" newsletter dated November 28, 2025 - Hensoldt does not appear there as a standalone pick, only in the editorial look-back on page 1: "Hensoldt and Renk: share-price gains of 100 to 300 percent" in 2025. No company figure, no forecast, no analyst price target - just a price range from the past. We have taken a look at the second name in that sentence as well: our analysis of RENK. The same issue featured Nokia in its main editorial section, as a position in the European AI and defense cycle.
Context matters here too: the newsletter itself discloses a conflict-of-interest note on page 8 - the publisher and author may hold long positions in securities discussed and intend to sell into rising prices (EU Market Abuse Regulation No. 596/2014) - a note worth keeping in mind with any stock newsletter, even when Hensoldt shows up only in a look-back.
The numbers over the years - honestly appraised
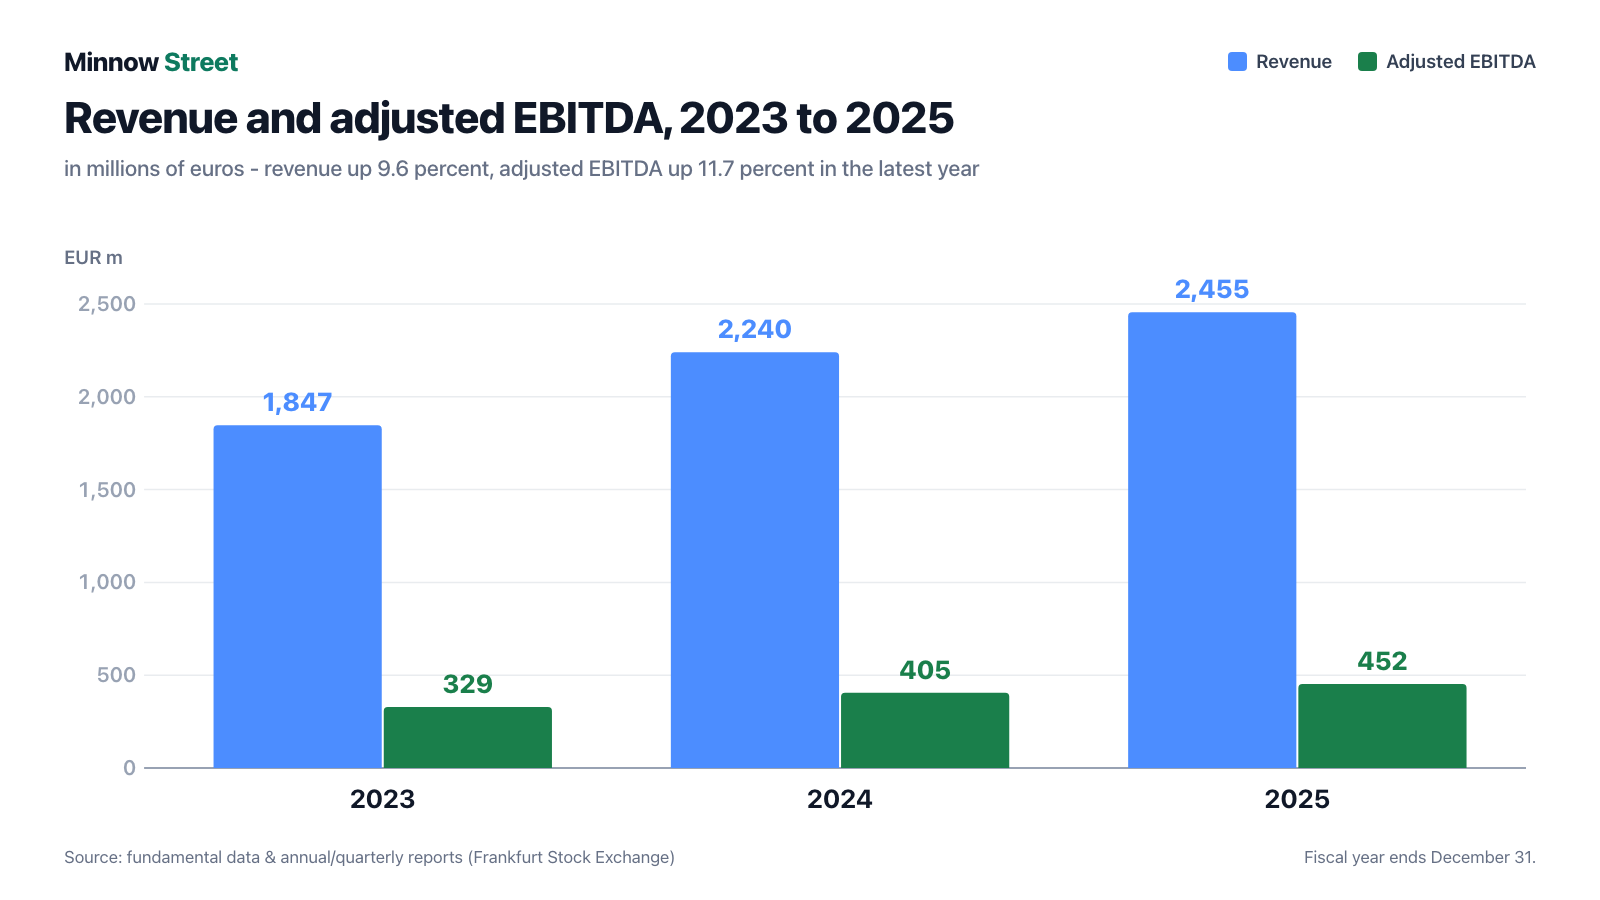
First, what genuinely impresses - and there is plenty of it. Hensoldt has grown for years: revenue of €1,847 million (2023), €2,240 million (2024), €2,455 million (2025), up 9.6 percent in the most recent year. Adjusted EBITDA - Hensoldt's own definition: earnings before interest, taxes, depreciation and amortization, adjusted for purchase-price-allocation effects and special items - grows by double digits: €329 million (2023), €405 million (2024), €452 million (2025), up 11.7 percent; the margin climbed from 18.1 to 18.4 percent.
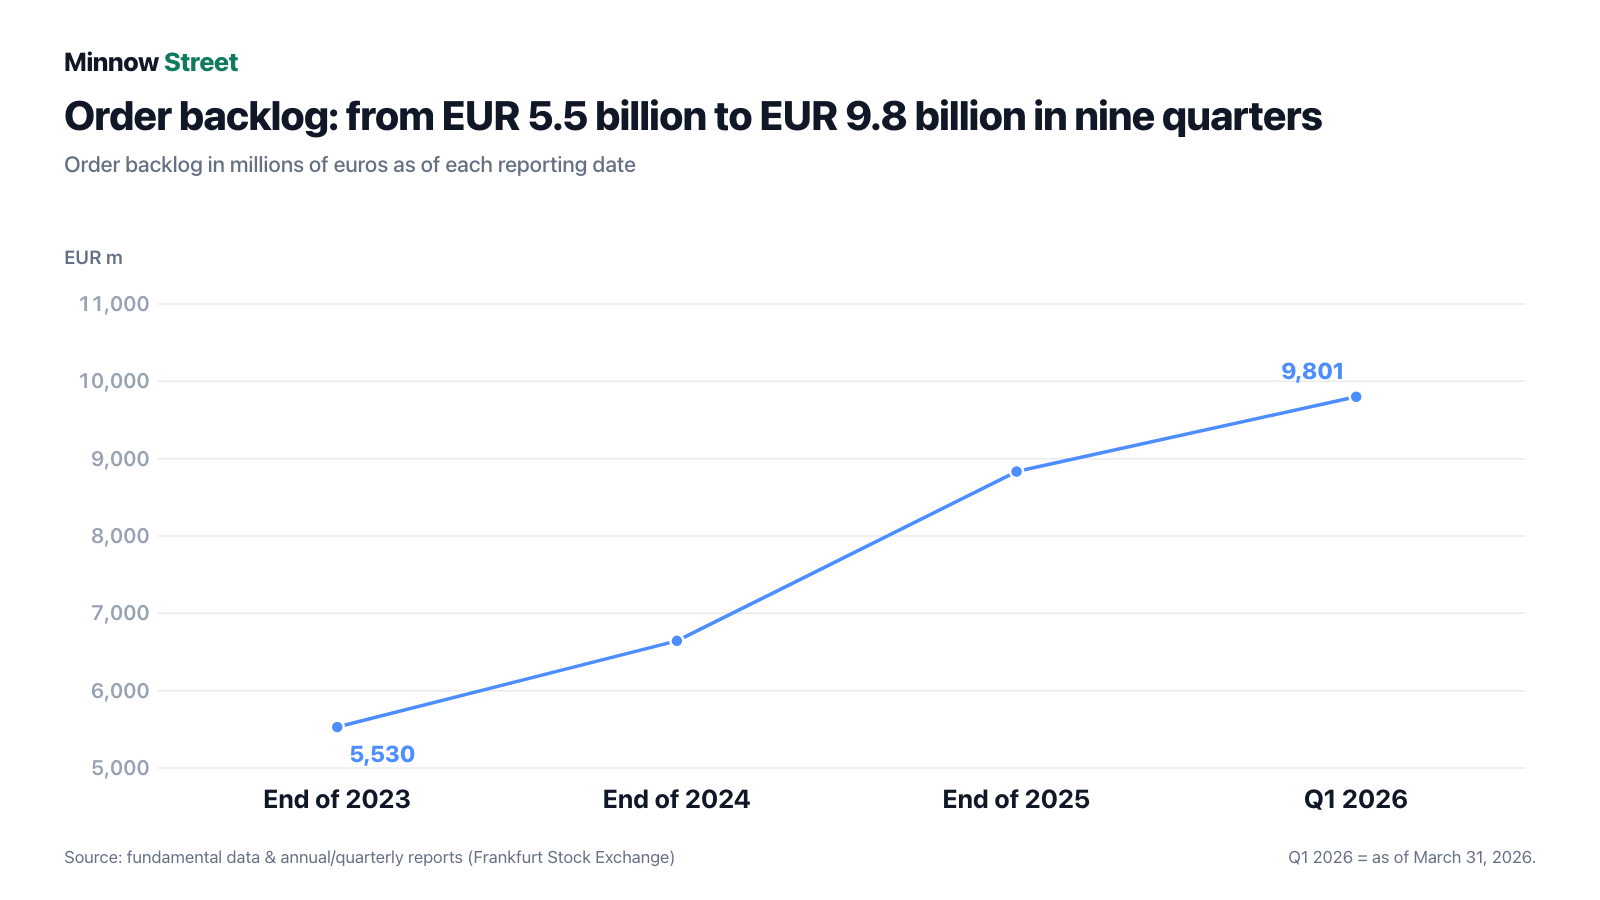
The order picture is even more impressive. Order intake jumped 62.2 percent in 2025 to €4,710 million (2024: €2,904 million), and the book-to-bill ratio rose from 1.3x to 1.9x - mainly because the Optronics segment booked billion-euro orders in the fourth quarter of 2025 to equip the Puma and Leopard 2 vehicles. The resulting order backlog grew from €5,530 million (end of 2023) through €6,644 million (end of 2024) to €8,833 million (end of 2025, up 32.9 percent), stood at €9,801 million on March 31, 2026 - and on June 30, 2026 reached €10,356 million, passing the €10 billion mark for the first time, a rise of 17.2 percent in six months. A year earlier, on June 30, 2025, it had been €7,070 million.
The half-year report of July 31, 2026 - what changed
The first edition of this analysis ended in late July with three open questions for the half-year report. Does free cash flow turn? Does debt come down? Does the order backlog keep growing? The report has been out since July 31, 2026, and it answers them with different degrees of clarity - two yes, one emphatic no.
The operating picture first, because it is strong. Order intake doubled in the first half of 2026 to €2,812 million (prior-year period €1,405 million), lifting the book-to-bill ratio to 2.4x from 1.5x. Revenue rose 23.6 percent to €1,167 million - about €1.17 billion - adjusted EBITDA 28.5 percent to €137 million, and the adjusted margin from 11.3 to 11.8 percent. Earnings before financial result and income taxes (EBIT) jumped from €6 million to €34 million, the net loss narrowed from €44 million to €13 million, and earnings per share improved from minus €0.36 to minus €0.09. Both segments contributed: Sensors lifted order intake 57.6 percent to €1,979 million, Optronics by more than 200 percent to €971 million - and there the adjusted EBITDA margin rose from 1.0 to 10.9 percent as the Ground Based Systems product line turned the Puma and Schakal contracts into production.
CEO Oliver Dörre put it this way in the half-year press release:
"The political decisions to increase defence spending are now being reflected in our order book. It is now down to industrial execution to determine how quickly these translate into real capabilities. For HENSOLDT, this entails a clear responsibility – we must demonstrate that we can not only deliver technology that gives our armed forces a genuine advantage but also have the capacity to supply it in the required quantities and at high speed."
— Oliver Dörre, Chief Executive Officer, in the press release on the first half of 2026 (July 31, 2026)
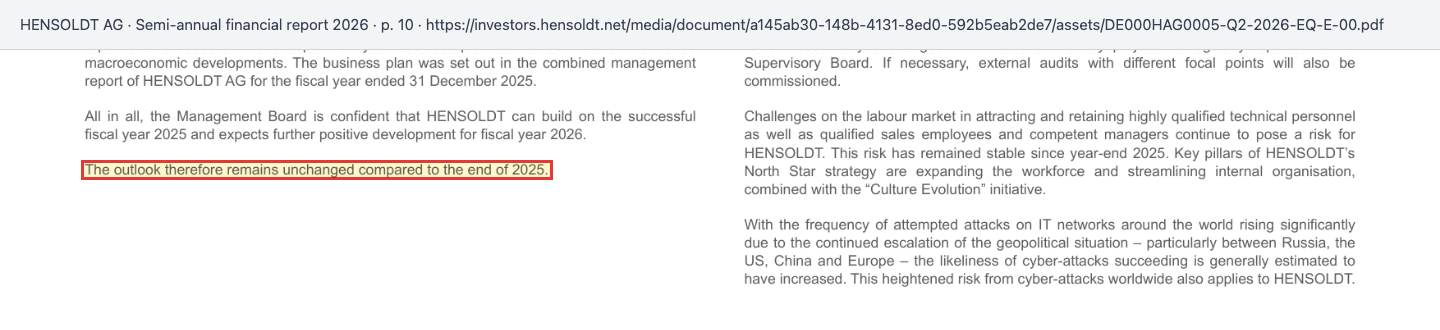
Guidance for 2026 stays as it was: revenue of about €2,750 million, a book-to-bill ratio of 1.5x to 2.0x, an adjusted EBITDA margin of 18.5 to 19.0 percent, and adjusted cash conversion of about 50 percent of adjusted EBITDA. The interim management report states it plainly, with no qualifier attached:
"The outlook therefore remains unchanged compared to the end of 2025."
— HENSOLDT AG, Semi-annual financial report 2026, interim management report section 5 "Outlook," page 10
Here, though, sits the arithmetic that is easy to skip while reading. After six months the adjusted EBITDA margin stands at 11.8 percent; the full-year target is 18.5 to 19.0 percent. Hensoldt explains that with its own business rhythm: deliveries and acceptances concentrate in the second half and above all in the fourth quarter. That is plausible and normal in this industry. It also means that the entire 2026 result gets earned in the closing months - and anyone ticking off "guidance confirmed" is really ticking off an expectation about the fourth quarter, not a result.
Two more changes from the reporting period belong in the fact box. On May 29, 2026 Hensoldt closed its acquisition of the Dutch Nedinsco Group (periscopes, driver vision systems, optomechatronic subassemblies) - a purchase price payment of €87 million, which added €68 million of goodwill to the balance sheet. In June 2026 it took a 5.3 percent stake in the German defense start-up Project Q GmbH, which is building a software platform for integrating situational awareness data and analyzing it with artificial intelligence. And since May 1, 2026 Inka Tews has served as Chief Human Resources Officer on the management board, turning a two-person board into a three-person board. After the reporting date, in July 2026, Hensoldt agreed to sell part of its stake in the Munich drone maker Quantum Systems; the remaining shares carry a fair value of €76 million on the balance sheet.
What the filings say - the uncomfortable truths
Uncomfortable truth no. 1: two-thirds of revenue depends on a single customer - the company's own government
Hensoldt sells to many armed forces worldwide - but the weighting is far from balanced. The 2025 annual report states it plainly:
"In fiscal year 2025, HENSOLDT generated around two thirds of its revenue in its home market of Germany."
— HENSOLDT AG, Annual Report 2025, Combined Management Report I.1 "Business model," page 24
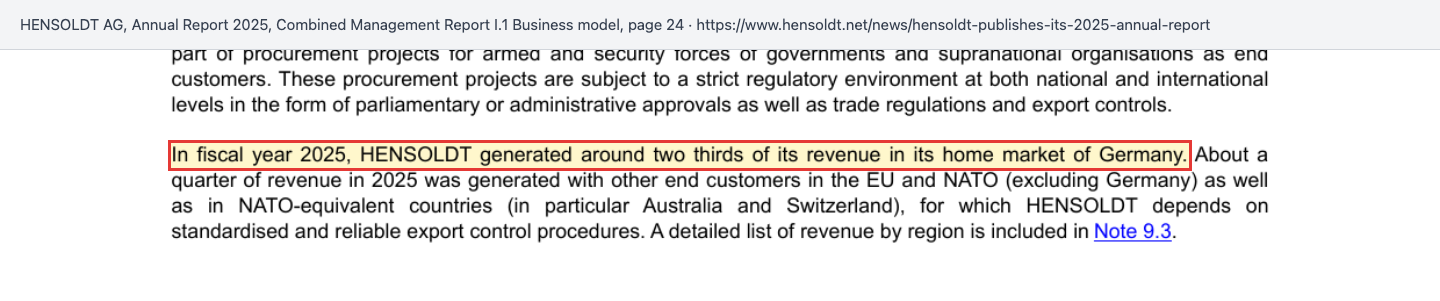
Roughly another quarter of 2025 revenue came from other EU and NATO countries plus NATO-equivalent states such as Australia and Switzerland - and every one of those orders runs through the same mechanisms: parliamentary approvals, export controls, defense budgets. Picture it this way: if a neighbor told you their small business was thriving, but two-thirds of revenue came from a single customer who decides on a fresh budget every year - would you pause? That is exactly the structure behind the record order backlog: it is real, audited, valuable - but it depends overwhelmingly on a single political decision, the German defense budget.
How real that is showed up on June 30, 2026: Germany's Federal Ministry of Defence cancelled the F126 frigate program and launched a MEKO A-200-class procurement instead. Hensoldt supplied the TRS-4D naval radar for F126 - a contract worth more than €200 million, of which more than a third had already been booked as revenue. The first edition of this analysis left open what traces that would leave in the half-year report. The answer is striking: none that are visible. The word "F126" does not appear once in the entire semi-annual financial report 2026 - no impairment, no provision, no separately disclosed adjustment to the order backlog. On the analyst call of July 31, 2026, CEO Oliver Dörre raised the topic himself, according to the call transcript, and called the financial impact "not material"; the contract value had been just over €200 million, with more than one-third already recognized as revenue. In its half-year presentation Hensoldt makes the same argument in general form: a single program can end without materially affecting the business, because exposure is spread across many platforms. That is a fair answer - and it does not change the fact that diversification across platforms is not the same thing as diversification across customers.
Uncomfortable truth no. 2: the entire full-year result has to appear in the fourth quarter
Here the numbers get interesting. In 2025, IFRS net income attributable to Hensoldt AG shareholders fell from €108 million to €89 million - down 17.6 percent - even as revenue grew 9.6 percent and adjusted EBITDA 11.7 percent. Earnings per share fell from €0.93 to €0.77. The gap sat between adjusted EBITDA and net income: depreciation and amortization rose to €181 million in 2025 (prior year €163 million), partly because Hensoldt had to recognize right-of-use assets under IFRS 16 for the first time, for the new Oberkochen site. The financial result worsened from minus €68 million to minus €94 million, and the tax charge rose from €12 million to €41 million as German loss carryforwards were used up.
The first half of 2026 has cleared part of that up. The financial result improved from minus €62 million to minus €32 million, because the loan newly agreed in April 2025 costs less than the previous financing and because currency and interest-rate hedges produced income this time rather than expense. Working the other way was tax: prior-year income tax income of €12 million turned into a €15 million charge. What remained was a half-year loss of €13 million, €11 million of it attributable to shareholders.
For you as an investor that means two things. First: a half-year loss is not an alarm signal at Hensoldt, it is the seasonal pattern - the first six months of 2025 also showed a €44 million loss, and the year closed with €89 million of profit. Second, and this is the uncomfortable part: precisely for that reason, the half-year says very little about the year. Remember this: when a company earns its whole annual result in the final quarter, confirmed guidance after six months is not proof, it is a promise. On 2025 earnings per share (€0.77) and a price of €87.44 (Xetra, August 4, 2026), the price-to-earnings ratio works out to about 114 - a valuation where a disappointing fourth quarter hits disproportionately hard.
Uncomfortable truth no. 3: free cash flow is deeply negative in the half-year too - and debt is climbing
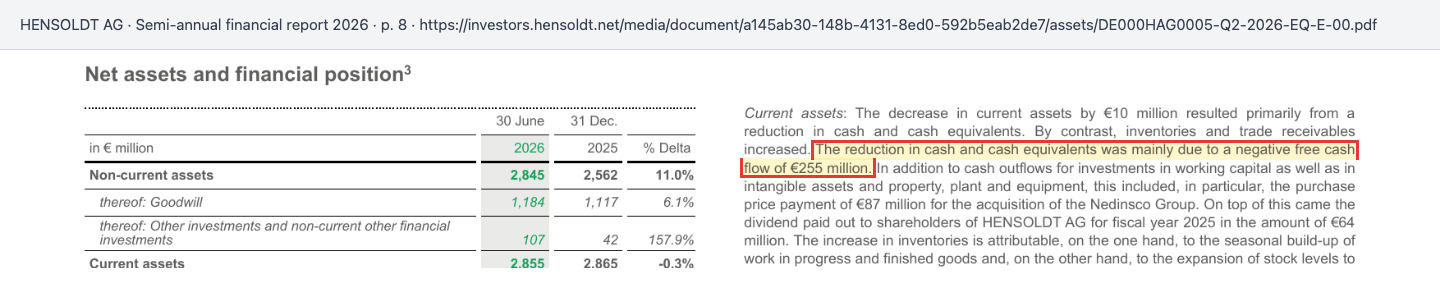
This is the question the half-year report answers most clearly, and the answer is no, it has not turned. After minus €115 million in the first quarter of 2026, the full first half shows free cash flow of minus €255 million (prior-year period minus €252 million). Adjusted for special items and acquisitions - Hensoldt's own steering metric - it is minus €136 million versus minus €181 million a year earlier, so that adjusted figure did improve. Cash itself fell from €933 million to €589 million.
"The reduction in cash and cash equivalents was mainly due to a negative free cash flow of €255 million."
— HENSOLDT AG, Semi-annual financial report 2026, section "Assets, liabilities and financial position," page 8
Adding financing and lease liabilities together and subtracting cash produces the measure Hensoldt itself applies to its leverage target (leases included, pensions excluded): €701 million on December 31, 2025, €833 million on March 31, 2026 and €1,101 million on June 30, 2026. That is €400 million more in two quarters - while the order backlog grew by €1.5 billion.
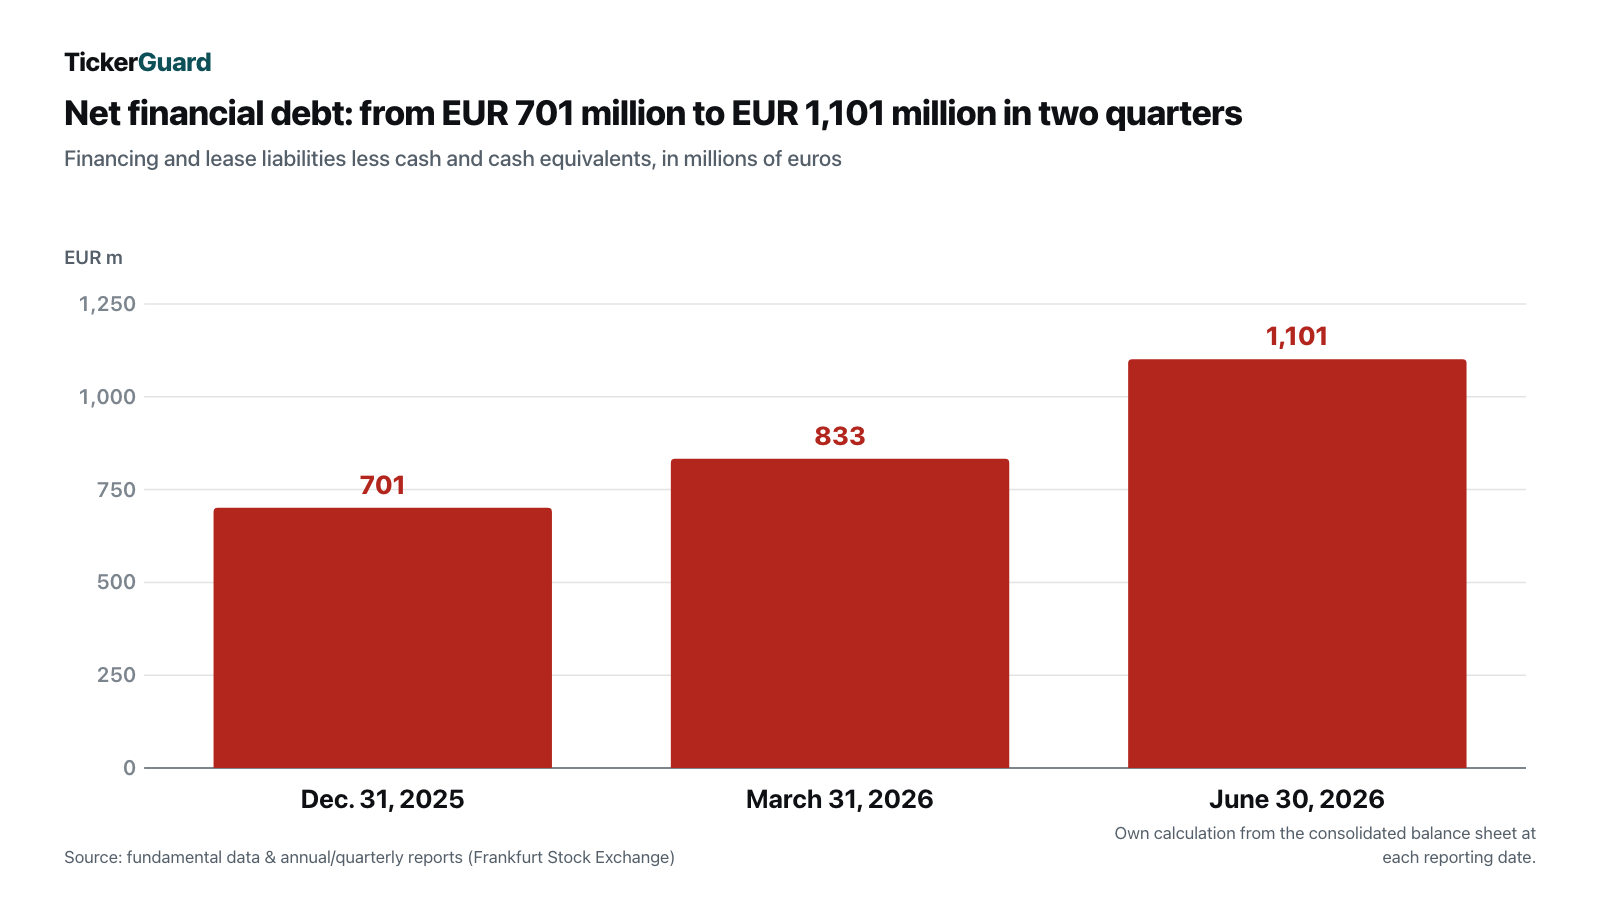
Part of that increase is explainable and one-off: €87 million for Nedinsco and €64 million of dividend have gone out and will not come back. The larger part sits in growth itself - inventories rose 22.2 percent to €1,073 million and trade receivables 13.2 percent to €494 million. Translated: Hensoldt is buying and building today for orders that get paid later. Working in the company's favor, customers are helping - contract liabilities, essentially advance payments received, grew by €247 million to €1,393 million. The financing side is orderly too: the syndicated facility agreed in April 2025, comprising an €850 million term loan and a €400 million revolving credit facility, was extended at the end of March 2026 to April 2, 2031.
Even so, the target is demanding. On June 1, 2026 Hensoldt had raised its 2026 cash conversion guidance from about 40 to about 50 percent of adjusted EBITDA while confirming a net leverage target of about 1.5x. Run that through the company's own EBITDA guidance (18.5 to 19.0 percent of about €2,750 million, or roughly €510 million to €520 million) and net debt would have to fall from €1,101 million to roughly €765 million to €785 million by year-end. That is not an impossible target - the fourth-quarter surge traditionally brings the cash receipts - but it is one of the most concrete, checkable commitments Hensoldt has made. The nine-month report on November 5, 2026 is the next milestone.
Valuation: a share price that has caught up - and a valuation that forgives nothing
Now back to the price range from the newsletter. "Share-price gains of 100 to 300 percent" in 2025 - is that accurate? Yes, and the annual report itself supplies the numbers that were not yet known in November 2025:
"… at one point reaching a new all-time high of €117.70. At the end of 2025, the shares were trading at €73.40, 112.8% above the €34.50 share price at the end of the previous year."
— HENSOLDT AG, Annual Report 2025, chapter "HENSOLDT on the Capital Market," page 11
After the all-time high of October 6, 2025 the stock corrected sharply - deepened by the resumption of Ukraine peace talks - down to a 52-week low of €63.12 on June 26, 2026. It has since recovered: €79.80 on July 24, 2026 and €87.44 on August 4, 2026 (Xetra). That is roughly 26 percent below the all-time high and roughly 19 percent above the 2025 year-end close - the price has caught back up with the order backlog after trailing it for half a year. Market capitalization works out to about €10.1 billion (roughly 115.5 million shares).
What does that mean for the valuation? On 2025 earnings per share (€0.77) the price-to-earnings ratio is about 114 - high, but not very informative, because reported 2025 earnings were depressed by depreciation and taxes. Enterprise value tells more: market capitalization of about €10.1 billion plus net financial debt of €1,101 million (June 30, 2026) equals roughly €11.2 billion. Measured against 2025 adjusted EBITDA (€452 million) that is about 25 times; measured against the company's own 2026 guidance (roughly €510 million to €520 million) about 22 times. For comparison, when the first edition of this analysis went out in late July, the same ratio on a 2025 basis stood at about 22. The stock has not become cheaper as the numbers improved - the market took the improvement and added a little on top.
The dividend for 2025 was €0.55 per share (prior year €0.50), approved with 99.99 percent support on May 22, 2026, with €64 million paid out. At the August 4, 2026 price that equals a yield of about 0.6 percent. Hensoldt's stated payout policy is 30 to 40 percent of adjusted net income.
Opportunities and risks at a glance
What speaks for Hensoldt:
- A record order position with visibility far into the future: order intake in the first half of 2026 doubled to €2,812 million, and the order backlog passed €10 billion for the first time (€10,356 million on June 30, 2026) - carried by the German defense budget (€108.2 billion planned for 2026) and NATO's target of 3.5 percent of GDP for traditional defense spending.
- Profitability is improving in both segments: adjusted EBITDA up 28.5 percent to €137 million in the half-year, with the margin at 11.8 percent versus 11.3 percent; in the long-weak Optronics segment the margin jumped from 1.0 to 10.9 percent.
- Guidance for 2026 fully confirmed on July 31, 2026 (revenue about €2,750 million, adjusted EBITDA margin 18.5 to 19.0 percent), with the cash conversion expectation actually raised on June 1, 2026. Mid-term, Hensoldt targets 15 to 20 percent annual revenue growth and about 50 basis points of margin improvement per year.
- Orderly financing: the syndicated facility of €850 million term loan plus a €400 million revolving credit line was extended to April 2, 2031, with €589 million of cash on hand at June 30, 2026 and no sign of covenant trouble. The German government (via KfW) and Leonardo S.p.A. together hold 47.9 percent of the shares.
- A growing software and capacity base: the Nedinsco acquisition (closed May 29, 2026), a 5.3 percent stake in Project Q, the new Optronics campus in Oberkochen - and, announced on August 4, 2026, a development centre for software-defined defence in the Stuttgart region with about 300 planned jobs, in cooperation with Bosch. On the same day, Germany's procurement office BAAINBw awarded a series contract for equipping dismounted Joint Fire Support Teams.
What speaks against it:
- Free cash flow is still deeply negative after six months: minus €255 million in the first half of 2026 (minus €136 million adjusted), with cash falling from €933 million to €589 million.
- Net financial debt including leases rose from €701 million to €1,101 million in two quarters. To hit the company's own net leverage target of about 1.5x, it would have to fall to roughly €765 million to €785 million by year-end.
- The entire 2026 result has to be earned in the second half and above all in the fourth quarter: after six months the adjusted EBITDA margin stands at 11.8 percent against a full-year target of 18.5 to 19.0 percent.
- Two-thirds of 2025 revenue depends on the German home market, with another quarter on other EU/NATO states - the June 2026 cancellation of the F126 program shows that live contracts can end with a single political decision, even though the financial effect left no trace in the half-year report this time.
- The equity ratio fell from about 18.5 percent (December 31, 2025) to about 17.2 percent (equity of €978 million against total assets of €5,700 million on June 30, 2026) - thin for the sector, though with no visible liquidity strain.
- Hensoldt names the execution risk itself in the half-year report: the sharp rise in order volume and the time pressure on development and production could weigh on delivery capability, and the risk from supply constraints for certain materials has been rising moderately since the end of 2025.
A human conclusion
Back to the rearview-mirror trap from the opening. The newsletter was not wrong about its price range - 112.8 percent to the 2025 year-end close, over 200 percent at one point to the all-time high. And right now, nine months later, it briefly looks as though the rearview mirror was right after all: the order backlog has passed €10 billion, the share price has caught up, guidance stands. That is exactly the moment when readers stop reading.
Anyone who keeps reading finds the second set of numbers in the same reports: free cash flow of minus €255 million, net financial debt up €400 million in two quarters, equity slightly smaller, and a full-year target that gets decided in the fourth quarter. None of that disproves the growth story - a defense group growing this fast has to burn cash first. But both sets of numbers sit in the same document, and only one of them makes the headlines. A look in the rearview mirror only shows how fast you were going, not how much fuel is left in the tank. What you make of it is your decision. And that is exactly as it should be.
Sources
All original documents used in this analysis - for your own reading:
- HENSOLDT AG - Semi-annual financial report 2026 (published July 31, 2026)
- HENSOLDT AG - Press release on the first half of 2026 (July 31, 2026) - source of the management quotes
- HENSOLDT AG - H1 2026 analyst presentation (July 31, 2026) - guidance table and mid-term targets
- HENSOLDT AG - Release on the raised cash conversion guidance and the net leverage target (June 1, 2026)
- HENSOLDT AG - 2025 Annual Report (published March 26, 2026)
- HENSOLDT AG - Quarterly statement as of March 31, 2026 (published May 6, 2026)
- HENSOLDT AG - Press release on the F126 program cancellation (June 30, 2026)
- HENSOLDT AG - Annual general meeting release (May 22, 2026, dividend approval)
- HENSOLDT AG - Fiscal-year-2023 press release - source of the 2023 comparison figures in the charts
- HENSOLDT AG - corporate news of August 4, 2026: development centre in the Stuttgart region and the BAAINBw series contract for dismounted Joint Fire Support Teams
- Investor relations page investors.hensoldt.net - publications, financial calendar, voting-rights notifications
- H1 2026 analyst call (July 31, 2026), transcript via Investing.com (retrieved August 4, 2026) - used solely for the quoted CEO statements on the F126 program and on manufacturing capacity
- Fundamental data (price, valuation; data as of August 4, 2026), reconciled with the annual and half-year reports.
- Hook: "Hot Stocks Europe" newsletter, issue 24, dated November 28, 2025 (B-Inside International Media GmbH, Freiburg) - cited as a third party's expectation, not used as a source for company figures.
Transparency & disclaimer: This analysis is a journalistic contextualization of publicly available information and is not investment advice, not a regulated financial analysis, and not a solicitation to buy or sell securities. Equity investments carry substantial risk, including total loss. All information is provided without warranty; the data cutoff for each figure is noted in the text, and the overall cutoff for this edition is August 4, 2026. The next interim report (nine months 2026) is scheduled for November 5, 2026. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this deep dive.
Our Bottom Line at a Glance
- Growth and order picture positive
- Order intake doubled in the first half of 2026 to €2,812 million, and the order backlog passed €10 billion for the first time at €10,356 million on June 30, 2026 (prior-year date €7,070 million). Revenue rose 23.6 percent to €1,167 million, for a book-to-bill ratio of 2.4x.
- Profitability positive
- Adjusted EBITDA rose 28.5 percent to €137 million in the first half of 2026, with the margin improving from 11.3 to 11.8 percent; in the long-weak Optronics segment it jumped from 1.0 to 10.9 percent. EBIT multiplied from €6 million to €34 million, and the net loss narrowed from €44 million to €13 million.
- Cash flow and leverage negative
- Free cash flow was minus €255 million in the first half of 2026 (prior-year period minus €252 million), or minus €136 million adjusted. Net financial debt including leases rose from €701 million (December 31, 2025) through €833 million (March 31, 2026) to €1,101 million (June 30, 2026), and the equity ratio fell from about 18.5 to about 17.2 percent.
- Quality of guidance neutral
- Guidance for 2026 was fully confirmed on July 31, 2026 (revenue about €2,750 million, adjusted EBITDA margin 18.5 to 19.0 percent, cash conversion about 50 percent). After six months, however, the margin stands at just 11.8 percent - the annual result has to be earned in the second half and above all in the fourth quarter.
- Customer concentration neutral
- About two-thirds of 2025 revenue came from the German home market. The cancellation of the F126 frigate program on June 30, 2026 left no visible trace in the semi-annual financial report 2026 - F126 is not mentioned there, and management called the impact not material on July 31, 2026. The structural risk remains regardless.
- Ownership and financing positive
- The German government (via KfW) and Leonardo S.p.A. together hold 47.9 percent of the shares, with free float at 52.1 percent (December 31, 2025). The syndicated facility of an €850 million term loan plus a €400 million revolving credit line was extended at the end of March 2026 to April 2, 2031, and €589 million of cash sat on the balance sheet at June 30, 2026.
Hensoldt is delivering operationally: order intake doubled in the first half of 2026, the order backlog passed €10 billion for the first time, revenue and adjusted EBITDA grew by double digits, and 2026 guidance was fully confirmed. At the same time free cash flow stayed deeply negative at minus €255 million and net financial debt including leases rose from €701 million to €1,101 million in two quarters - which leaves the full-year target to be settled in the fourth quarter. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
Yellow here is not about an existential question. The balance sheet at June 30, 2026 holds up: €589 million of cash, a €400 million credit line extended to 2031, positive equity of €978 million, no going-concern note and no visible covenant breach. And the business itself is clearly working better than a year ago: order intake doubled, the order backlog past €10 billion for the first time, adjusted EBITDA up 28.5 percent, and the Optronics margin up from 1.0 to 10.9 percent. Yellow stands because two operating questions remain open that the half-year report does not answer but postpones. First, the cash: free cash flow was still minus €255 million after six months, and net financial debt including leases rose from €701 million to €1,101 million in two quarters. To reach the company's own net leverage target of about 1.5x, it would have to fall to roughly €765 million to €785 million by year-end - a swing the first half did not anticipate. Second, the shape of the year: after six months the adjusted EBITDA margin is 11.8 percent against a full-year target of 18.5 to 19.0 percent. Both are explainable by the industry's delivery rhythm and both may well work out - but that is only proven with the annual accounts. On top of that sits the unchanged dependence on the German defense budget, which supplies about two-thirds of revenue. The next checkable milestone is the nine-month report on November 5, 2026. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- Update of August 4, 2026: this analysis was first published on July 26, 2026 and has been brought fully up to date after the semi-annual financial report of July 31, 2026 - figures, valuation, quality rating and images. The next interim report (nine months 2026) is scheduled for November 5, 2026.
- Net financial debt including lease liabilities (€1,101 million at June 30, 2026) is our own calculation from the consolidated balance sheet: financing plus lease liabilities less cash and cash equivalents. It matches the definition Hensoldt applies to its own net leverage target (leases included, pensions excluded) and reproduces the December 31, 2025 figure exactly.
- The hook for this analysis is issue 24 of the "Hot Stocks Europe" newsletter dated November 28, 2025 (B-Inside International Media GmbH, Freiburg), which mentions Hensoldt only in a page-1 editorial look-back ("share-price gains of 100 to 300 percent" in 2025) - no company figure, no price target. The newsletter carries a standard conflict-of-interest note on page 8: the publisher, author or related third parties may hold long positions in securities discussed and intend to sell into rising prices (EU Market Abuse Regulation No. 596/2014).
- All company figures come from the semi-annual financial report 2026 (July 31, 2026), the 2025 annual report (March 26, 2026) and the quarterly statement as of March 31, 2026 (May 6, 2026), not from the newsletter. Statements from the July 31, 2026 analyst call on the F126 program and on manufacturing capacity are marked as such. Data cutoff for price and valuation figures: August 4, 2026.
- Possible confusion: the ticker shorthand HAG.DE used in this analysis is simply a platform convention for "Hensoldt, listed in Germany" - not an official exchange code. The stock trades under Xetra: HAG as well as on Tradegate, Frankfurt and Gettex.
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace.
Frequently Asked Questions
Hensoldt AG, headquartered in Taufkirchen near Munich, develops and manufactures electronic sensor solutions for defense and security: radar, electronic warfare, avionics and optronics. The company is a manufacturer-agnostic system integrator for fighter jets, ships, armored vehicles and satellites, and employed about 9,679 people as of June 30, 2026 across its two segments, Sensors and Optronics.
Order intake doubled to €2,812 million and the order backlog reached €10,356 million, passing €10 billion for the first time. Revenue rose 23.6 percent to €1,167 million and adjusted EBITDA 28.5 percent to €137 million. The net loss narrowed from €44 million to €13 million, while free cash flow stayed deeply negative at minus €255 million.
Because spending runs ahead of revenue: inventories rose 22.2 percent to €1,073 million in the first half of 2026, on top of an €87 million purchase price for the Nedinsco Group and a €64 million dividend. Deliveries and cash receipts concentrate in the fourth quarter at Hensoldt. Cash fell from €933 million to €589 million as a result.
Yes, fully and unchanged on July 31, 2026: group revenue of about €2,750 million, a book-to-bill ratio of 1.5x to 2.0x, an adjusted EBITDA margin of 18.5 to 19.0 percent and adjusted cash conversion of about 50 percent of adjusted EBITDA. After six months the margin stands at just 11.8 percent - the annual result is earned mostly in the fourth quarter.
Germany's Federal Ministry of Defence cancelled the program on June 30, 2026. Hensoldt's contract for the TRS-4D naval radar was worth just over €200 million, of which more than a third had already been booked as revenue. F126 does not appear in the semi-annual financial report 2026 - no impairment, no provision. CEO Oliver Dörre called the financial impact "not material" on July 31, 2026.
About two-thirds of 2025 revenue came from the German home market, per the annual report, with another quarter from other EU/NATO countries. The €10,356 million order backlog (June 30, 2026) therefore depends overwhelmingly on a single political decision: the German defense budget, planned at €108.2 billion for 2026.
Hensoldt is listed on the Prime Standard of the Frankfurt Stock Exchange, not in the United States - there is no 10-K, no 10-Q, no SEC registration. It must publish an audited IFRS annual report, a half-year report and short, unaudited quarterly statements. This analysis draws on the 2025 annual report and the semi-annual financial report 2026.
Yes. For fiscal 2025, the annual general meeting approved a dividend of €0.55 per share (prior year €0.50) with 99.99 percent support on May 22, 2026; €64 million was paid out. At the August 4, 2026 price of €87.44 that equals a yield of about 0.6 percent. The stated payout policy is 30 to 40 percent of adjusted net income.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.