ImmunityBio Stock: 668 Percent Growth — and $4.6 Billion of Losses
ImmunityBio is the rare stock that lands on our triple-digit revenue growth list AND on three warning lists in the same scanner run. Revenue rose 668 percent in 2025 to $113.3 million and reached $50.7 million in the second quarter of 2026 — and behind it sit $4.6 billion of accumulated losses, a going-concern warning and a billionaire who carries the company and lends it money at the same time. We read the annual and quarterly reports through June 2026 and show you who gets paid first when this growth turns into cash.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 30, 2026
- Closing price
- 8.30 $ -5.10%
- Market Capitalisation
- 8.6 $B
- Growth Score
- 6/10
- AAQS
- 4/10
Price change since August 4, 2026: +15.3%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot

Chart
Interactive price chart (TradingView).
52-week range: 2.00 $ to 11.60 $ · Last price: 8.30 $ (As of: October 30, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
There is one pull that even experienced investors find hard to resist: the rescue story with a big name behind it. A cancer immunotherapy, cleared by the U.S. regulator. Revenue that more than multiplied sevenfold in 2025. And a billionaire founder who props up the company with his own money and his own loans. By early July 2026 the stock had more than tripled within six months. The voice on your shoulder whispers: "this is the next big biotech bet — and a rich man is standing behind it with his own money, he will not let it fall." Call that thought the rescuer reflex. It is dangerous because it skips two questions: why does a billionaire have to keep putting money in at all? And what happens to your slice while he does it? So let's make a deal. Before you touch a single share of ImmunityBio (Nasdaq: IBRX), we read together what the filings to the U.S. securities regulator, the SEC, actually say. An SEC filing is honest under penalty of law. And at ImmunityBio it tells two stories at the same time. What you make of it at the end is your decision.
Update: the second quarter of 2026 at a glance
This analysis first appeared in July 2026, based on the 2025 annual report and the first-quarter report. On August 4, 2026 ImmunityBio filed its quarterly report (10-Q) as of June 30, 2026 and, the same day, its earnings release. We read both and carried the new figures through the entire text. Here is what matters most.
Revenue keeps growing — without a single outlier. ANKTIVA net product revenue came to $50.7 million in the second quarter of 2026, up 92 percent from the year-ago quarter and 15 percent from the first quarter. According to the company, that is the eighth straight quarter of sequential growth since launch. The first half brought $94.8 million, up 121 percent. New is a small amount of European revenue: $0.5 million in the quarter — the first meaningful sum outside the U.S.
The operating loss is shrinking, but it has not gone away. The loss from operations was $61.7 million, after $69.8 million in the first quarter and $71.3 million a year earlier. Operating cash outflow — the cash the day-to-day business consumes — was $141.9 million in the first half; subtracting the $75.4 million of the first quarter leaves roughly $66.5 million for the second. That is better, but still more than the entire quarter's revenue.
The book loss balloons again — for the same reason as in the first quarter. The bottom line shows a $230.4 million net loss for the second quarter and $863.2 million for the half year. Most of it is remeasurement: $96.0 million for the convertible founder debt and $44.2 million for the warrants, because the share price rose from $7.67 (March 31, 2026) to $8.76 (June 30, 2026). That costs no cash, but it pushes stockholders' equity further below zero: minus $1.05 billion as of June 30, 2026, after minus $0.50 billion at the end of 2025.
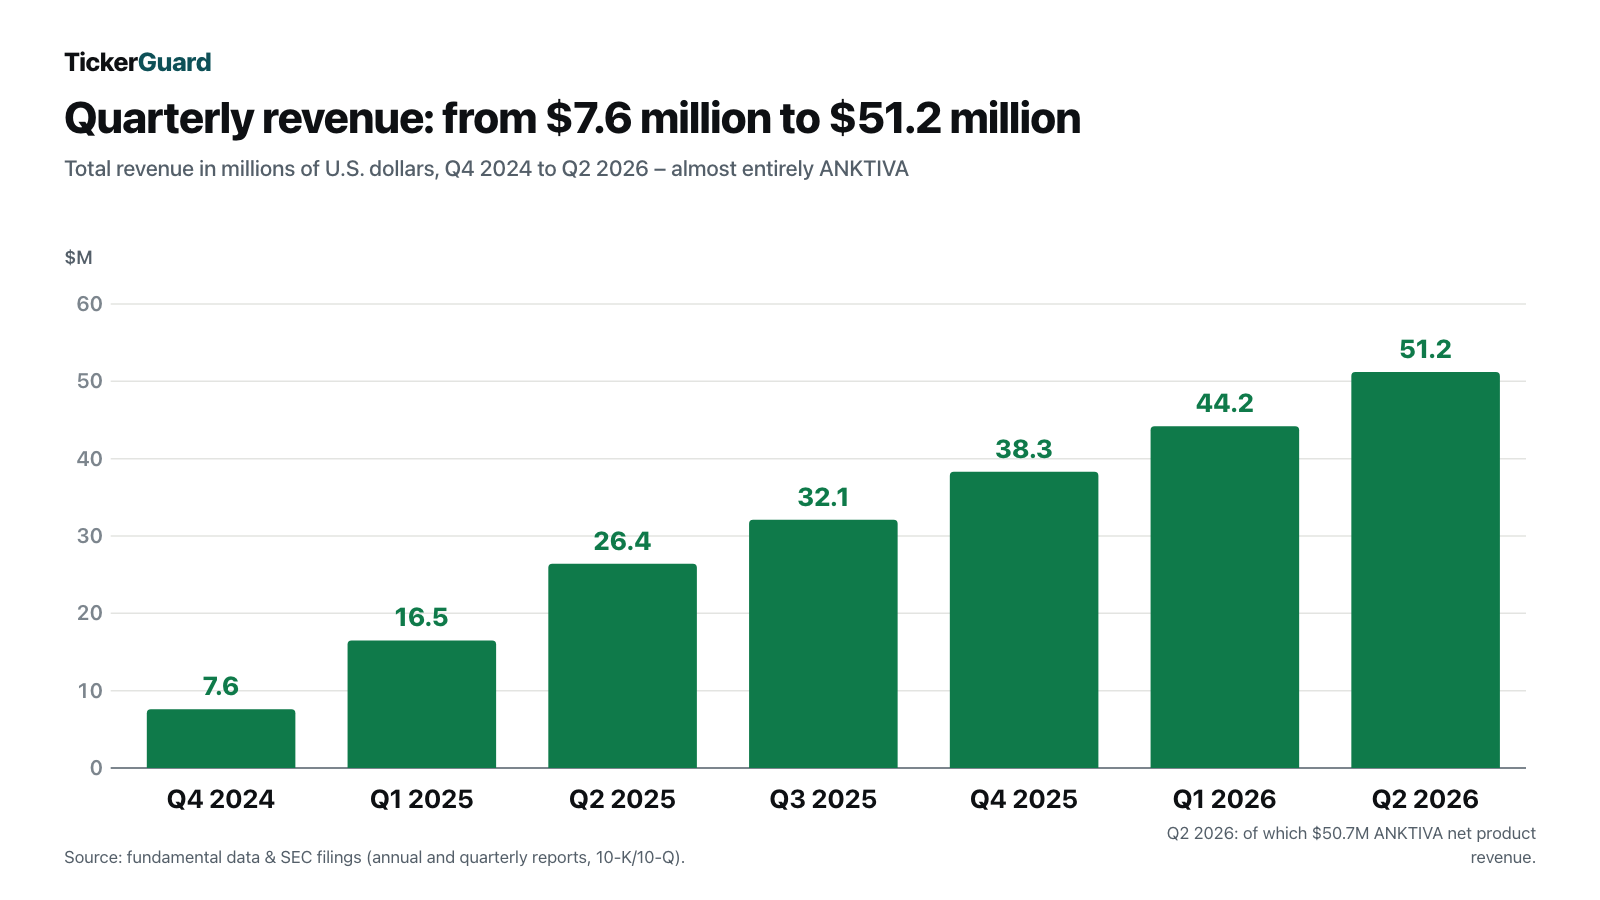
The cash: $357.4 million — again from other people's money. As of June 30, 2026, cash and marketable securities stood at $357.4 million, after $380.9 million on March 31. Management sounds confident in the earnings release:
“With $357.4 million in cash and cash equivalents, and marketable securities, we are well-positioned to support both our commercial and clinical priorities.”
— Richard Adcock, President and CEO, second-quarter 2026 earnings release, current report (8-K) of August 4, 2026, Exhibit 99.1
Same day, same sender, different document — the quarterly report still carries the sentence we know from the annual report:
“As a result of continuing anticipated operating cash outflows as we commercialize our approved product and accelerate our development efforts, we believe that substantial doubt exists regarding our ability to continue as a going concern without additional funding or financial support.”
— ImmunityBio, Inc., quarterly report (10-Q) as of June 30, 2026, Note 1 “Liquidity”
Where the first-half money came from is visible in the cash flow statement: $147.2 million from selling new shares through the ATM program ($45.1 million of it in the second quarter), $74.9 million from a third payment by the lender Oberland in exchange for a larger revenue interest, and $53.5 million from exercised warrants. After quarter-end another $21.1 million came in from 6.4 million exercised warrants. The ATM program still has $349.2 million available for further share sales. The earnings release names no earnings call, and no transcript was available to us for this quarter; we therefore worked from the quarterly report and the earnings release. ImmunityBio gives no revenue guidance for 2026.
What moved in the pipeline. The FDA accepted the supplemental application for patients with papillary-only bladder cancer without carcinoma in situ; the decision date is January 6, 2027. The United Arab Emirates authorized ANKTIVA in July 2026 for bladder cancer and advanced lung cancer, which according to the company brings it to five regulatory jurisdictions and 34 countries. In May 2026 ImmunityBio secured exclusive U.S. rights to a second BCG strain (Tokyo-172) from Japan BCG Laboratory — no payment is due before an FDA approval of that strain. A further application for patients never treated with BCG (QUILT-2.005 trial) is planned for 2026.
And the uncomfortable news: a second creditor stands ahead of the founder. According to the quarterly report, Soon-Shiong's loan is expressly subordinated to Oberland's revenue interest. That arrangement (the "RIPA" in the filing) works like a mortgage on revenue: Oberland has paid $375.0 million so far and receives 5.625 to 12.5 percent of worldwide net sales every quarter until 1.95 times that sum has flowed back — roughly $731 million. The balance sheet carries the obligation at $415.1 million (June 30, 2026), more than cash and securities combined. And it is secured:
“To secure the company’s obligations under the RIPA and the subsidiary guarantors’ obligations under the guarantees, each of the company and the subsidiary guarantors has granted a security interest in substantially all its assets, subject to certain exceptions and limitations.”
— ImmunityBio, Inc., quarterly report (10-Q) as of June 30, 2026, Note 10 “Revenue Interest Purchase Agreement”
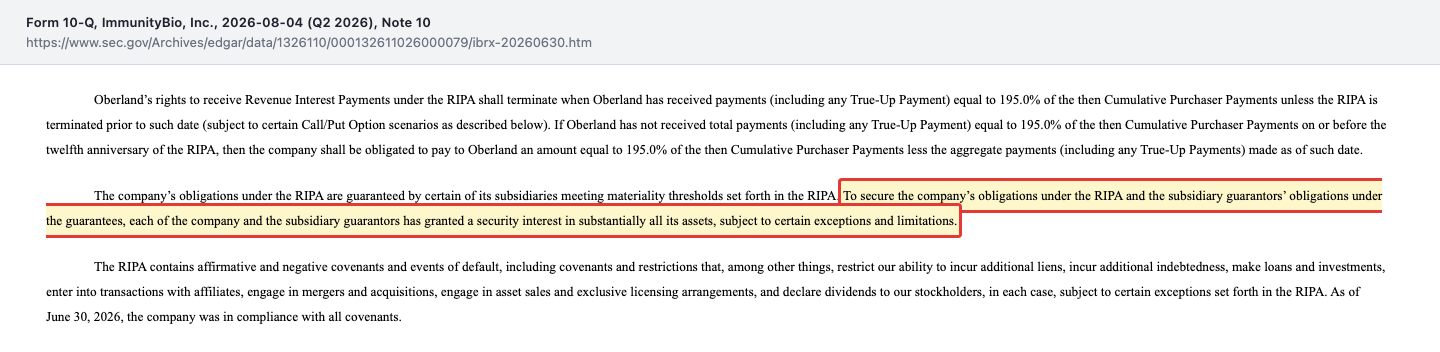
For you as a shareholder that means: from every ANKTIVA dollar, Oberland's share comes off first, then the founder's interest. In the second quarter ImmunityBio booked $17.2 million of interest expense on the revenue interest and $14.0 million of interest to the founder's entity Nant Capital — $31.2 million together, a little over 60 percent of quarterly revenue. Part of that is imputed rather than paid in cash; cash interest paid in the first half was $40.1 million. Remember: the growth does not belong to shareholders alone — two creditors are standing in line ahead of them.
Company history for investors
-
2015
IPO as NantKwest
Today's ImmunityBio listed on the Nasdaq in July 2015 under the name NantKwest — back then a cell therapy developer without product revenue.
-
2021
NantKwest becomes ImmunityBio
In March 2021 NantKwest and NantCell combined their businesses; the company has been called ImmunityBio since, with the compound from Altor, acquired in 2017 and today's ANKTIVA, at its center.
-
2023
Revenue interest sold to Oberland
In December 2023 ImmunityBio sold Oberland a share of future revenue — money up front that later ANKTIVA sales have to serve first.
-
2024
FDA approval for ANKTIVA
In April 2024 the FDA approved ANKTIVA for an early form of bladder cancer; the developer became a company with product revenue.
-
2026
Partial conversion and third Oberland payment
In late March 2026 the founder converted $25.0 million of his loan into stock, and Oberland paid $75.0 million for a larger revenue interest.
-
2026
Second quarter with $50.7 million of revenue
On August 4, 2026 ImmunityBio reported $50.7 million of ANKTIVA revenue, still with a going-concern warning; the FDA decides on an expansion by January 6, 2027.
What ImmunityBio actually does
ImmunityBio is a biotech company from San Diego with exactly one product on the market: ANKTIVA. Behind the brand sits a compound called N-803, and you can picture it as a wake-up call for the body's own guard force. Your immune system keeps its own troop against degenerate cells — the "natural killer cells" and the T cells. ANKTIVA is a synthetic copy of a messenger substance that switches this troop on and multiplies it. It is given together with the ancient tuberculosis vaccine BCG, directly into the bladder, in an early form of bladder cancer (NMIBC with carcinoma in situ) in which BCG therapy alone no longer works. The promise: instead of removing the bladder surgically, the body is meant to beat the tumor itself. The FDA approved ANKTIVA in April 2024; it will decide by January 6, 2027 on an expansion to patients with papillary-only tumors.
The market is real and the need is large. According to ImmunityBio's own annual report, bladder cancer is the sixth most common cancer in the United States; roughly 84,500 new cases are expected for 2026, and the early form NMIBC accounts for about three quarters of all cases. On top of that comes a structural tailwind: the standard compound BCG has been scarce in the U.S. for years — per the annual report (10-K), 57 percent of urologists therefore cannot treat patients as intended. ANKTIVA pushes into that gap, and with access to a second BCG strain agreed in May 2026, ImmunityBio also wants to tackle the shortage of the partner drug itself. Sounds like a rounded growth story? It is one — until you open the balance sheet. And that is exactly where it gets interesting.
Where the stock shows up in our scanner
Every day we run roughly 3,500 stocks through our in-house stock scanner. ImmunityBio triggered 17 of them (data as of July 7, 2026) — and that list is the real reason for this analysis, because it contradicts itself. On one side the stock sat in the growth and momentum scanners: "triple-digit revenue growth", "high revenue growth", "RS leader (90 or above)", "Stan Weinstein: stage 2", "Qullamaggie top gainers 6M" and several trend filters. At the time the stock ran better than 94 percent of the market and had more than tripled within six months.
On the other side — and this is rare — the very same stock sat simultaneously on three warning lists: the going-concern warning proxy, the Altman-Z distress zone (a statistical early-warning model for insolvency) and the Beneish M-Score list. It practically never happens that one name triggers the strictest growth scanner and the harshest balance-sheet warning filters in the same run. Remember this tension — the growth is real, the base is small, and the balance sheet is fragile. It is the thread through everything that follows. Here is how to get there yourself: on tickerguard.com, open the "Scanner" menu, pick the filter "triple-digit revenue growth" and look for the IBRX row — the hit list is updated daily and may look different today than on July 7, 2026.
The numbers over the years — first what impresses
Let's start with what is genuinely strong. The revenue growth is not an accounting illusion but a real product ramp. ANKTIVA came to market in mid-2024, and since then revenue has risen quarter after quarter — according to the company for eight quarters in a row through June 2026, without a single outlier. The chart in the update section above shows the path since the fourth quarter of 2024: $7.6, $16.5, $26.4, $32.1, $38.3, $44.2 and most recently $51.2 million of total revenue per quarter.
On an annual basis that means: $0.6 million (2023, before approval, other revenue only), $14.7 million (2024), $113.3 million (2025) — up 668 percent. And the growth continues: in the first half of 2026 ANKTIVA net product revenue reached $94.8 million, 121 percent above the prior-year period; the four quarters through June 2026 add up to roughly $166 million of revenue. The gross margin, at roughly 99 percent, is a dream, as is usual with drugs — manufacturing costs almost nothing, the research behind it costs everything. That is one half of the story, and it is a good one. Eight rising quarters in a row are no longer a lucky hit but a trend.
What the filings say — the uncomfortable truths
Now we turn the page. Literally.
Uncomfortable truth no. 1: the company doubts its own survival
There is one sentence no company writes voluntarily, because it is a legal alarm button: the going-concern warning. "Going concern" is the accountant's term for a business that can be expected to keep operating — and when an auditor doubts that, it has to go into the report. At ImmunityBio it is in there, in the 2025 annual report as well as in the quarterly report as of June 30, 2026. You already read the quarterly report's wording in the update above; here is the slightly longer version from the annual report:
“As a result of continuing anticipated operating cash outflows as we commercialize our approved product in the U.S. and globally and accelerate our development efforts, we believe that substantial doubt exists regarding our ability to continue as a going concern without additional funding or financial support.”
— ImmunityBio, Inc., SEC annual report (10-K) for fiscal year 2025, MD&A “Liquidity”

The reason for the doubt is one plain number: by December 31, 2025 ImmunityBio had piled up an accumulated deficit of $3.7 billion, and by June 30, 2026 it was already $4.6 billion. An accumulated deficit is the sum of every loss since the company was founded — it shows how much money the business has burned over the years. For comparison: against it stand $113.3 million of revenue for 2025. You have to put those magnitudes side by side once:

Uncomfortable truth no. 2: a billionaire carries the company — and is its creditor at the same time
Formally, the going-concern doubt counts as alleviated — in the quarterly report as of June 30, 2026, too. But read carefully with what ImmunityBio alleviates it:
“…will be sufficient to fund our operations through at least the next 12 months following the issuance date of the consolidated financial statements based primarily upon our Founder, Executive Chairman and Global Chief Scientific and Medical Officer's intent and ability to support our operations with additional funds, including loans from affiliated entities, as required, which we believe alleviates such doubt.”
— ImmunityBio, Inc., SEC annual report (10-K) for fiscal year 2025, MD&A “Liquidity”
So the company stands because one man promises to prop it up: Dr. Patrick Soon-Shiong, founder, chairman and billionaire (he once invented the cancer drug Abraxane). He controls more than 60 percent of the shares — according to his ownership filing (Schedule 13D/A) of August 6, 2026, about 62 percent of the shares outstanding, and 64.8 percent including his conversion right. That is why the annual report formally classifies ImmunityBio as a "controlled company" under the Nasdaq rules. That sounds reassuring, but it has an uncomfortable flip side: Soon-Shiong is not only the owner, he is also the lender. The company owes an entity affiliated with him a loan whose terms the filing discloses:
“As of December 31, 2025, we have a $505.0 million variable-rate loan outstanding, which matures on December 31, 2027 and bears interest at Term SOFR plus 8.0% per annum. As of December 31, 2025, the interest rate on this loan was 11.66%.”
— ImmunityBio, Inc., SEC annual report (10-K) for fiscal year 2025, Item 7A “Market Risk”

A founder who is majority owner and expensive creditor at the same time — that is a structural conflict of interest and a cluster risk concentrated in a single person. As long as he props the company up, it survives. Since January 2026 his entity Nant Capital may convert the loan into stock at $5.427 per share at any time, in whole or in part — and it has done so: on March 31, 2026 it converted $25.0 million into 4.6 million new shares. That leaves $480.0 million outstanding (June 30, 2026). If the rest were converted, roughly 88.4 million more shares would be created — the debt would be gone, but his stake would grow further, and yours would shrink.
Uncomfortable truth no. 3: the cash pile does not come from the business
At first glance the cash position looks healthy: $149.8 million at the end of 2024, $242.8 million at the end of 2025, $380.9 million as of March 31, 2026 and $357.4 million as of June 30, 2026. Except this balance did not grow because ANKTIVA brings money in, but because ImmunityBio keeps raising fresh capital. The filing names the sources itself:
“During the year ended December 31, 2025, we received net proceeds totaling $250.1 million from the issuance of shares under the ATM.”
— ImmunityBio, Inc., SEC annual report (10-K) for fiscal year 2025, MD&A “At-the-Market Offering”

An "ATM" program (short for at-the-market) is a selling machine for fresh shares: the company continuously issues new paper straight into the market and pockets the money. In the first half of 2026 it brought in another $147.2 million net; $349.2 million remains available (June 30, 2026). For you as a shareholder that means dilution — picture a pizza that keeps getting cut into more slices: your slice gets smaller even though you sold nothing. The numbers are clear. The share count rose from 852.9 million (end of 2024) to 1,011.8 million (end of 2025, up 18.6 percent), to 1,053.2 million as of June 30, 2026 and to 1,059.8 million as of July 31, 2026. On top come 41.5 million warrants still outstanding (as of August 4, 2026) and the roughly 88.4 million shares from the founder's conversion right. Authorized shares stand at 1.65 billion — plenty of room for more dilution. Remember the mechanism: growth paid for with fresh shares is never entirely free.
And the billion-dollar losses in 2026? Not as bad as they look
Fairness demands the other direction too. The headline for the first quarter of 2026 was a net loss of $632.8 million — almost twice the loss of the whole of 2025 — and the second quarter added another $230.4 million. That sounds like a catastrophe, but it is mostly an accounting effect and, paradoxically, a consequence of the share price rally. The operating loss was only $69.8 million in the first quarter and $61.7 million in the second. The rest are non-cash revaluations: in the first half together $339.6 million from remeasuring warrants and $332.6 million from remeasuring the convertible founder debt. Because the share price rose, these items — carried as liabilities — became more expensive in the income statement. That inflates the book loss but costs not one cent of cash. Anyone taking this loss literally dramatizes it wrongly. What stays honest, though: the operating cash outflow of $75.4 million in the first quarter and roughly $66.5 million in the second, and the dilution, continue.
Valuation — what the market is actually paying for here
At the closing price of $8.44 on September 25, 2026 and 1,059.8 million shares (July 31, 2026), ImmunityBio weighs in at roughly $8.9 billion. Against that market value stand about $166 million of revenue in the four quarters through June 2026; annualizing the second quarter would give a little over $200 million. That works out to a price-to-sales ratio of roughly 44 to 54. For context: an established, profitable company is often valued at one to five times revenue. Here the market is paying more than forty times.
What does that mean? The price is not valuing today's business but a multi-billion blockbuster future: the hope that ANKTIVA grows into further bladder cancer stages, into lung cancer and into additional tumor types, and that the broad pipeline delivers. That can work out — every new approval would scale the same compound, and at a 99 percent gross margin the leverage would be enormous. The next test is fixed: the FDA decision on papillary-only tumors by January 6, 2027. It can also fail, and then billions of dollars of expectation are air. Keep in mind: before growing revenue reaches shareholders, Oberland and the founder are served first. The five analysts covering the stock are optimistic in consensus (three "strong buy", two "buy", an average price target of $12.75, data as of September 27, 2026). Average here means: all price targets added up and divided by their number — with only five voices, a single outlier moves it noticeably. That is "the professionals' view" — but it is few professionals, and price targets are snapshots, not certainties.
Opportunities and risks at a glance
What speaks for ImmunityBio:
- The first FDA approval is in hand — ANKTIVA is on the market, and revenue is growing for real and without outliers (eight rising quarters through June 2026, according to the company).
- Every further approval scales the same compound — next date: the FDA decision on papillary-only tumors by January 6, 2027; plus authorizations in the United Arab Emirates and a planned application for patients without prior BCG treatment.
- Structural tailwind from the BCG shortage — and with the Tokyo-172 strain a second potential BCG supply route without upfront payment.
- A billionaire with deep pockets and skin in the game stands behind the company — that genuinely dampens the near-term insolvency risk; operating cash outflow fell to roughly $66.5 million in the second quarter of 2026.
What speaks against it:
- An explicit going-concern warning, also in the quarterly report as of June 30, 2026; $4.6 billion of accumulated losses and minus $1.05 billion of stockholders' equity against about $166 million of revenue over four quarters.
- Two creditors ahead of shareholders: the founder ($480.0 million convertible loan, carrying 11.66 percent at the end of 2025) and Oberland (revenue interest, $415.1 million liability, secured by substantially all assets).
- Ongoing dilution: share count up 18.6 percent in 2025 and another 4.7 percent through the end of July 2026, $349.2 million of ATM capacity left, 1.65 billion authorized shares.
- One product, almost one market (99 percent U.S. in the second quarter of 2026), strong competition from Keytruda (Merck), Adstiladrin (Ferring) and Inlexzo (Johnson & Johnson); on top of that a very high short interest (roughly 31 percent of the free float, data as of September 27, 2026).
A human conclusion
Do you remember the rescuer reflex from the opening — the voice saying "a billionaire is behind it, he will not let it fall"? After a look at the filings it sounds different. Yes, a billionaire is behind it. But he is behind it because the company cannot make it alone — even after the second quarter of 2026, the going-concern doubt counts as alleviated only for as long as he is willing to keep injecting money. And that money costs you as a shareholder something: the interest on his loan, ever more new shares that shrink your slice of the cake — and a second financier who secures his share of revenue ahead of you. ImmunityBio is therefore both at once — a real growth story with an approved drug and a fragile balance sheet propped up by a single human being. That is exactly why the stock appeared on the growth list and on three warning lists in the same scanner run. It is not a contradiction you can argue away — it is the core of this stock.
What you make of it is your decision. And that is exactly as it should be. If you buy ImmunityBio, you are buying a bet on a drug's blockbuster future — and a trust in one individual man. If you avoid it, you may be passing up the next biotech rocket. Both are legitimate. What matters is only that you know what you are betting on — on both halves of the story, not just the pretty one.
The pattern is not unique to ImmunityBio. At Iovance, a commercial-stage cell therapy company, product revenue climbed to $263.5 million in 2025 — and shareholders financed that year almost to the dollar: 101,899,334 new shares brought in $306.3 million net against $302.4 million of operating cash burn. At Agenus, the going-concern sentence stood in the quarterly report as of March 31, 2026, next to negative equity of $228.0 million and warrants over 54.9 million shares — more than the company had outstanding on July 17, 2026. In all three cases the money that keeps the lights on comes from the capital market, not from the business. What sets ImmunityBio apart is only who writes the check: not an anonymous market alone, but one man who is also the lender.
Sources
- ImmunityBio, Inc. — annual report (10-K), fiscal year 2025 (filed February 23, 2026)
- ImmunityBio, Inc. — quarterly report (10-Q), first quarter of 2026 (as of March 31, 2026, filed May 7, 2026)
- ImmunityBio, Inc. — quarterly report (10-Q), second quarter of 2026 (as of June 30, 2026, filed August 4, 2026)
- ImmunityBio, Inc. — second-quarter 2026 earnings release, current report (8-K) of August 4, 2026, Exhibit 99.1
- ImmunityBio, Inc. — current report (8-K) of May 18, 2026: supply agreement with Japan BCG Laboratory
- ImmunityBio, Inc. — current report (8-K) of July 30, 2026, Exhibit 99.1: authorization in the United Arab Emirates
- Ownership filing (Schedule 13D/A) by Patrick Soon-Shiong and affiliated entities of August 6, 2026
- Fundamental data (metrics, valuation, analyst consensus, quarterly series, prices); in-house stock scanner, data as of July 7, 2026.
Disclaimer: This article is a journalistic analysis and not investment advice. It is not a solicitation to buy or sell securities. Share prices fluctuate; a total loss is possible. Make your investment decisions on your own responsibility and seek independent advice when in doubt.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 0.9 | 0.2 | 0.6 | 14.7 | 113.3 |
| Operating Income (EBIT) | -330.3 | -351.3 | -362.3 | -344.2 | -256.0 |
| Net Income | -346.8 | -416.6 | -583.2 | -413.6 | -351.4 |
| Net Margin | -37,129.6% | -173,569.6% | -93,761.4% | -2,804.8% | -310.2% |
| Earnings Per Share | -0.89 $ | -1.04 $ | -1.15 $ | -0.59 $ | -0.38 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
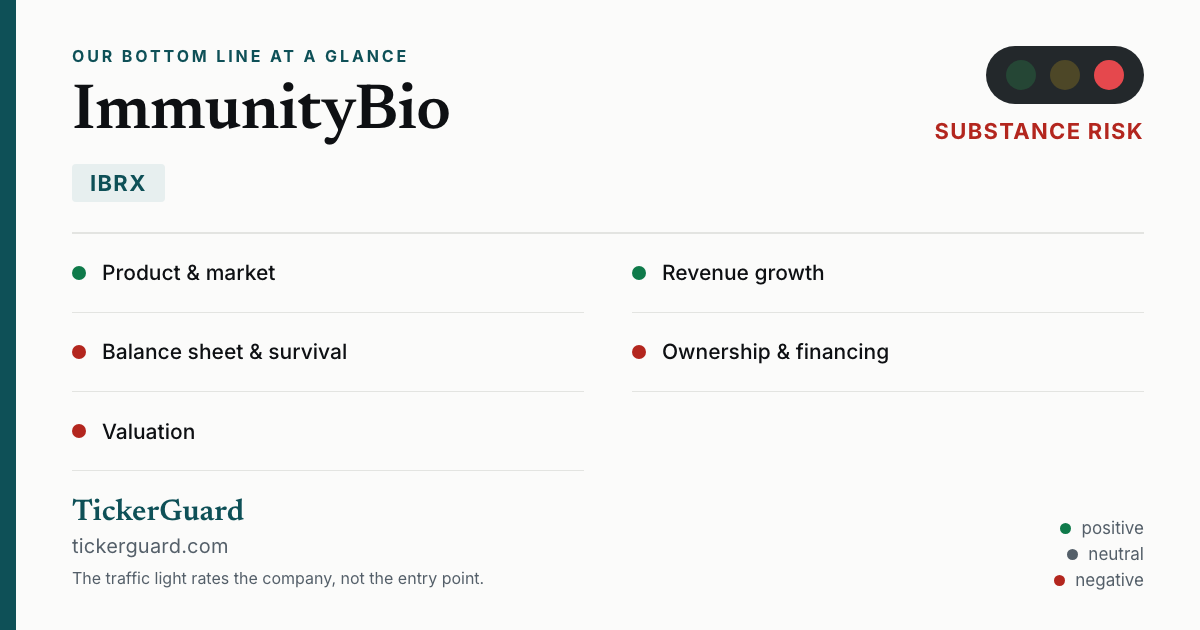
Our Bottom Line at a Glance
- Product & market positive
- ANKTIVA is FDA-approved and addresses a real need: bladder cancer is the sixth most common cancer in the United States, and the BCG shortage leaves many patients undertreated. A gross margin of roughly 99 percent; the FDA decides by January 6, 2027 on an expansion to papillary-only tumors.
- Revenue growth positive
- A genuine product ramp rather than an accounting effect: from $14.7 million (2024) to $113.3 million (2025, up 668 percent), and $50.7 million of ANKTIVA revenue in the second quarter of 2026 (up 92 percent) — according to the company the eighth straight quarter of sequential growth.
- Balance sheet & survival negative
- A going-concern warning also in the quarterly report as of June 30, 2026; $4.6 billion of accumulated losses, stockholders' equity of minus $1.05 billion, $141.9 million of operating cash outflow in the first half of 2026. The cash comes from equity and financing measures, not from the business.
- Ownership & financing negative
- Founder Soon-Shiong controls about 62 percent and is a lender at the same time ($480.0 million, convertible at $5.427). Ahead of him stands Oberland with a secured revenue interest ($415.1 million liability); ongoing dilution through the ATM program and warrants.
- Valuation negative
- Roughly $8.9 billion of market value (September 25, 2026) against about $166 million of revenue over four quarters = a price-to-sales ratio of a little over 50. Practically the entire value is future expectation; one-product risk and strong competition.
ImmunityBio is both things at once: a real growth story with an approved drug, and a fragile balance sheet propped up by a single billionaire. The second quarter of 2026 confirms the growth and shows a somewhat smaller cash outflow, but it changes nothing about the foundation: a going-concern warning, negative equity, two creditors ahead of shareholders and ongoing dilution. Not investment advice.
What Our Rating Means
Substance risk
We found at least one documented issue that threatens the company itself — regardless of how the stock is currently valued.
The existential findings carry the verdict: an explicit going-concern warning also in the quarterly report as of June 30, 2026, stockholders' equity of minus $1.05 billion and $141.9 million of operating cash outflow in the first half of 2026 — survival hangs on the funding promise of majority shareholder Soon-Shiong, who is a lender at the same time, and on a secured revenue interest. The genuine revenue growth changes nothing about that existential type. Only when the operating cash outflow falls markedly and the company manages without the founder's support and without constant capital raises can this be reassessed.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- ANKTIVA (N-803) has been approved in the United States since April 2024 (the early bladder cancer form NMIBC with carcinoma in situ); in the second quarter of 2026, $50.7 million of $51.2 million of revenue came from the U.S.
- The first-half 2026 net loss of $863.2 million is largely non-cash (remeasurement of warrants and of the convertible founder debt following the share price rally); the operating loss was $131.5 million.
- Very high short interest (roughly 31 percent of the free float, data as of September 27, 2026); in the twelve months through July 7, 2026, insiders bought no shares in the market and only sold (the loan conversion by the founder on March 31, 2026 is not a market purchase).
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of September 27, 2026. Stock Watch will tell you what's changed at IBRX since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Immunitybio Inc (IBRX), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
ImmunityBio is a biotech company from San Diego with one approved product: ANKTIVA, an immunotherapy against an early form of bladder cancer (FDA approval in April 2024). The compound activates the body's own killer and T cells and is given together with the BCG vaccine directly into the bladder. Alongside that, the company is working on a broader cancer immunotherapy pipeline.
ANKTIVA net product revenue rose to $50.7 million (up 92 percent year over year), the operating loss fell to $61.7 million and operating cash outflow to roughly $66.5 million. Cash and marketable securities stood at $357.4 million as of June 30, 2026. The going-concern warning remains in the quarterly report, and stockholders' equity is minus $1.05 billion.
Because both are true. Revenue grew 668 percent in 2025 to $113.3 million, which triggers the growth scanners. At the same time the company sits on the warning lists — the going-concern proxy, Altman-Z distress and the Beneish M-Score — because of $4.6 billion of accumulated losses (June 30, 2026), negative equity and an explicit going-concern warning. Growth and balance-sheet stress in a single stock.
The company itself writes of "substantial doubt" about its ability to continue as a going concern, most recently in the quarterly report as of June 30, 2026. That doubt counts as alleviated only because founder and billionaire Patrick Soon-Shiong has committed to keep supporting operations with money as required. In the near term that dampens the risk; over the longer run, survival depends on his willingness and on fresh capital.
The $863.2 million net loss in the first half of 2026 is largely non-cash. The operating loss was $131.5 million; the rest is mainly the remeasurement of warrants and of the convertible founder debt, which became more expensive because the share price rose. That costs no cash. The $141.9 million of operating cash outflow in the half year, however, is real.
Because the valuation is almost pure expectation: at roughly $8.9 billion of market value (September 25, 2026) against about $166 million of revenue over four quarters, the market is paying a little over 50 times revenue. Add to that ongoing dilution, two creditors ahead of shareholders and a one-product business facing strong competition.
Founder Dr. Patrick Soon-Shiong, a billionaire and the inventor of the cancer drug Abraxane, controls about 62 percent of the shares according to his ownership filing of August 6, 2026, and 64.8 percent including his conversion right; ImmunityBio therefore counts as a "controlled company". He is at the same time a lender: an entity affiliated with him holds a $480.0 million convertible loan (June 30, 2026), convertible at $5.427 per share.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.