Eli Lilly Stock: One Trillion Dollars, One Molecule — and the Government Now Sits at the Table
Eli Lilly remains the most valuable pharmaceutical company in the world: in the second quarter of 2026, revenue grew 48 percent to $23.0 billion, and 51 percent for the first half — Lilly raised its full-year guidance to as much as $87 billion. It is still carried by a single compound: tirzepatide (Mounjaro plus Zepbound) accounts for about 65 percent of revenue. New since our last analysis: an acquisition wave of four closed and at least one announced deal that pushed total debt up 29 percent to $54.9 billion within six months — and a look into five analyst earnings calls that shows where management promises held and where they did not. We read the latest quarterly report (10-Q as of 06/30/2026) and the accompanying earnings release. Not investment advice — just a look at how much weight a single domino can carry.
 Thomas Mücke
Founder & Publisher
As of Today
As of: September 17, 2026
- Closing price
- 1,152.40 $ +1.30%
- Market Capitalisation
- 1,027.6 $B
- P/E
- 44.4
- Growth Score
- 8/10
- AAQS
- 10/10
Price change since September 2, 2026: -0.7%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 714.60 $ to 1,280.30 $ · Last price: 1,152.40 $ (As of: September 17, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
There is a kind of stock at which the investor brain quietly switches off its inspection mode: the celebrated giant. A company that has existed for 150 years, whose products millions of people take and whose price has been climbing for years — an inner voice whispers: "You can't go wrong with one of these." Psychologists call this the halo effect: one radiant feature (size, success, fame) outshines everything you actually ought to check. Hardly any stock invites this reflex in 2026 as much as Eli Lilly (NYSE: LLY) — the pharmaceutical company from Indianapolis that the boom in weight-loss injections has turned into the first trillion-dollar pharma company in stock-market history. And this time even a serious tool nods along: our in-house stock scanner built on Joel Greenblatt's Magic Formula — a value filter that looks for good companies at fair prices, not a warning system — lists Lilly among its hits. So let's make a deal: before the halo effect decides for you, we read together what Lilly itself reported to the U.S. securities regulator, the SEC — in the annual report (10-K, the yearly mandatory filing) and the quarterly report (10-Q). Such filings are honest under penalty of law. And these particular ones contain three sentences about a single molecule, a negotiating government and a ticking patent clock that measure the halo rather precisely. In the end, you decide for yourself.
What Eli Lilly actually does
Eli Lilly was founded in Indianapolis in 1876 by the pharmacist and colonel Eli Lilly and for long stretches of the 20th century was above all one thing: the insulin company. Today the group employs about 50,000 people (roughly 12,000 of them in research) and sells medicines in about 90 countries — for diabetes and obesity, cancer (Verzenio), psoriasis (Taltz), migraine (Emgality) and Alzheimer's. So much for the portrait. Since 2022, though, the stock-market story has at its core consisted of a single word: tirzepatide. That is a so-called incretin — translated: a satiety-hormone mimic. The compound imitates two of the body's own messengers at once (GLP-1 and GIP) that signal "full" to the brain and regulate blood sugar. One molecule, two labels: as Mounjaro, tirzepatide is sold against type 2 diabetes; as Zepbound, against obesity. Sounds like marketing? It partly is — but behind it stands the biggest new drug market in decades, in which Lilly and its Danish rival Novo Nordisk share a de facto duopoly. And Lilly keeps adding to it: in April 2026 the U.S. drug regulator FDA approved Foundayo (orforglipron) — the first weight-loss pill of this class, which needs neither syringe nor refrigerator, and by its debut quarter it was already generating revenue of its own.
Note the central tension right away — it is the connecting thread of this analysis: Eli Lilly delivers the best growth in big pharma — but two thirds of it hang on a single molecule whose price is set less and less by the market and more and more at the negotiating table. A company town in which every second paycheck comes from a single factory can live splendidly. It just ought to know what happens when the factory coughs.
Company history for investors
-
2022
FDA approval of Mounjaro (tirzepatide) for type 2 diabetes
The start of the tirzepatide era, which would turn Lilly into the world's most valuable pharma company within a few years.
-
2023
FDA approval of Zepbound (tirzepatide) for obesity
The same molecule under a second brand name — the beginning of today's revenue concentration on a single compound.
-
2025
Voluntary pricing agreements with the U.S. government (November)
Lilly secures tariff grace and Medicare access in exchange for lower prices — the government becomes a co-negotiator.
-
2026
HHS selects Trulicity and Verzenio for government-set prices from 2028 (January)
First signal that government price-setting extends beyond Jardiance to further blockbusters.
-
2026
FDA approval of Foundayo, the first weight-loss pill (April)
Lilly's attempt to broaden the one-molecule cluster — already $98 million in revenue in its debut quarter.
-
2026
Four acquisitions in the second quarter, total debt up 29 percent within six months
Orna, Ajax, Centessa and Kelonia expand the pipeline — on credit: debt grows at a rare pace.
-
2026
AtaiBeckley acquisition announced, about $2.8 billion (disclosed by August 5)
The move into depression therapies shows how aggressively Lilly is now expanding its portfolio through deals rather than organically.
Where the stock shows up in our scanner
Every day we run about 3,500 stocks through our scanners. Eli Lilly last lit up in five filters in our evaluation (data as of July 8, 2026) — and not a single one of them is a warning scanner. The most interesting hit is the Magic Formula of value investor Joel Greenblatt. His idea in one sentence: buy above-average companies at a reasonable price — measured by return on capital (how much operating profit per dollar of working capital employed?) and earnings yield (how much operating profit per dollar of enterprise value?). Lilly qualifies via the quality track: the EBIT margin has historically run around 49 percent, the return on equity is in the triple digits. Added to that are hits in the Levermann ranking, in "Martin Zweig: growth with reason", in the EBIT-margin ranking and in the "Altman-Z: balance-sheet fortress" (our live check on July 14, 2026 additionally brought up dividend and growth scanners). The individual grades, translated: the Piotroski F-Score, a nine-point test of balance-sheet quality, stands at 8 of 9 — genuinely good, a thoroughly healthy company. The Altman-Z score, a classic early warning of insolvency, sits at a relaxed about 7.3 (it gets critical below 1.1). The fundamental rating stands at A. In short: the scanner sees a model student. What a scanner cannot see: where the shiny numbers come from — and how many eggs sit in one basket for them.
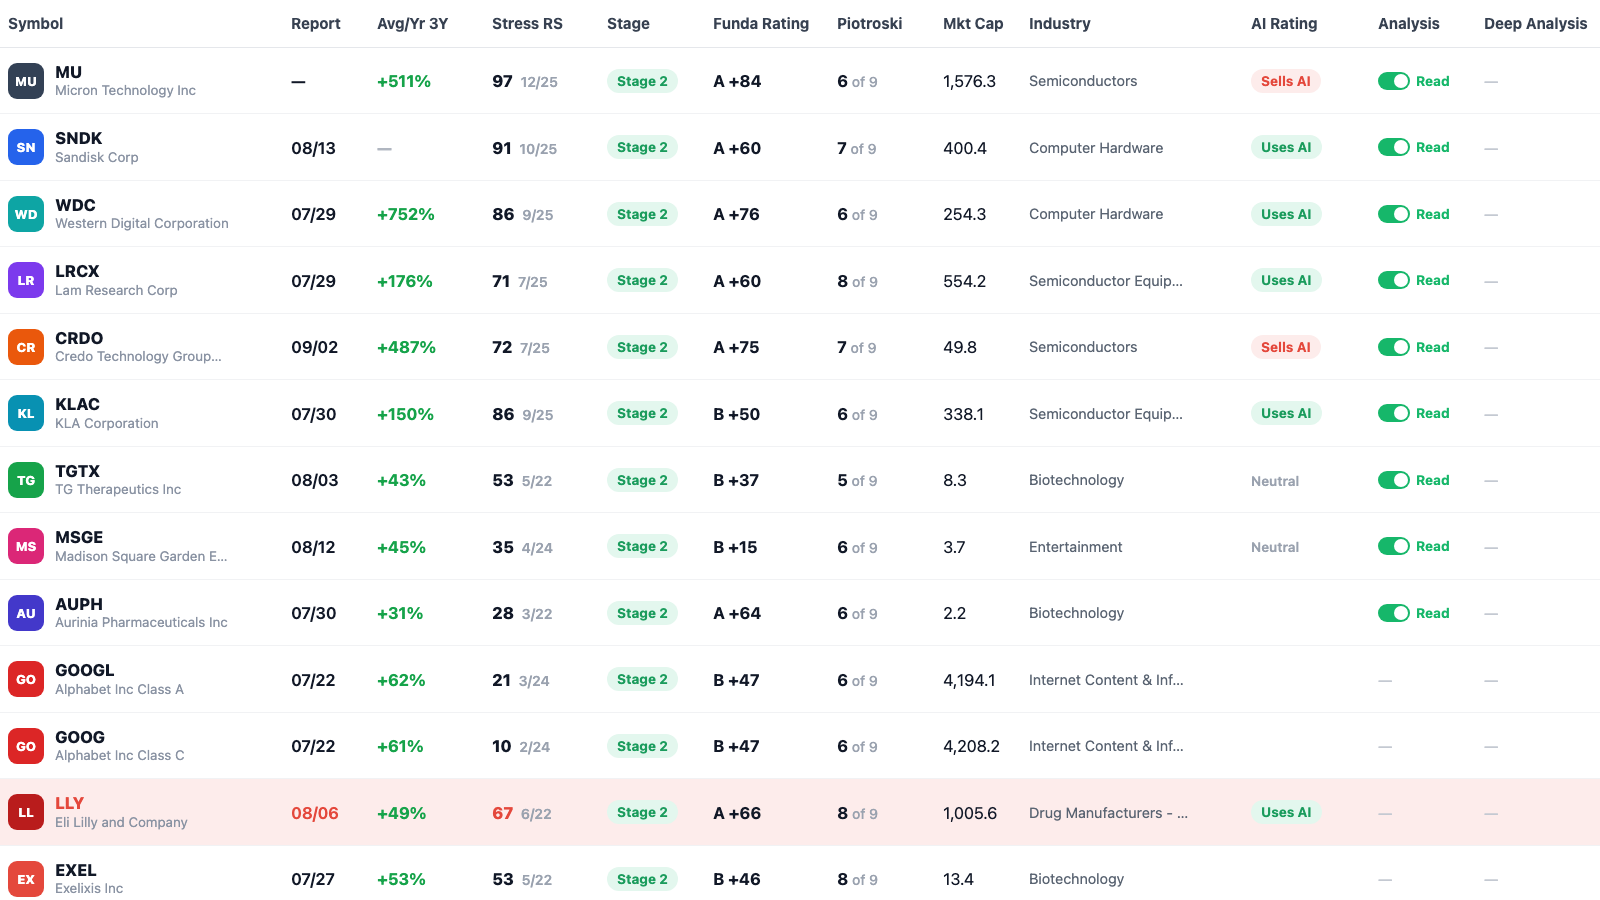
One footnote for context: unlike the memory-chip cyclical Micron, which the same formula currently catches at its earnings peak, Lilly is no cyclical — demand for medicines does not swing with the business cycle. The Greenblatt weakness looks different here: the formula measures today's earning power and knows nothing of patent calendars, price negotiations and concentration risks. That is exactly what the mandatory filings are for.
The numbers over the years — honestly appraised
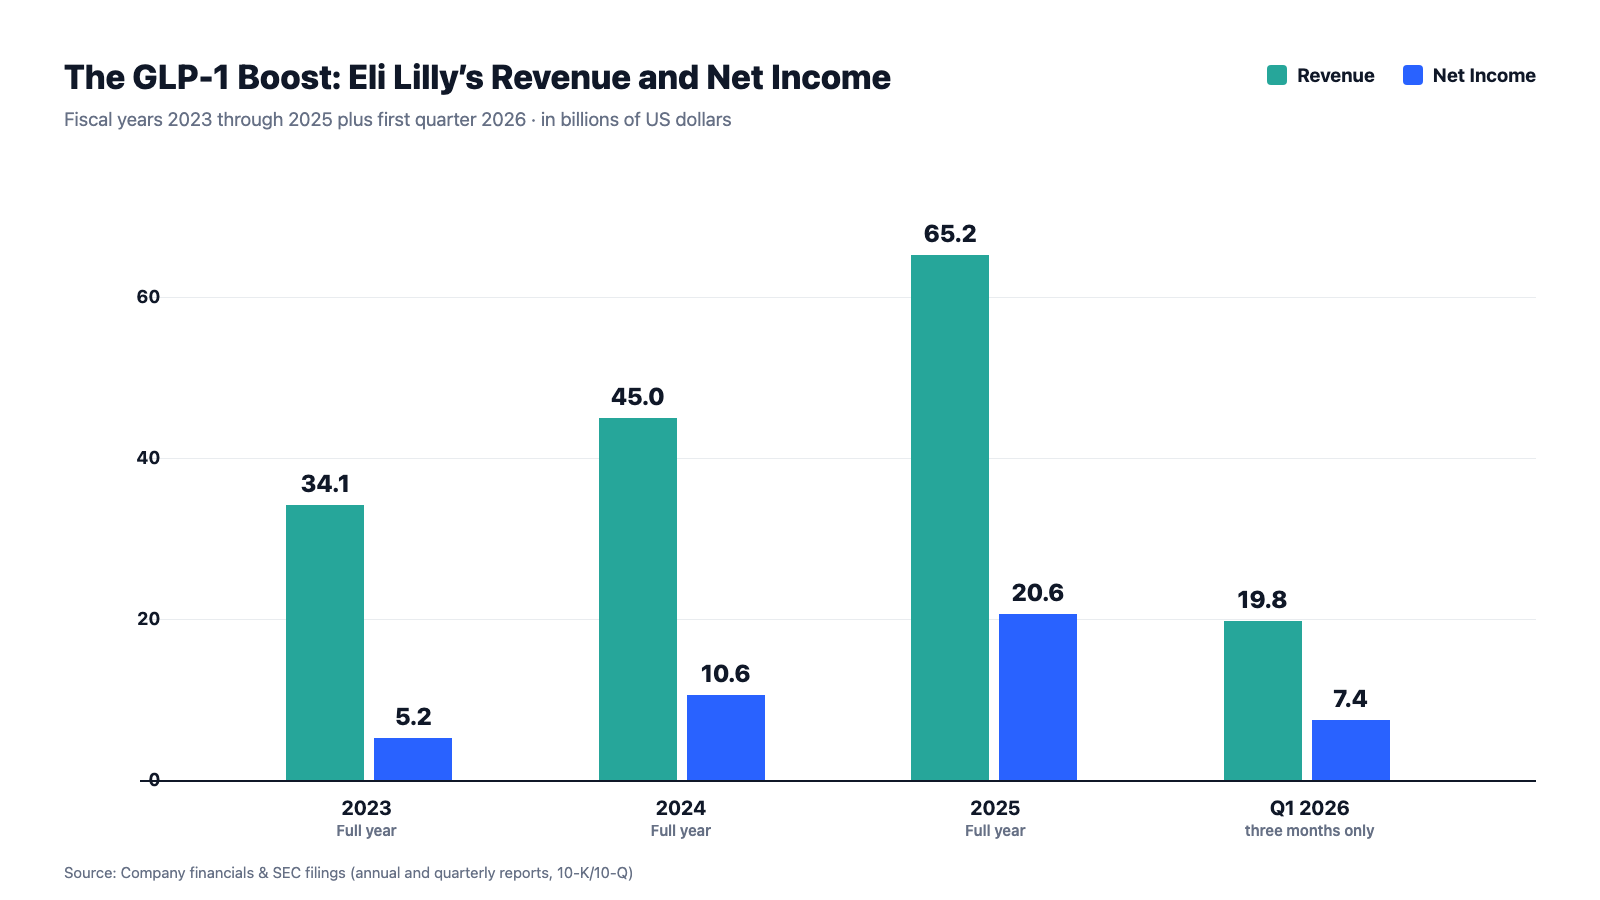
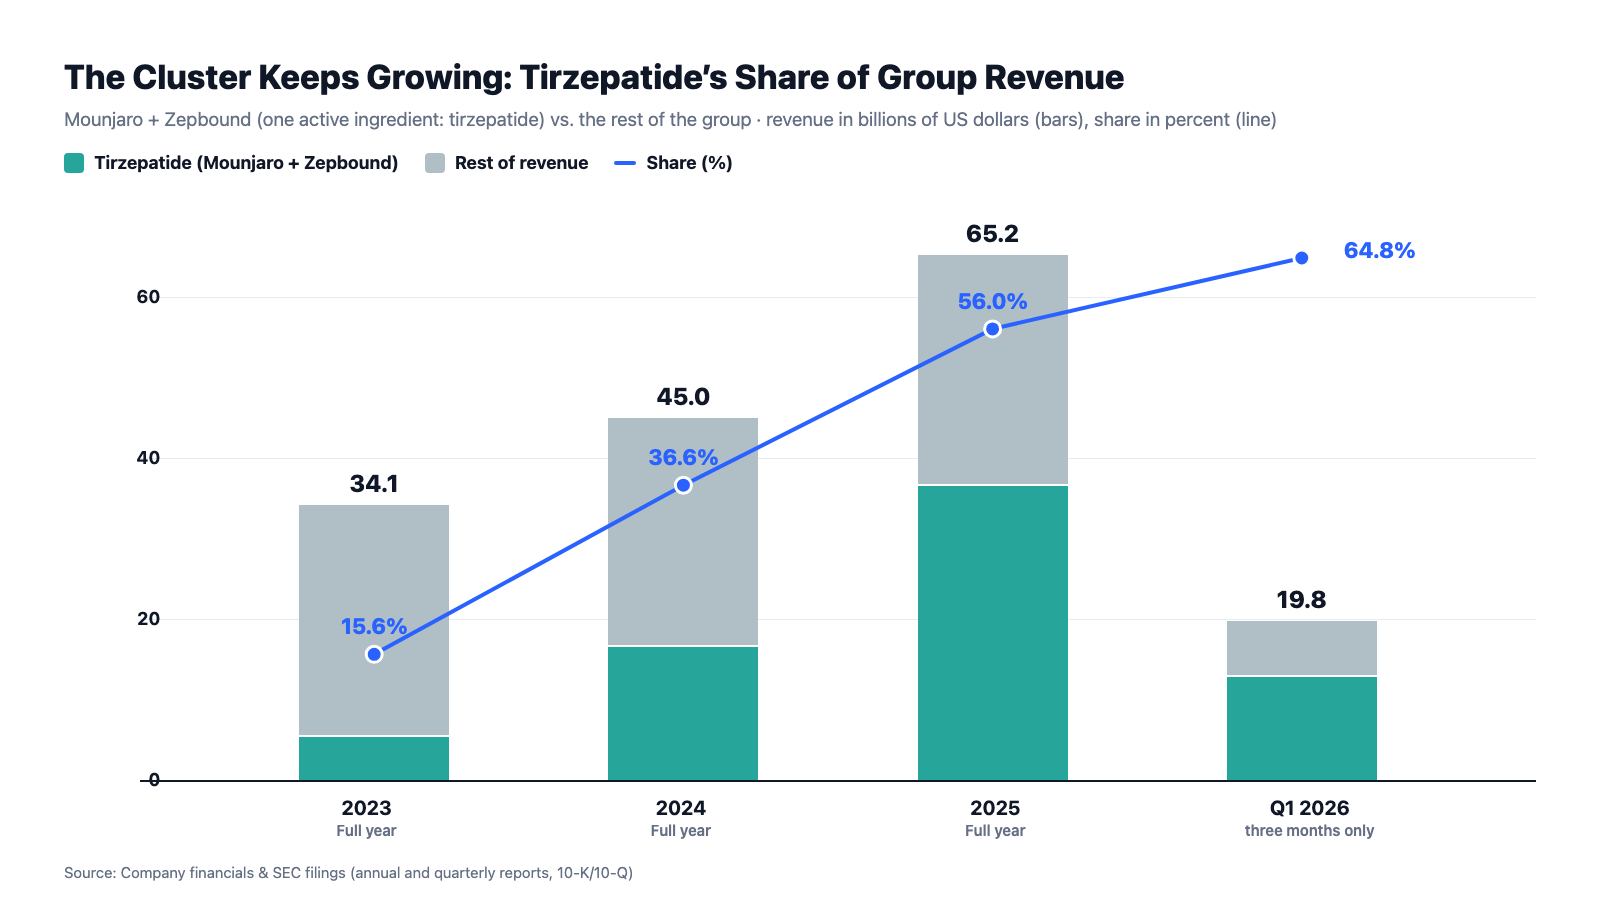
First, what genuinely impresses — and at Lilly that is a lot. Group revenue jumped from $34.1 billion (2023) via $45.0 billion (2024, plus 32 percent) to $65.2 billion (2025, plus 45 percent). Net income quadrupled in two years: from $5.2 via $10.6 to $20.6 billion (plus 95 percent in 2025). And the pace holds into the current year: in the second quarter of 2026 revenue grew 48 percent to $23.0 billion, and 51 percent for the first half of 2026 to $42.8 billion — net income for the first half rose 72 percent to $14.5 billion, earnings per share from $9.35 to $16.19. The gross margin stood at 86 percent in the second quarter of 2026, higher still than in the record year 2025 (83 percent). For a company of this size, such growth rates are simply extraordinary — for perspective: in 2026 Lilly continues to grow, in percentage terms, roughly as fast as many a start-up, only from a $65 billion base. Whoever hears only bubble talk here is not doing the numbers justice.
The use of the windfall is presentable too: in 2025, $13.3 billion flowed into research (plus 21 percent), $7.8 billion into new plants, $4.1 billion into share buybacks and $5.4 billion into dividends; the quarterly dividend was raised to $1.73 at the start of 2026 (plus 15 percent) and stayed there through the second quarter. The flip side is in the balance sheet as well, and it grew markedly larger this year: total debt jumped within six months from $42.5 billion (12/31/2025) to $54.9 billion (06/30/2026) — a 29 percent increase, largely financed through a $9.0 billion bond issued in May 2026 and driven by a series of corporate acquisitions (more on that in the second uncomfortable truth). Cash ($8.95 billion) plus other investments and equity stakes ($3.9 billion per the 10-Q's MD&A) totaled about $12.9 billion as of 06/30/2026. Growth, factories, acquisitions, buybacks and a dividend all at once — even at Lilly, that only works with markedly more borrowed money than a year ago. It remains solid nonetheless: equity grew over the same half-year from $26.5 to $33.9 billion, and the Altman-Z score still stands at about 7.3. The filings pose the exciting questions elsewhere.
What the filings say — the uncomfortable truths
Uncomfortable truth no. 1: two brands, one molecule — about 65 percent of revenue hangs on tirzepatide
Mounjaro and Zepbound sound like two legs to stand on. Chemically they are the same leg. The annual report makes no secret of it — it lists the concentration itself as a risk factor:
"We derived direct product and/or collaboration and other revenues of more than $3 billion for each of Mounjaro, Zepbound, Verzenio, Trulicity, Taltz, and Jardiance (including Glyxambi, Synjardy, and Trijardy XR) that collectively accounted for 82 percent of our total revenues in 2025. In particular, Mounjaro and Zepbound accounted for 56 percent of our total revenues in 2025, and we expect cardiometabolic health products will continue to represent a significant and growing portion of our business, revenues, and prospects."
— Eli Lilly, SEC annual report 10-K 2025, Item 1A "Risk Factors"
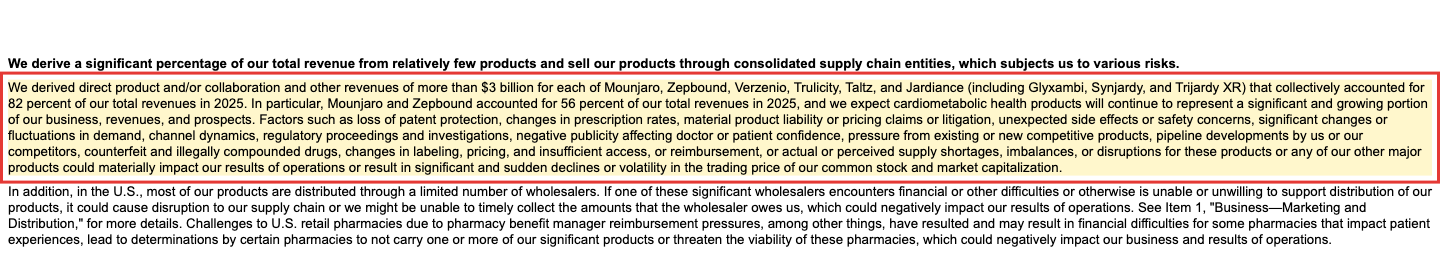
And the concentration has stayed high and stable: in the latest quarterly report, Mounjaro and Zepbound together account for about 65 percent of group revenue (three months through June 30, 2026: Mounjaro $9.9 billion, plus 91 percent; Zepbound $4.9 billion, plus 46 percent) — practically unchanged from the 65 percent in the first quarter, but far above the 56 percent for full-year 2025. You may know customer concentration from small companies — at our Greenblatt neighbor TG Therapeutics, 98 percent hangs on one drug. But a trillion-dollar company whose valuation exceeds Novo Nordisk, Pfizer, Merck and AstraZeneca combined, hanging by two thirds on one compound — that is historically fairly unique. In fairness: the cluster is not one customer but a world market with billions of potential patients, and Lilly is actively broadening it — in the second quarter of 2026, Foundayo became a third product of the same compound class with revenue of its own ($98 million, from a standing start). Still: every piece of news about tirzepatide — a side-effect study, a rival product, a pricing decision — continues to move two thirds of the business. The company's own report names the possible consequence: "significant and sudden declines or volatility" of the stock price and market value.
Uncomfortable truth no. 2: the government still sits at the price tag — and the promised price relief is now guided down explicitly
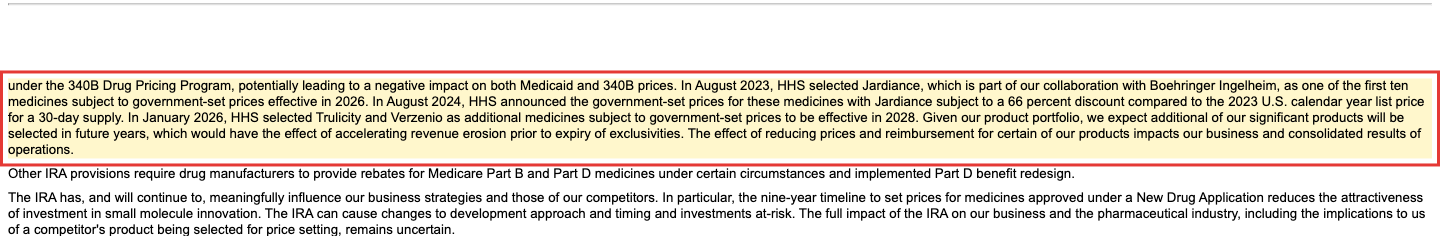
To investors, American drug prices long counted as a nature preserve. That is over. Since the Inflation Reduction Act (IRA) of 2022, the U.S. Department of Health and Human Services (HHS) may effectively set prices for high-revenue Medicare drugs — for pills as early as nine years after approval, for biologics after thirteen. Lilly has already experienced what that means in practice: for Jardiance, a government-set price has applied since 2026 — 66 percent below the 2023 list price. And the calendar keeps filling up, unchanged from what Lilly disclosed in the annual report: Trulicity and Verzenio follow in 2028, and Lilly "expects additional of our significant products will be selected in future years" — language the second-quarter 10-Q repeats without material change. On top comes a second channel that is now live: in November 2025 Lilly concluded voluntary agreements with the U.S. government, finalized in the first quarter of 2026 — lower Medicaid prices, more balanced pricing across developed markets for new medicines, discounted Lilly weight-loss drugs for Medicare beneficiaries, a government direct-purchase platform with substantial discounts to list prices, and in return three years of grace from possible pharma tariffs. The "Medicare GLP-1 Bridge Program" actually launched on July 1, 2026: 20 million additional Americans have since had access to weight-loss drugs at a $50 monthly out-of-pocket cost — a "35 percent" bigger pool of people with access to Lilly's obesity medicines, per management. The early weeks show a clear preference for the injectable (about 80 percent of Bridge patients choose an injectable over an oral) and about 60 to 70 percent new, previously untreated patients — more volume, but also more people at the discounted price.
You can read the government agreement as smart peacekeeping: Lilly buys itself predictability and at the same time opens the huge Medicare market for Zepbound. But you must also see the direction: this company's prices, rebates and even tariffs increasingly come into being in negotiations with governments. For the Magic Formula that is invisible — it measures yesterday's margins, not tomorrow's bargaining power. And the IRA has one more punchline: for pills, government price-setting kicks in after just nine years. Of all products, Foundayo — the new weight-loss pill and Lilly's most important bet on the future — falls under this shorter deadline; the company's own report dryly notes that the nine-year rule diminishes the appeal of investing in small molecules.
Uncomfortable truth no. 3: the patent clock — Trulicity shows live that a cliff is rarely a straight line, and a new legal fight looms over the next blockbuster
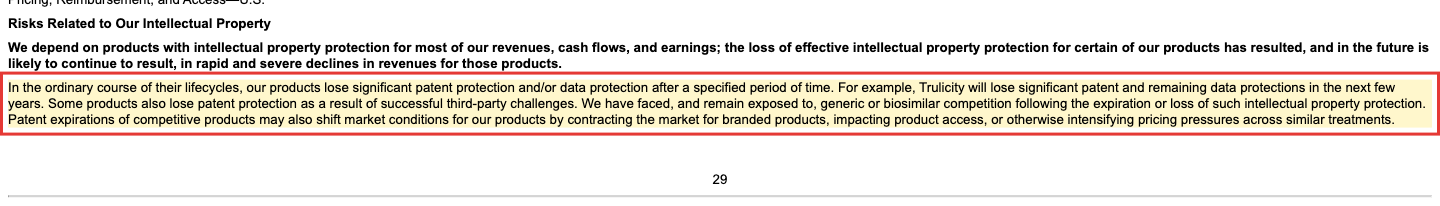
Pharma business models have a built-in expiration date: when patent and data protection end, the branded product turns into a commodity overnight — generic and biosimilar makers copy legally, prices collapse. The annual report says so with a candor you have to credit — right under the heading stating that the loss of protections has led to rapid and severe revenue declines in the past and is expected to keep doing so:
"In the ordinary course of their lifecycles, our products lose significant patent protection and/or data protection after a specified period of time. For example, Trulicity will lose significant patent and remaining data protections in the next few years."
— Eli Lilly, SEC annual report 10-K 2025, Item 1A "Risk Factors — Risks Related to Our Intellectual Property"
You can watch what that feels like live in the same filings: Trulicity, Lilly's GLP-1 predecessor, still brought in $7.1 billion in 2023, only $4.3 billion in 2025 — in the first quarter of 2026, revenue fell another 16 percent. Yet the path is no straight collapse: in the second quarter of 2026, Trulicity revenue unexpectedly rose again, 12 percent to $1.2 billion (helped by a favorable rebate-estimate adjustment), so that the first half of 2026 is only 2 percent below the prior year. That changes nothing about the structural trend — the U.S. compound patent expires in 2027 per the report, and HHS has selected the product for government price-setting from 2028: cliff and price cap at once — but it shows that a patent cliff is rarely a straight line, more a zigzag of rebate adjustments, residual demand and base effects. At the crown jewel tirzepatide, the calendar looks friendlier — compound patent in the United States until 2036, Europe 2037, Japan 2040. But one line in the patent table deserves attention: U.S. data exclusivity for tirzepatide ends as early as 2027. That does not open the generics floodgates immediately (the compound patent remains), but it lets imitators base their approval applications on Lilly's trial data. A related fight is now playing out over the next big hope, the triple agonist retatrutide: Lilly wants it approved as a biologic ("BLA"), which would mean twelve years of data exclusivity instead of the five years typical for small molecules. Per CEO David Ricks on the August 5, 2026 earnings call, the FDA disagrees; the matter is "active litigation" and unresolved, while Lilly prepares a filing for early 2027. Outcome open — but a live example of how much of Lilly's future patent protection depends on interpretation questions decided in court, not in the lab.
Uncomfortable truth no. 4: copies, gatekeepers and the rebate scissors — and management now guides the scissors to widen further
The fourth truth is about everything that happens between the prescription pad and Lilly's account. First: the copies. During the tirzepatide shortage of 2022 through 2024, U.S. compounding pharmacies were legally allowed to sell remixed versions — the emergency backdoor became a barn door through which a gray billion-dollar market emerged. The shortage has been officially over since late 2024 per the FDA, mass production prohibited. But the latest quarterly report, filed as of 06/30/2026, repeats the same finding word for word — Lilly "continues to see" counterfeit and mass-compounded incretins, a persistent state, not a one-off episode:
"We continue to see the production, marketing, and sale of counterfeit, misbranded, adulterated, and mass-compounded incretins. These practices may impact patient safety and undermine regulatory drug approval processes. While the FDA confirmed in late 2024 that the previous shortage of tirzepatide had ended and that compounding pharmacies are required to cease mass production, we cannot guarantee adequate regulation or compliance."
— Eli Lilly, SEC quarterly report 10-Q as of June 30, 2026, Item 2 MD&A "Executive Overview — Incretin Medicines"
Second: the gatekeepers. Between Lilly and patients in the United States stand pharmacy benefit managers (PBMs) — the insurers' rebate negotiators who decide which drug makes the preferred list (the "formulary"). How much power that is showed in the case of CVS Caremark: the biggest of these gatekeepers removed Zepbound as a preferred weight-loss drug on many insurance plans in July 2025 — in favor of the rival product. The consequence, as CFO Lucas Montarce put it bluntly on the August 5, 2026 earnings call: patients without formulary access flowed through a "medical exception" channel where Lilly sold at close to an undiscounted price — artificially inflating the reported net price per Zepbound prescription. Zepbound is set to return to CVS formularies starting in the fourth quarter of 2026, per company guidance; Montarce explicitly guided falling net prices for the following quarters once that exception channel goes away. Third: the rebate scissors. Between list price and actual proceeds lies an entire rebate system in the United States — the related balance-sheet liability, "Sales rebates and discounts", grew from $17.4 billion (12/31/2025) to $21.1 billion (06/30/2026). Realized prices per unit are falling measurably: in the second quarter of 2026, U.S. revenue rose 33 percent against a reported price decline of 3 percent — excluding the favorable rebate-estimate adjustment, U.S. price would have fallen 9 percent per the CFO. Internationally the gap is even bigger: realized prices there fell 36 percent in the second quarter, mainly because Mounjaro was added to China's national reimbursement list, the NRDL. And on the margins run the product-liability mass proceedings: multidistrict litigations (MDLs) over alleged gastrointestinal and optic-nerve injuries from incretins are collecting lawsuits against Lilly and Novo Nordisk — at a company that is largely self-insured for liability cases, as the report notes. Remember: Lilly's boom is a volume boom at falling net prices — and per management's own account, the price side of that equation is set to get less attractive in coming quarters, not better.
What the analyst calls reveal — promises and reality
Mandatory filings are honest under penalty of law — but they are also finished, lawyer-polished prose, months in the making. The analyst earnings calls after every quarterly report are the opposite: live, unedited, and in the Q&A executives must answer questions they did not choose themselves. We read five of these transcripts — the last five quarters, Q2 2025 through Q2 2026 — watching for one thing above all: what did management promise, and did it come true?
The Foundayo launch trailed its own timetable — and only caught up visibly late in the quarter. In late April 2026, shortly after the U.S. launch of the weight-loss pill Foundayo, analysts framed the expectation that the launch would "accelerate" in the second half — a reading management did not push back on, pointing instead to upcoming catalysts (mid-May PBM access, the July Medicare start). In the August call, an analyst asked bluntly whether the launch had run "somewhat slower than anticipated":
"In the U.S., the launch curve has been somewhat slower than anticipated. Just curious as to what you think the contributing factors are there and when you think we could expect an inflection?"
— Analyst Asad Haider (Goldman Sachs), Eli Lilly Q2 2026 earnings call, August 5, 2026
Ilya Yuffa, President of Lilly USA, gave an answer that implicitly confirmed the delay rather than disputing it: only "the last week of July" did prescribed volume nearly double from the month before, and the number of Foundayo prescribers rose from 8,000 (as of the April call) to 36,000. That is genuine progress — but it arrived late in the quarter, not evenly spread across it, as the original "acceleration in the second half" framing suggested. CEO David Ricks himself chose this line in his prepared remarks: "We're pleased with our progress this year so far, but we're not satisfied." An understatement that says more between the lines than any single metric.
The net-price question was asked twice in a row — and the answer shifted from defense to forward guidance. Back in the April call, an analyst calculated that Zepbound was netting about $580 per prescription, well above Lilly's own cash-pay price of about $450. The explanation then: a "medical exception" channel without a discount, triggered by CVS Caremark's July 2025 removal of Zepbound from preferred lists. In the August call the same math came up again — this time also benchmarked against rival Wegovy (about $380 net per prescription) — and this time CFO Lucas Montarce did not just explain, he guided forward: once CVS access returns in the fourth quarter of 2026, the net price will fall. For investors who infer sustainable margin from today's elevated net prices, that is an important correction straight from the source: part of today's price level is a transitional effect, not a permanent state.
The "raised" full-year guidance contains a growth brake in the fine print. At first glance, the August guidance increase sounds unambiguously positive: $2 billion more revenue at the top of the range. Yet one analyst calculated that the implied second-half growth rate is lower than the first half's — despite Medicare Bridge tailwinds and the Foundayo ramp. Montarce's answer named the reason openly: one-time rebate-estimate adjustments from the first two quarters of 2026 are not expected to repeat in the second half, plus the base effect of Mounjaro's prior-year country launches. Translated: part of 2026's record growth so far was not repeatable — not dramatic news, but a detail that gets lost in the guidance-raise headline.
The acquisition wave is sold as discipline — the balance sheet shows speed. Asked whether Lilly's sudden deals in psychiatry (AtaiBeckley) and vaccines (Curevo, LimmaTech, Vaccine Company) mean leaving its core business, business-development chief Jake Van Naarden answered that Lilly remains "disciplined" and buys only at prices that create long-term value. That may well be true — but "disciplined" and "fast" are not mutually exclusive here: four acquisitions closed in the second quarter of 2026 alone, more than in some entire prior years, financed with fresh debt. The language on the calls describes selectivity and value; the balance sheet describes pace and leverage. Both can be true at once.
What these five transcripts show overall: Lilly's management largely delivers what it promises — growth, approvals, pipeline progress — but the details in its answers to uncomfortable analyst questions are more honest and more cautious than the headlines of the prepared remarks. Whoever reads only the first page of the earnings release misses exactly the nuances that surface in the Q&A.
Valuation: one trillion dollars — what you pay for is the decade, not the year
In early September 2026, Eli Lilly stock cost about $1,160; that makes a market value of about $1,035 billion — still the only trillion-dollar valuation in pharma history (all valuation figures: data as of September 2, 2026). For that you get, as of today: a price-to-earnings ratio of about 45, a price-to-sales ratio of about 13, a price-to-book ratio of about 31 and an enterprise value of about 29 times EBITDA. For perspective: classic pharma giants such as Pfizer or Merck traditionally trade at 10 to 15 times earnings — Lilly is priced more like a software growth stock. The optimists' counter-calculation: 31 analysts see the stock mostly as a buy (18 "strong buy", 6 "buy", 5 "hold", 2 sell-oriented), with the average price target about 15 percent above the current price. If profit grows as Lilly itself now guides for 2026 (adjusted earnings per share of $35.50 to $36.50), the price-to-earnings ratio on the company's own guidance already falls to about 32 — and to about 26 if the profit jump analysts expect on average for 2027 materializes. And exactly there lies the core: what is paid for is not the current record year but a whole decade of continued success — Foundayo must become a blockbuster, retatrutide and company must deliver, the newly acquired pipeline projects must pay for themselves, and neither price regulators nor copies nor the duopoly rival may crash the party. The dividend yield of about 0.6 percent ($6.92 annual rate) is, at this price, more symbol than argument. Still: unlike many a high-flyer, real, growing cash flows stand behind this. It is not a house of cards. It is a very solid house with a very athletic price tag, and markedly more borrowed capital on the foundation than a year ago.
Opportunities and risks at a glance
What speaks for Eli Lilly:
- A duopoly in the biggest new drug market in decades: tirzepatide keeps growing at strong double-digit rates (Mounjaro +91 percent, Zepbound +46 percent in Q2 2026), Mounjaro has been launched in all major international markets, and the Medicare Bridge program has been live since July 1, 2026, opening another mass market (10-Q as of 06/30/2026).
- The pipeline delivers: Foundayo (orforglipron) already generated $98 million in revenue in its debut quarter and is under regulatory review in over 40 countries; retatrutide has the complete data package for approval after three more successful Phase 3 trials and is set to be filed in early 2027 (earnings release and earnings call, August 5, 2026).
- Outstanding metric quality: 86 percent gross margin in Q2 2026, operating profit (EBIT) about 31 percent higher than the prior-year quarter, Piotroski 8 of 9, Altman-Z about 7.3, fundamental rating A — the Greenblatt hit comes from real earning power, not a balance-sheet trick (data as of July 8, 2026 resp. Q2 figures August 5, 2026).
- Shareholder-friendly capital allocation from a position of strength: $1.5 billion in dividends and $1.6 billion in share buybacks in the second quarter of 2026 alone, the dividend still at $1.73 per quarter (earnings release August 5, 2026).
- The November 2025 government agreement creates predictability: the Medicare Bridge program actually launched on July 1, 2026, three years of tariff grace in exchange for U.S. investment commitments — Lilly has contractually secured its political peace (10-K 2025; 10-Q as of 06/30/2026).
What speaks against it:
- Extreme concentration persists: Mounjaro + Zepbound = one molecule = about 65 percent of revenue in the second quarter of 2026, practically unchanged since the start of the year — the company's own risk factor warns of "significant and sudden" stock-price declines on bad news (10-K 2025; 10-Q as of 06/30/2026).
- Prices increasingly come into being politically, and management now confirms on the calls that net prices will keep falling: Jardiance at a government-set price (minus 66 percent), Trulicity and Verzenio from 2028, more products per Lilly "expected"; on top, the CFO guided falling Zepbound net prices once the CVS formulary return in the fourth quarter of 2026 ends today's exception channel.
- Patent, classification and copy risks: tirzepatide's U.S. data exclusivity ends in 2027; whether the successor drug retatrutide is classified as a biologic (twelve years of exclusivity) or a small molecule (five years) is, per management, "active litigation" with an unresolved outcome; mass-compounded incretins remain, per the latest 10-Q, an unchanged nuisance.
- Fast-growing debt from an acquisition wave: four closed deals (Orna, Ajax, Centessa, Kelonia) plus the announced AtaiBeckley acquisition (about $2.8 billion) pushed total debt up 29 percent to $54.9 billion within six months; the related one-off charges already shaved $3.03 per share off the raised 2026 earnings guidance (10-Q as of 06/30/2026).
- A demanding valuation: price-to-earnings ratio about 45, price-to-book about 31, market value about $1,035 billion (data as of September 2, 2026) — what is being paid for is a decade of continued success, while product-liability mass lawsuits (the incretin MDLs) run with no meaningful insurance cover.
A human conclusion
Back to the halo effect. The treacherous thing about it: it is usually right — until the one time it is expensively wrong. Six weeks after our last analysis, Eli Lilly remains an extraordinary company: the fastest growth in big pharma, a research machine with complete approval packages for not one but two new blockbuster candidates, balance-sheet grades straight from the textbook. The Greenblatt scanner made no mistake here. But the halo still carries the same documented dents — and a new one has joined them. Two thirds of the business still hang on one molecule. The industry's most important customer — the government — still sits at the price tag, and on the analyst calls management now confirms itself that net prices will fall. The patent clock keeps ticking, with a new unknown: whether retatrutide even gets the twelve-year biologic protection is now being decided by a court, not a lab. And new is the pace at which Lilly is buying growth rather than just earning it — 29 percent more debt within six months is no alarm bell given this balance-sheet strength, but it is a shift worth watching. Whoever holds or buys the stock is not betting on a house of cards but on the opposite: that an excellently run company broadens its cluster faster than politics, patents, copies and its own acquisition bill can weigh it down. That can work out very well. It is just a bet — not a certainty, even if the halo effect makes it feel like one. The filings and the earnings calls hand you both halves of the truth; which one you give more weight is your decision. And that is exactly as it should be.
Sources
All original documents used in this analysis — for your own reading:
- Eli Lilly and Company — SEC quarterly report 10-Q as of June 30, 2026 (filed August 5, 2026, the latest periodic filing)
- Eli Lilly and Company — Second-quarter 2026 earnings release, Exhibit 99.1 to the 8-K dated August 5, 2026
- Eli Lilly and Company — SEC annual report 10-K for fiscal year 2025 (filed February 12, 2026)
- Eli Lilly and Company — SEC annual report 10-K for fiscal year 2024 (filed February 19, 2025)
- Eli Lilly and Company — SEC quarterly report 10-Q as of March 31, 2026 (filed April 30, 2026)
- Eli Lilly and Company — SEC quarterly report 10-Q as of September 30, 2025 (filed October 30, 2025)
- Eli Lilly and Company — SEC quarterly report 10-Q as of June 30, 2025 (filed August 7, 2025)
- Complete SEC filing history of Eli Lilly: EDGAR overview (sec.gov)
- Five analyst earnings-call transcripts (Q2 2025 through Q2 2026) for the chapter "What the analyst calls reveal".
- Fundamental data (metrics, valuation, analyst consensus; data as of September 2, 2026), reconciled with the SEC filings.
- Screener and rating data: in-house stock scanner (data as of July 8, 2026; scanner membership checked live on July 14, 2026).
Transparency & disclaimer: This analysis is a journalistic contextualization of publicly available information and is not investment advice, not a financial analysis in the regulatory sense and not a solicitation to buy or sell securities. Stock investments involve substantial risks up to total loss. All information without guarantee; the data cut-off is noted in the text. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this deep dive.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 28,318.4 | 28,541.4 | 34,124.1 | 45,042.7 | 65,179.0 |
| Operating Income (EBIT) | 7,933.0 | 8,653.3 | 10,787.3 | 17,501.7 | 29,696.0 |
| Net Income | 5,581.7 | 6,244.8 | 5,240.4 | 10,590.0 | 20,638.3 |
| Net Margin | 19.7% | 21.9% | 15.4% | 23.5% | 31.7% |
| Earnings Per Share | 5.85 $ | 6.57 $ | 5.80 $ | 11.71 $ | 22.98 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
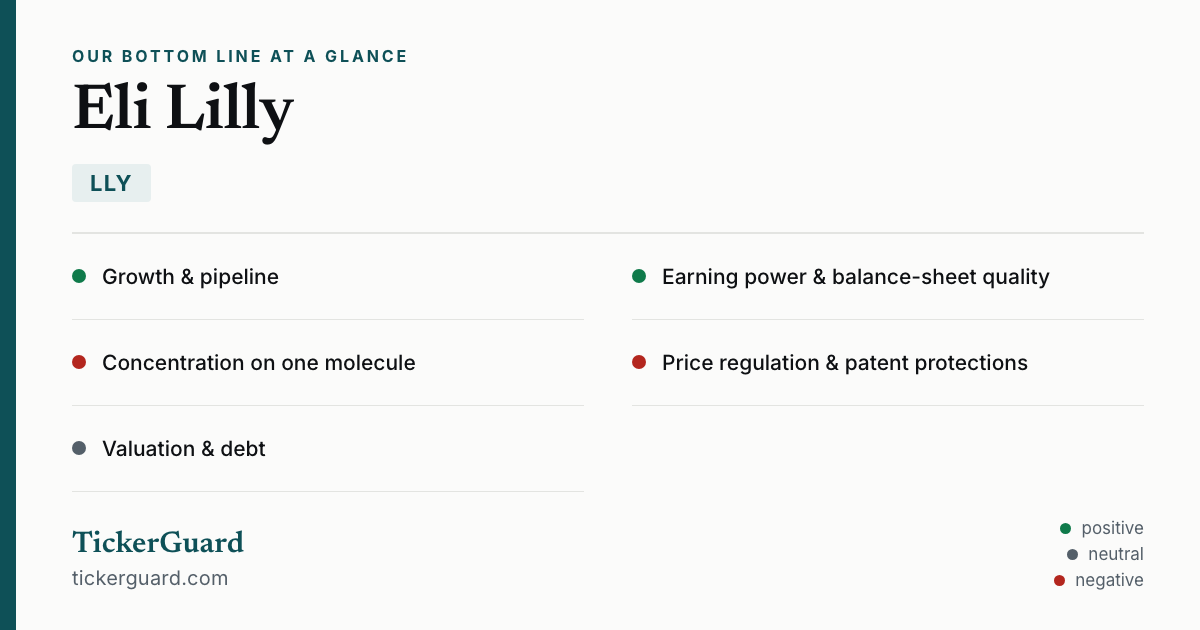
Our Bottom Line at a Glance
- Growth & pipeline positive
- Revenue plus 48 percent in Q2 2026, plus 51 percent for the first half — the fastest growth in big pharma continues. The pipeline delivers: Foundayo (the first weight-loss pill) generated $98 million in revenue in its debut quarter, retatrutide has the complete data package for approval in early 2027 after three more Phase 3 successes (earnings release August 5, 2026).
- Earning power & balance-sheet quality positive
- 86 percent gross margin in Q2 2026 (higher than in record-year 2025), Piotroski 8 of 9, Altman-Z about 7.3, fundamental rating A — the value-scanner hit rests on real earning power, and equity grew from $26.5 to $33.9 billion within six months (data as of July 8, 2026 resp. 10-Q as of 06/30/2026).
- Concentration on one molecule negative
- Mounjaro and Zepbound are the same compound (tirzepatide) and stood for about 65 percent of revenue in Q2 2026, unchanged — stable at a high level since the start of the year. The company's own risk factor warns of "significant and sudden" stock-price declines on bad news about these products (10-K 2025; 10-Q as of 06/30/2026).
- Price regulation & patent protections negative
- Government-set prices hit Jardiance since 2026 (minus 66 percent), Trulicity and Verzenio from 2028 — more products expected per Lilly. On the analyst calls, management confirmed falling Zepbound net prices from the fourth quarter of 2026; the retatrutide classification (biologic vs. small molecule, and thus its exclusivity length) is, per management, "active litigation" with an unresolved outcome.
- Valuation & debt neutral
- About $1,035 billion in market value, P/E about 45, P/B about 31 (data as of September 2, 2026) — on Lilly's own 2026 guidance the P/E falls to about 32. An acquisition wave (Orna, Ajax, Centessa, Kelonia; AtaiBeckley announced) pushed total debt up 29 percent to $54.9 billion within six months; the dividend (yield ~0.6 percent) and buybacks continue in parallel.
Eli Lilly is the rare case in which the halo effect is almost right: the best growth in big pharma, outstanding margins, a delivering pipeline and balance-sheet grades straight from the textbook. But the trillion-dollar valuation prices in a decade of continued success — and the company's own mandatory filings plus five reviewed analyst earnings calls document the same structural dents as before, with a new one added: 65 percent of revenue still hangs on a single molecule, the government sets prices and management now itself confirms falling net prices, and an acquisition wave pushed debt up 29 percent within six months. Quality is not the question here; the price of that quality is. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
The business model and balance sheet are fundamentally healthy — growth, margins and cash flow rank among the best in the entire pharma industry, and equity keeps growing despite the recent acquisition wave. The rating still sits at yellow because one material operating question remains open: about 65 percent of revenue hangs on a single compound whose prices increasingly come into being at the negotiating table with the government — not a solvency risk, but a concentration that makes every piece of bad news about this one molecule disproportionately heavy. This is a quality judgment about the company, not a statement about entry timing or the currently very athletic price of the stock.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- Price and valuation figures dated September 2, 2026 (about $1,160 per share, about $1,035 billion in market value); analyses are evergreen, daily prices are not a buy argument.
- The Q2 2026 figures ($23.0 billion in revenue, $7.1 billion in net income) are three-month values; growth rates refer to the prior-year quarter. Q2 2026 U.S. revenue also contains a favorable one-off effect from adjusted rebate estimates that management does not expect to repeat in the second half (earnings release August 5, 2026).
- The 2026 full-year guidance ($35.50 to $36.50 in adjusted earnings per share) is a company figure, not an independent forecast — analyst estimates (31 professionals, consensus mostly "buy") are additionally forecasts, not facts, and especially prone to revision given politically negotiated prices.
- Scanner membership: local evaluation with data as of July 8, 2026 (Greenblatt, Levermann, Zweig, EBIT-margin ranking, Altman-Z); checked live on July 14, 2026 — not re-verified since.
- The findings from the analyst earnings calls (chapter "What the analyst calls reveal") rest on five transcripts from Q2 2025 through Q2 2026 and are management statements, not audited facts.
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of September 3, 2026. Stock Watch will tell you what's changed at LLY since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Eli Lilly and Company (LLY), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Eli Lilly (NYSE: LLY) of Indianapolis, founded in 1876, is the most valuable pharmaceutical company in the world. It develops and sells medicines for diabetes and obesity (Mounjaro, Zepbound, Trulicity, and since 2026 the pill Foundayo), cancer (Verzenio), psoriasis (Taltz), migraine and Alzheimer's. In the first half of 2026 Lilly posted $42.8 billion in revenue — 51 percent more than the year-earlier period.
Tirzepatide is an incretin — a compound that mimics the satiety and blood-sugar messengers GLP-1 and GIP. Lilly sells the same molecule under two brands: as Mounjaro for type 2 diabetes ($9.9 billion in revenue in the second quarter of 2026) and as Zepbound for obesity ($4.9 billion). Together the two stood for about 65 percent of group revenue in the second quarter of 2026.
Joel Greenblatt's Magic Formula looks for companies with a high return on capital and a high earnings yield. Lilly qualifies through its extraordinary earning power: an 86 percent gross margin in the second quarter of 2026, a Piotroski score of 8 of 9 (data as of July 8, 2026). The formula's weakness: it measures today's earning power and sees neither concentration risks nor patent calendars nor government price negotiations.
Since the Inflation Reduction Act, the U.S. Department of Health and Human Services (HHS) sets prices for selected Medicare drugs: Jardiance since 2026 (66 percent below the 2023 list price), Trulicity and Verzenio from 2028. Per its annual report, Lilly expects more of its products to follow. The related government agreement is now active: the Medicare GLP-1 Bridge program launched on July 1, 2026 and lowers the cost of weight-loss drugs to $50 a month out of pocket for about 20 million Americans.
Per the annual report, Trulicity will lose significant protections "in the next few years" (U.S. compound patent 2027) — its revenue fell from $7.1 billion (2023) to $4.3 billion (2025), but stabilized in the first half of 2026 (down just 2 percent). Tirzepatide (Mounjaro/Zepbound) is protected by its compound patent until 2036 in the United States; the shorter U.S. data exclusivity, however, ends as early as 2027.
Foundayo is Lilly's weight-loss pill with the compound orforglipron — approved by the FDA against obesity in April 2026 and already generating $98 million in revenue in its debut quarter (Q2 2026). As a pill it needs neither syringe nor cold chain. One catch from the annual report: for pills the U.S. price authority may set government prices as early as nine years after approval, for biologics only after thirteen.
Mainly three things: the U.S. Foundayo launch ran slower than originally signaled and only caught up late in the second quarter of 2026; the CFO guided falling Zepbound net prices for coming quarters once the CVS Caremark formulary return takes effect in the fourth quarter of 2026; and the approval class (and therefore the exclusivity length) of the hopeful pipeline asset retatrutide is, per management, still "active litigation" with an unresolved outcome.
Measured against classic pharma yardsticks, yes: a price-to-earnings ratio of about 45, price-to-sales of about 13, price-to-book of about 31 at about $1,035 billion in market value (data as of September 2, 2026). Based on Lilly's own 2026 guidance ($35.50 to $36.50 per share), the P/E would fall to about 32 — so what is being paid for is sustained high growth, not the level already achieved. On top came a 2026 acquisition wave (Orna, Ajax, Centessa, Kelonia closed, AtaiBeckley announced) that pushed total debt up 29 percent to $54.9 billion within six months; equity remained solidly positive at $33.9 billion.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.