Redwire Stock Forecast: 89 Percent More Revenue, Nearly Quadruple the Share Count — and a $772 Million Goodwill Mountain
Redwire Space reported a record second quarter of 2026 — $117.1 million of revenue, a record $542.1 million backlog, and a visibly de-levered balance sheet. The same report also says: internal control over financial reporting showed "no change," and the share count grew another 30 percent since year-end 2025 — while almost the entire positive result came from the segment with the weakest controls. This Redwire stock forecast sorts the record quarter, the segment truth and the governance finding before it names a single number. Not investment advice — just the question of which of the two stories ends up weighing more with you.
 Thomas Mücke
Founder & Publisher
As of Today
As of: September 17, 2026
- Closing price
- 11.60 $ +7.00%
- Market Capitalisation
- 2.4 $B
- Growth Score
- 2/10
- AAQS
- 4/10
Price change since August 4, 2026: +20.8%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 5.10 $ to 25.90 $ · Last price: 11.60 $ (As of: September 17, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
There is an investor trap that works best on space stocks precisely because it borrows the perfect image for it: the launch trap. A price rockets straight up, and your brain automatically reads that as liftoff — something big is happening here, get in now before it leaves the pad. With Redwire Corporation (NYSE: RDW), better known as Redwire Space, exactly that movie played out in the spring of 2026: swept up in the SpaceX-IPO hype, the stock climbed to an all-time high of $26.64 (late May 2026) — up from a 52-week low of just $4.87. Whoever bought in then is sitting on a loss of roughly half today: at the close on August 7, 2026, the stock stood at $13.59 — and that is already after the jump the second-quarter 2026 results triggered; at the end of July it was still $8.62. A rocket that is falling still looks, from a distance, like a rocket that is climbing — right up until it doesn't anymore.
So let's make a deal before you read the next forecast on the Redwire stock: we read together, first, what Redwire actually told the U.S. securities regulator, the SEC — the annual report (10-K) for 2025 from February 27, 2026, and the most recent quarterly report (10-Q) as of June 30, 2026 from August 5, 2026, plus every mandatory filing through August 7, 2026. A filing to the SEC is honest under penalty of law. And this one tells two stories at once: a record backlog and a gross margin that swung within a year from deeply negative (minus 30.9 percent) to a record 27.8 percent — and a share count that has nearly quadrupled since August 2024, while a fresh $500 million dilution program keeps running. By the end, you decide for yourself which of the two stories weighs more with you.
Redwire Space or Redwire Corporation — Who Is RDW?
The name on the paperwork is Redwire Corporation; in the market and in its own branding, the company calls itself Redwire Space — both names mean exactly the same business, listed on the NYSE under the ticker RDW. At the U.S. securities regulator, the SEC, everything runs under a single identifier, CIK 0001819810. Anyone who knows that number can pull up every mandatory filing the company has made since going public — and that is exactly what we did for this analysis.
Redwire is not a startup in the classic sense; it is the product of a de-SPAC: on September 2, 2021, the operating Redwire group merged with the empty acquisition shell Genesis Park Acquisition Corp. and inherited its stock listing — the faster, but also bumpier, road to the public markets compared with a traditional IPO. Going public through a SPAC means the operating company skipped the usual, often months-long roadshow process with investors; instead, it stepped into an already-listed empty shell and was tradable within weeks. The upside is speed; the downside, which we'll see in the uncomfortable-truths chapter, is less runway to build out everything a company's controls and processes normally need time to mature. The company is headquartered in Jacksonville, Florida, and incorporated in Delaware. At the helm since the founding are Chairman, CEO and President Peter Cannito and CFO Chris Edmunds; the financial statements are audited by KPMG — a name that matters again in the uncomfortable-truths chapter.
As of the July 31, 2026 data cutoff, Redwire employed roughly 1,400 people per fundamental data. The fiscal year ends December 31, and the most recently filed periodic report is the quarterly report (10-Q) as of June 30, 2026, filed August 5, 2026. The second-quarter 2026 report is now in: Redwire released it after market close on August 5, 2026, with an earnings call the following day, August 6, 2026 — those results are worked into this piece starting in "The Numbers Over the Years." What you're reading here, then, reflects the picture after the latest mandatory SEC filings; any statement about a quarter beyond June 30, 2026 is deliberately flagged as a dated outlook, not a fact.
Every price mentioned anywhere in this piece is a dated valuation anchor, never a buy signal for today — that rule holds throughout.
What Redwire Actually Does — Space Infrastructure and Defense Tech Under One Roof
Translated into an everyday picture: Redwire is a supplier of things meant to stay in orbit or fly there — not a rocket builder like SpaceX, but more like the toolbox-and-parts supplier for the companies that are. The business splits into two segments: Space (satellite components, solar-array technology, robotics, digital engineering services) and Defense Tech — a segment that has only existed at this scale since June 13, 2025, the day the acquisition of Edge Autonomy closed.
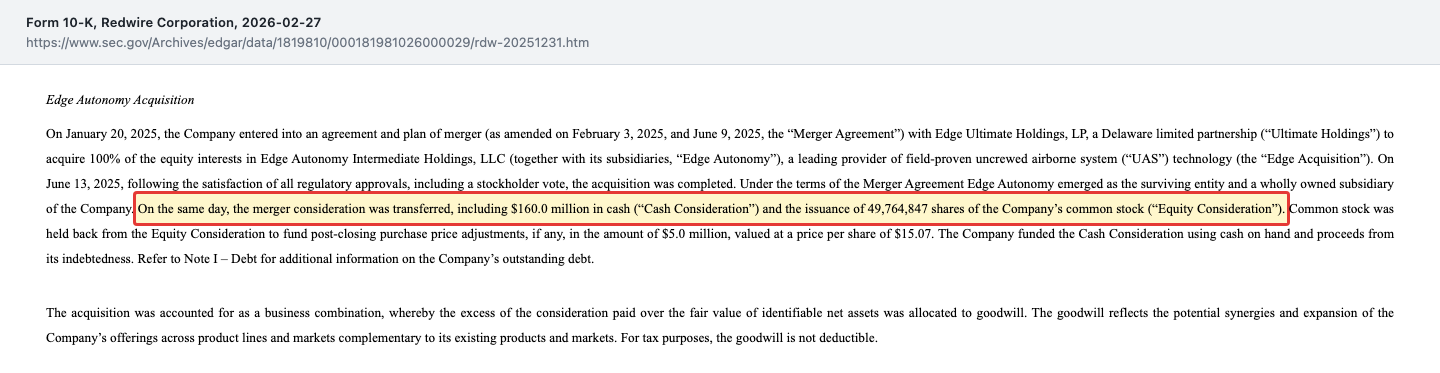
Edge Autonomy is the single largest step in Redwire's recent history. Per the annual report, the purchase price consisted of $160.0 million in cash plus the issuance of 49,764,847 shares of Redwire's own common stock:
"On the same day, the merger consideration was transferred, including $160.0 million in cash (“Cash Consideration”) and the issuance of 49,764,847 shares of the Company’s common stock (“Equity Consideration”).
— Redwire Corporation, SEC annual report 10-K for 2025, Note C "Edge Autonomy Acquisition"
Edge Autonomy brings unmanned aerial systems (UAS) and autonomy technology in-house — Redwire's answer to how the company can broaden out of pure space work into a market with real, near-term demand from defense budgets. The deal was funded from cash on hand, a new $90 million JPMorgan credit facility, and a "Seller Note" of $100 million — a loan from the seller itself, at 15 percent interest with a 1.2x minimum-return clause. Who exactly that seller was, and what it means for Redwire's ownership structure, is its own story, one we've broken out separately in the side-finds attached to this analysis — here in the main text we're focused on the operating business.
Across all of fiscal 2025, Space still carried the lion's share: $209.8 million of revenue against $125.6 million from Defense Tech — though Defense Tech only entered the annual figure from mid-June, so barely more than half a year. By the first quarter of 2026, the first full comparable quarter, the picture had already shifted noticeably: Space contributed $52.7 million to revenue, Defense Tech $44.3 million — after just one more quarter under the same roof, that's already close to half the business. The backlog shows the same shift: of the $411.2 million total at year-end 2025, $299.8 million sat with Space and $111.4 million with Defense Tech. If you want to see how other small space-and-defense suppliers handle exactly this two-segment structure, our T3 Defense analysis is an instructive counterpoint: the word "Defense" carries the name there too, but without the operating substance Redwire at least partly bought along with Edge Autonomy.
A look at the customer mix shows who Redwire actually works for: in fiscal 2025, 46.9 percent of revenue came from the national-security segment, 21.6 percent from civil agencies (such as NASA and ESA), and 31.5 percent from commercial customers; 41.6 percent of revenue came from customers outside the United States. Two individual customers together accounted for roughly 39 percent of revenue (about 19 and 20 percent) — a noticeable customer concentration, though not unusual in the space and defense supply chain. The international share of backlog grew from $70.5 million (end of 2024) to $193.1 million (end of 2025) — more than a tripling, driven in part by Edge Autonomy's Ukraine business. The annual report itself names that exact business as a risk: should the war end, the associated revenue would likely decline — a demand driver nobody wishes for, but one that is genuinely contributing to the backlog today.
A word on the "artificial intelligence" buzzword that hangs around almost every tech-adjacent stock: the annual report for 2025 describes "digital engineering and artificial intelligence automation" as part of the company's own offering — mostly inside the autonomous systems Edge Autonomy brought along. Redwire is therefore not an AI company; it uses AI technology specifically where autonomy is genuinely needed — for instance, in unmanned aircraft that have to navigate on their own. For valuation purposes that means: AI is a component in the product, not a revenue line of its own and not a standalone stock argument.
How This Stock Landed on Our Desk
Redwire surfaced repeatedly through our in-house stock scanner — what we call confluence, when a stock keeps showing up across different filters regardless of whether you sort by balance-sheet strength, price momentum, or valuation metrics. That's rarely a coincidence, and usually a sign that several kinds of market participants are looking at the same story from different angles. With Redwire, the trigger wasn't a single metric but a contradiction between several. The balance-sheet metrics look solid at first glance: an equity ratio of 73.15 percent and a debt-to-equity ratio of just 0.087 (data as of July 31, 2026) — figures more typical of a solid industrial than a company on nine consecutive quarters of net losses. The catch, which we unpack in the uncomfortable-truths chapter: that strength comes almost entirely from freshly issued shares, not from retained earnings.
The Piotroski F-Score, a nine-point test of accounting quality (it checks, among other things, profitability, leverage, and operating efficiency against the prior year), sits at 4 of 9 for Redwire — translated: "okay, not good." A genuinely healthy, growing company usually scores 7 or 8. The Altman Z-Score of 2.31 sits in the so-called gray zone (between 1.81 and 2.99) — neither clearly distressed nor clearly safe, a case for closer scrutiny, not for alarm. Net current asset value (NCAV) is negative at −$102.9 million; for a growing industrial company that's less alarming than it would be for a pure balance-sheet bet, but it shows: at that data cutoff there was no cushion of liquid net working capital here — the $144.5 million of cash (as of March 31, 2026) sat against substantial current liabilities. That picture has since flipped: as of June 30, 2026, Redwire reports $557.0 million of cash — more on that shortly.
Especially telling is the analyst estimate for earnings per share: −$0.12 for the current fiscal year but −$0.68 for the following one (data as of July 31, 2026) — the consensus, in other words, expects a larger loss per share two years out, not a smaller one. Whether that's driven by planned investment, expected further dilution, or conservative modeling, the raw number doesn't say — but it's a reason to look closer, not to trust the rally.
One check our scanner rarely skips: debt against the size of the company. At the time of the scan (data as of July 31, 2026), Redwire carried a market capitalization of roughly $2.02 billion; against that stood comparatively low net debt of just $63.7 million. Both numbers have since moved: after the quarterly report as of June 30, 2026 and the price jump that followed it, the market value stands at roughly $3.4 billion as of August 7, 2026, and net debt has turned into net cash of roughly $509 million ($557.0 million of cash against $48.1 million of financial debt). Translated: whoever bought the entire company would not only get the debt thrown in, but a funded treasury on top — the balance sheet is genuinely a plus here, as contradictory as that reads next to nine loss-making quarters. In short: the scanner showed "solid balance sheet, middling quality, unclear outlook" — on a stock that had hit its all-time high only weeks before the data cutoff and, even after the price jump, still trades roughly 49 percent below it. That gap between the metrics and the price action is exactly why this analysis exists.
The Numbers Over the Years — What Genuinely Impresses First
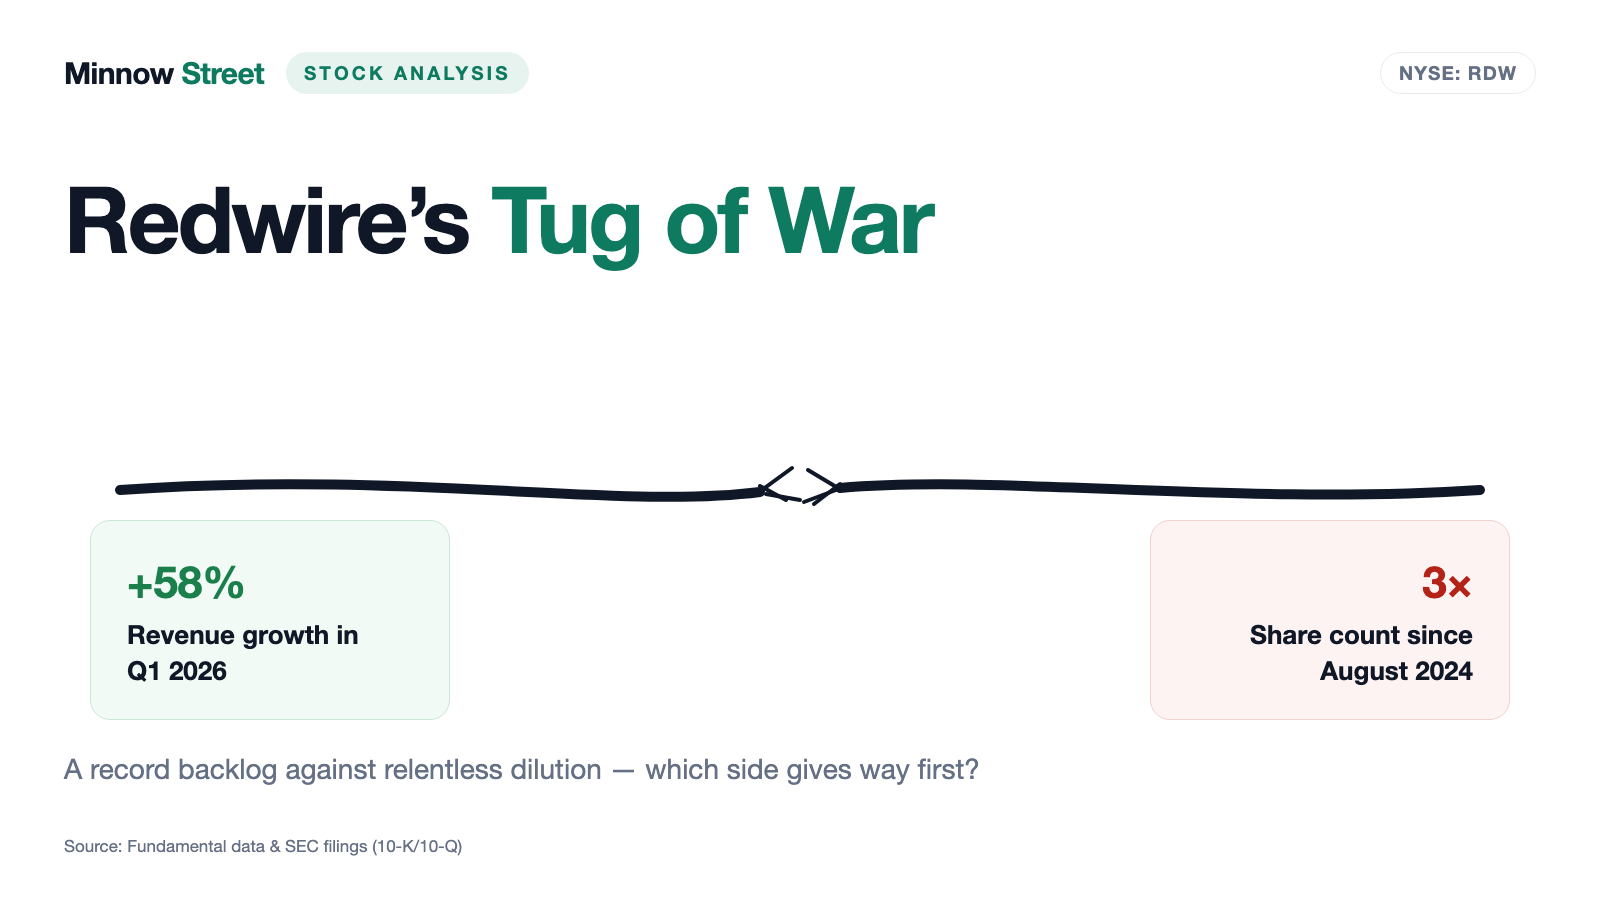
Let's start with what genuinely speaks for Redwire, and it's more than the net loss alone suggests. Revenue has grown every single year since the IPO: from $137.6 million (2021) through $160.5 million (2022) and $243.8 million (2023) to $304.1 million (2024) and $335.4 million for fiscal 2025 — up 10 percent, $107.1 million of it from Edge Autonomy, consolidated since mid-June 2025. In the first quarter of 2026, growth accelerated sharply to up 58 percent year over year — $97.0 million of revenue against $61.4 million. That's the number on our cover image too.
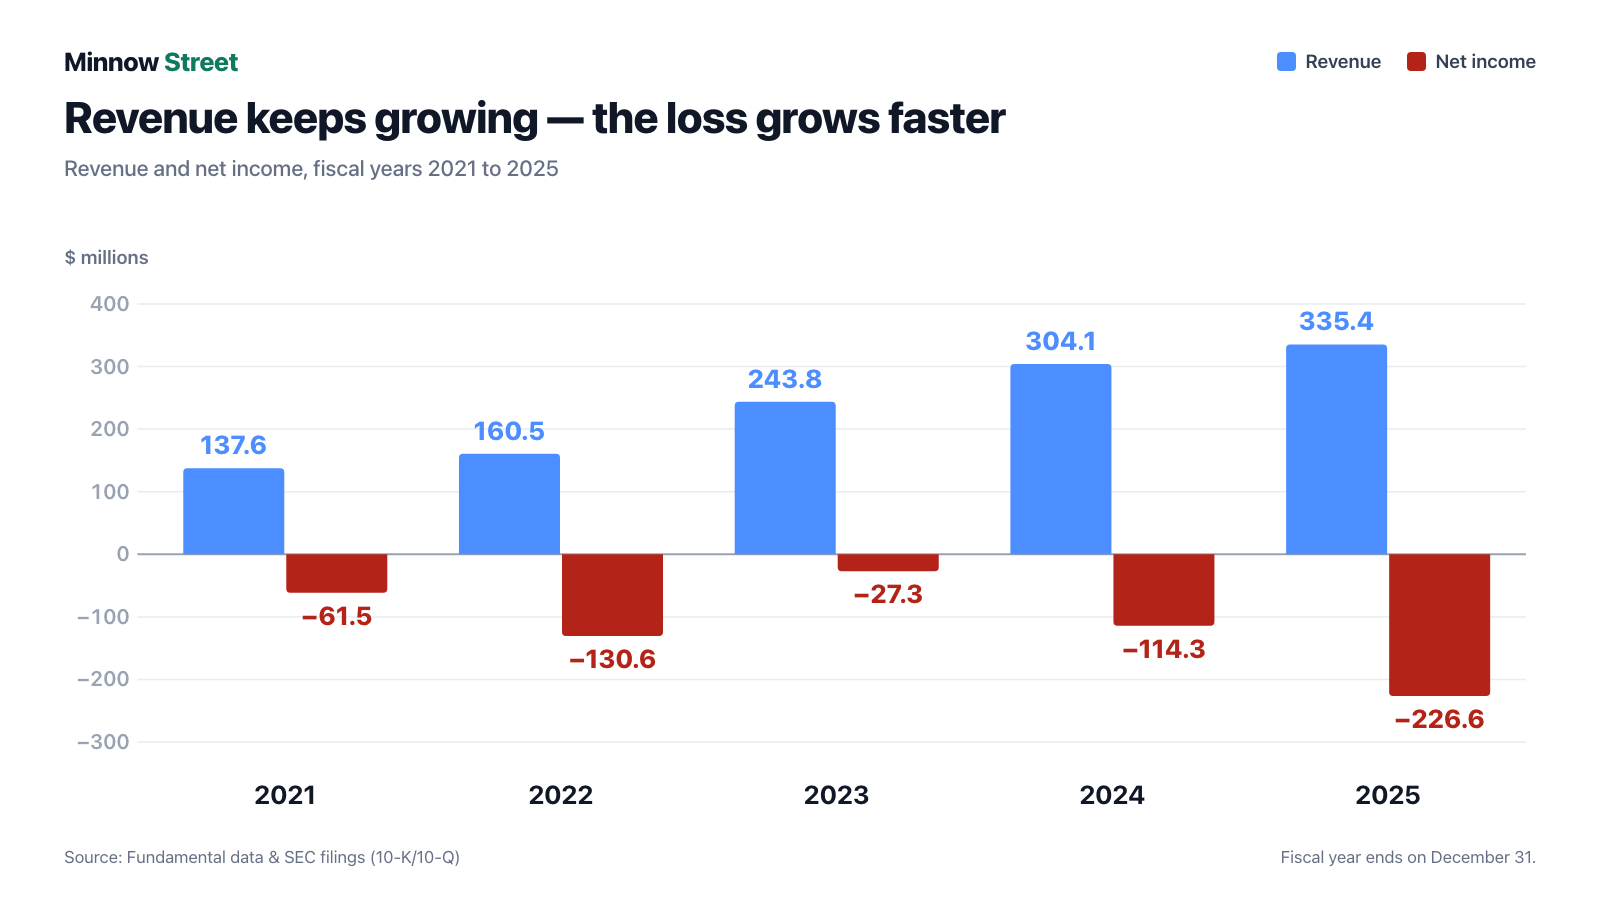
The red series in the chart is the other half of the truth: not one of those five years produced a positive net result. The net loss came in at $61.5 million (2021), $130.6 million (2022), $27.3 million (2023), $114.3 million (2024) and, most recently, $226.6 million (2025). 2023 was by far the best year of the five — since then the shortfall has been widening again, and the 2025 figure is the largest in company history.
Operating cash flow — the cash that actually moves in or out of day-to-day business, independent of accounting effects — also shows no straight line, but a recognizable pattern: −$37.4 million (2021), −$31.7 million (2022), then a single positive year at +$1.2 million (2023), followed by −$17.3 million (2024) and a deep drop to −$177.3 million in the acquisition year 2025 — before easing sharply in the first quarter of 2026 to just −$6.7 million. That number alone explains why Redwire, despite a record net loss in 2025, has no going-concern problem: the large 2025 cash outflow was overwhelmingly integration- and acquisition-related, not a permanent operating state.
The quarter-by-quarter view also shows that 2025 was not a straight path: after $61.4 million of revenue in the first quarter of 2025 (net loss of just $2.9 million, helped by a one-time warrant-valuation gain), a weak second quarter followed with $61.8 million of revenue but a $97.0 million net loss. Business then picked up: $103.4 million of revenue in the third quarter (net loss $41.2 million) and $108.8 million in the fourth quarter of 2025 — the highest single-quarter revenue in company history to that point — at a net loss of $85.5 million, partly due to the goodwill impairment booked that same quarter. The first quarter of 2026, with $97.0 million of revenue and a $76.5 million net loss, continues that pattern: revenue growth, yes; a positive net result, not yet by a long shot.
The real surprise sits in the metrics that rarely make headlines: gross margin jumped from 15 percent (Q1 2025) to 27 percent (Q1 2026), operating cash flow improved from minus $45.1 million to just minus $6.7 million — nearly break-even. And backlog hit a record $498.1 million as of March 31, 2026, up from $411.2 million at year-end 2025:
"Backlog increased to $498.1 million as of March 31, 2026 from $411.2 million as of December 31, 2025."
— Redwire Corporation, SEC quarterly report 10-Q as of 03/31/2026, Item 2 (MD&A)
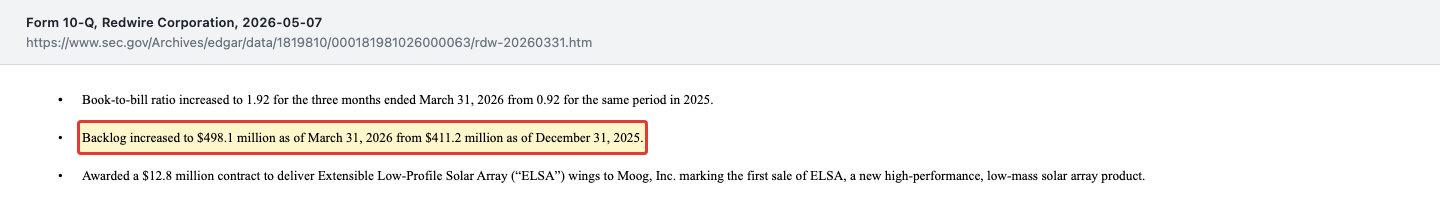
Behind that sits the book-to-bill ratio — a simple metric, translated: is more new business coming in than is being worked off? A value above 1 means yes, the backlog is growing. For Redwire, this ratio jumped from 0.92 (Q1 2025, backlog shrank slightly) to 1.92 (Q1 2026):
"Book-to-bill ratio increased to 1.92 for the three months ended March 31, 2026 from 0.92 for the same period in 2025."
— Redwire Corporation, SEC quarterly report 10-Q as of 03/31/2026, Item 2 (MD&A)
Liquidity is also sturdier than the net loss would suggest: $144.5 million of cash plus a $30 million undrawn credit line as of March 31, 2026, for $174.5 million total; cash alone was thus roughly 52 percent above year-end 2025 ($95.2 million). One quarter later that has multiplied: as of June 30, 2026 the books show $557.0 million of cash and $607.8 million of total liquidity — funded almost entirely out of the ATM program, as the dilution chapter shows shortly. A small but telling detail on the side: standby letters of credit (collateral Redwire has to post with business partners) fell from $15.4 million (end of 2024) to just $0.7 million (end of 2025) — a sign that counterparties are now extending more trust to the company. Redwire itself states a line every investor should read before putting money in, because it is the opposite of a going-concern qualification:
"We believe our existing sources of liquidity will be sufficient to meet our working capital needs and debt service obligations and to comply with our debt covenants for at least the next twelve months from the date on which our condensed consolidated financial statements were issued."
— Redwire Corporation, SEC quarterly report 10-Q as of 03/31/2026, notes (Liquidity)
The debt side has visibly eased too. At the end of 2025, Redwire fully retired its expensive Adams Street loans ($75.5 million of term loans plus a $30 million revolver) out of ATM proceeds — with a $1.0 million loss on early extinguishment. On February 20, 2026 came a new JPMorgan credit agreement: a $90 million term loan plus a $30 million revolver, maturing May 2029, at SOFR plus 3.25 to 3.75 percent — an effective rate around 8.06 percent, well below the prior term loan's effective 13.31 percent. Refinancing added a $2.5 million loss on debt extinguishment in the first quarter of 2026. And right on the quarter-end date came a solid piece of progress: with a first amendment to that credit agreement dated June 30, 2026, Redwire raised the revolver commitment from $30 million to $50 million and at the same time made a voluntary prepayment of $40.0 million on the term loans, cutting their aggregate principal to $50 million. The balance sheet as of June 30, 2026 therefore shows only $48.9 million of gross term loan, or $48.1 million of net financial debt — down from $85.2 million at year-end 2025.
Alongside conventional debt, Redwire also carried expensive preferred capital until mid-2026: 46,505.13 Series A preferred shares with a 13 percent cash (or 15 percent payment-in-kind) dividend and a liquidation preference of $118.4 million as of December 31, 2025 — considerably pricier than any bank loan on the books. As of June 30, 2026 that item is history: the preferred stock was fully converted into common stock, zero shares outstanding — paid for in additional shares, not in cash. Total equity flipped from −$188.7 million (12/31/2024) to +$1,087.5 million (03/31/2026) and on to +$1,629.9 million (06/30/2026) — a sign change that, as we'll see next, comes overwhelmingly from new shares, not from earnings. Whoever looks only at the net loss misses this half of the story. Whoever looks only at the record backlog misses the other half — the one we turn to now.
Update: The Second Quarter of 2026 — A Record Quarter With a Segment Catch in the Fine Print
On August 5, 2026, after market close, Redwire filed its quarterly report (10-Q) as of June 30, 2026, followed by an earnings call the next day. The headline is unambiguously positive: $117.1 million of revenue — up 89.6 percent year over year and up 20.7 percent quarter over quarter, a new record. Gross margin climbed to 27.8 percent (prior-year quarter: negative 30.9 percent), the net loss narrowed to $41.0 million (prior-year quarter: $97.0 million), and earnings per share improved to negative $0.19 (prior-year quarter: negative $1.41). Adjusted EBITDA came in at negative $3.2 million (including $12.5 million of R&D), and free cash flow at negative $35.3 million — both markedly better than the negative $27.4 million and negative $93.5 million, respectively, of the prior-year quarter. Wall Street estimates were clearly beaten: $117.07 million of revenue against $107.91 million expected (up 8.5 percent), and an adjusted loss per share of $0.09 against $0.16 expected. Backlog also hit a new record at $542.1 million — up 8.8 percent from the first quarter and up 64.5 percent year over year — with a book-to-bill ratio of 1.42 (1.52 on a trailing-twelve-month basis). For the first half of 2026 combined: $214.0 million of revenue (prior year $123.2 million), a $117.5 million net loss (prior year $99.9 million), negative $12.4 million Adjusted EBITDA, and negative $48.0 million of free cash flow.
Stopping there tells only half the story — and the second half sits in the segment breakdown the quarterly report spells out more clearly than ever. The Defense Tech segment (Edge Autonomy) generated $61.9 million of revenue in the second quarter — versus just $5.1 million in the prior-year quarter, because the acquisition had only closed on June 13, 2025 — and positive Adjusted EBITDA of $14.1 million (prior-year quarter: negative $15.0 million). The Space segment, by contrast — the business that gave the company its name — brought in only $55.2 million of revenue, slightly less than the $56.7 million of the prior-year quarter, and slipped back into the red with Adjusted EBITDA of negative $4.2 million (prior-year quarter: positive $1.0 million). Backlog splits accordingly: $321.9 million at Space, $220.2 million at Defense Tech.
Translated: the acquired segment is carrying essentially the entire positive result this quarter, while the business that originally put Redwire on the map is shrinking slightly and back to a segment-level loss. The widely quoted 89.6 percent revenue growth is therefore almost entirely inorganic — it comes from consolidating Edge Autonomy, not from organic growth of the pre-existing business. Remember this tension for the chapters that follow: a record quarter and a segment truth that qualifies that record quarter sit in the very same report — both are true, and both belong in any Redwire stock forecast.
What the Filings Say — the Uncomfortable Truths
Now for the other side of the tug-of-war. The chapters so far have deliberately started with what speaks for Redwire — growth, margin recovery, record backlog, falling debt. That wasn't spin; it was the first half of a complete picture. The second half comes now: five findings from the same mandatory SEC reports, each independently sourced and documented — and together they explain why this analysis's quality light lands on red, even though the operating business has genuinely improved lately.
Uncomfortable truth No. 1: the share count has nearly quadrupled since August 2024 — and the next program is already running
Dilution means your slice of the pie gets smaller because the pie keeps getting cut into more pieces — even as the pie itself grows. At Redwire you can read this straight off the cover pages of the company's own SEC filings, because each one states the current share count as of the filing date:
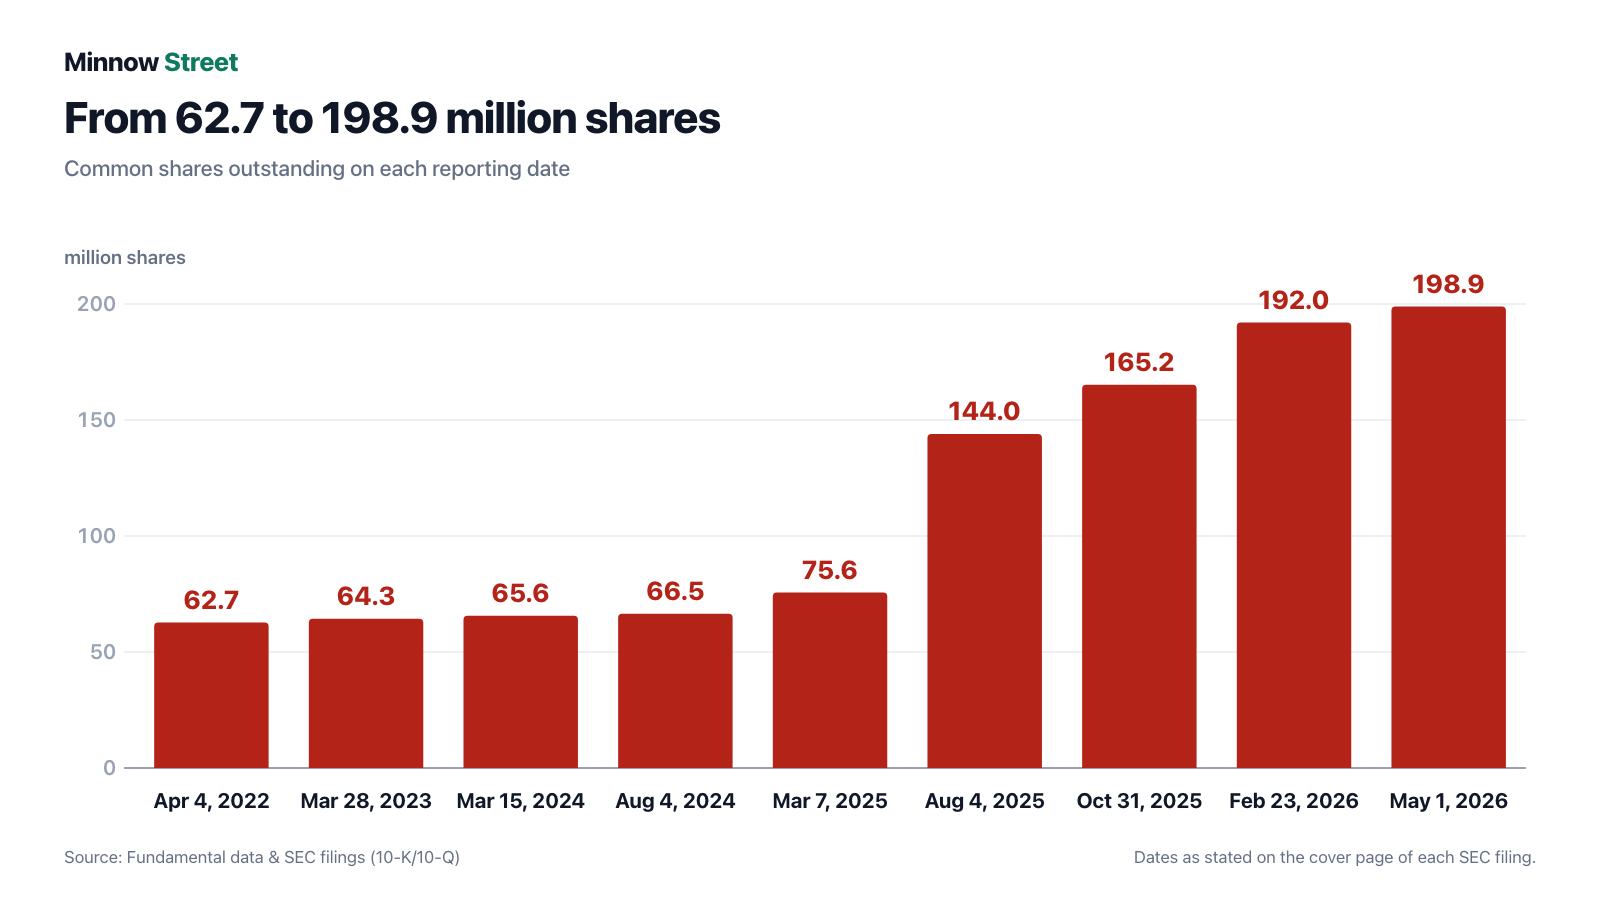
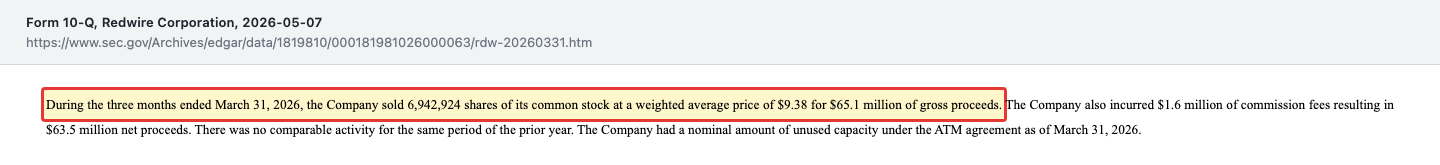
In the first years after the IPO, dilution stayed modest: 62.7 million shares as of April 4, 2022, 64.3 million as of March 28, 2023 and 65.6 million as of March 15, 2024 — fewer than three million additional shares in almost three years. The big jump happens between August 2024 (66.5 million shares) and today: 75.6 million in March 2025, 144.0 million in August 2025, 165.2 million in October 2025, 192.0 million in February 2026, and most recently 198,918,728 shares as of May 1, 2026 — the latest date named before the quarterly report as of June 30, 2026. Part of that comes from the Edge Autonomy purchase (49.8 million new shares in June 2025) and from a capital raise used to retire the expensive seller note (15,525,000 shares at $16.75 in June 2025, $245 million net proceeds). The larger and more durable driver, though, is a so-called ATM program — "at-the-market," a standing authorization to keep selling new shares directly into the market in small tranches, like a faucet that never quite fully closes. The $250 million program launched in November 2025 was, per the quarterly report, effectively exhausted within roughly five months: in the first quarter of 2026 alone, Redwire sold 6,942,924 shares this way:
"During the three months ended March 31, 2026, the Company sold 6,942,924 shares of its common stock at a weighted average price of $9.38 for $65.1 million of gross proceeds."
— Redwire Corporation, SEC quarterly report 10-Q as of 03/31/2026, Note J (Stockholders' Equity)
The quarterly report itself admits the program had only a "nominal amount" of capacity left as of March 31, 2026 — and it was promptly replaced. On May 6, 2026, Redwire launched a new $350 million ATM program; on June 9, 2026 — just five weeks later — that one was already replaced by a $500 million program with ten participating banks. The escalation, in numbers: $250 million (November 10, 2025) → $350 million (May 6, 2026) → $500 million (June 9, 2026). On top sat, back then — as of March 31, 2026 — a dilution reservoir that hadn't even been tapped yet: the preferred stock was convertible into roughly 16,079,001 common shares, plus 2,633,195 warrants with an $11.50 strike price (expiring September 2, 2026) and 3,351,023 shares reserved for employee stock purchases. Most of that reservoir is meanwhile settled: the preferred stock was fully converted into common stock as of June 30, 2026 (zero shares outstanding) — so the reservoir did not vanish, it was drawn — and only 202,069 of the warrants remain — more on that in the paragraph after this one. That this pattern isn't a one-off shows in the rear-view mirror: the public warrants from the SPAC era are already fully spent — 6,738,225 of them were exercised by early 2025 at $11.50 each ($77.5 million of proceeds for Redwire), and another 1,450,586 were redeemed for just $0.01 each. Those were new shares too, every one of them. And the ceiling is set high: Redwire's charter authorizes up to 500,000,000 common shares — against 198.9 million issued as of May 1, 2026, and 250.0 million as of August 3, 2026, there's formally plenty of room for further dilution without a shareholder vote. Remember the mechanism: every new share issued shrinks the slice belonging to everyone already holding one — even while revenue keeps growing at the same time. Anyone who owns 1 percent of Redwire today would, with the same number of shares, have owned roughly 3.8 percent of it in August 2024.
Update from the quarterly report as of June 30, 2026: dilution didn't stop — it kept going. As of August 3, 2026 — the cover-page filing date — Redwire lists 249,992,609 shares outstanding; as of the actual quarter-end, June 30, 2026, it was 249.2 million. Against year-end 2025 (191.9 million), that's up roughly 30 percent in seven months. The weighted average share count for the second quarter was 220.5 million, versus just 89.6 million in the prior-year quarter. The ATM program kept running too, faster than in any earlier stretch: the $350 million program launched in May 2026 was drawn down in full (average price $14.59), and of the $500 million successor program from June 2026, $149.6 million had already been drawn by quarter-end (average price $16.05) — leaving $350.4 million of open capacity. In the second quarter alone, Redwire raised roughly $499.6 million of gross proceeds this way; for the first half of 2026 combined, $564.7 million. And Redwire leaves no doubt that further acquisitions remain explicitly on the table — management calls M&A "fundamental to our DNA" — fundable out of $607.8 million of total liquidity plus the open ATM capacity.
Fairness demands the counterweight here too, because the fresh shares didn't simply vanish: financial debt fell to just $48.1 million (year-end 2025: $85.2 million), the expensive Series A preferred stock was fully converted into common stock — zero shares outstanding as of June 30, 2026, versus 46,505.13 shares carrying a 13/15 percent dividend before; that swap is itself a piece of the dilution and sits inside the 249.2 million shares —, interest expense dropped below $1 million (prior-year quarter: $23.8 million), the public warrants from the SPAC era are fully spent (zero outstanding), and only 202,069 private warrants remain (expiring September 2, 2026). Cash itself rose to $557.0 million. Put differently: a good share of the dilution converted directly into a noticeably stronger balance sheet — that doesn't explain the dilution away, but it does explain where the fresh capital actually went.
Uncomfortable truth No. 2: the company's own accounting controls failed their own inspection
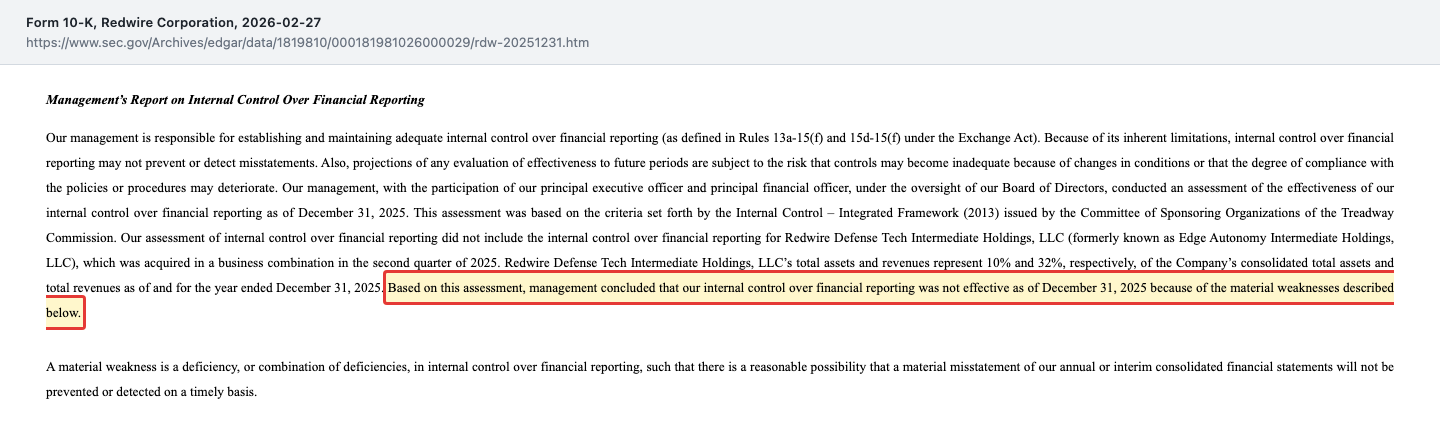
Internal control over financial reporting (ICFR), translated into an everyday image, is the safety inspection for a company's books: a system of checks meant to ensure the numbers in the financial statements are correct before they ever reach the outside auditors. Redwire's own management reached a clear verdict for fiscal 2025 — and it reads: failed.
"Based on this assessment, management concluded that our internal control over financial reporting was not effective as of December 31, 2025 because of the material weaknesses described below."
— Redwire Corporation, SEC annual report 10-K for 2025, Item 9A (Controls and Procedures)
Important context: this is not an accusation of misstated numbers — the report doesn't name any resulting financial-statement errors. It's a process verdict: controls in the United States couldn't be demonstrably operated effectively for long enough, and Europe plus the rest of the U.S. business lacked sufficient IT general controls (ITGCs). Auditor KPMG confirmed that verdict with a so-called "adverse opinion" — the harshest rating available for internal control. Making it worse: the newly acquired Edge Autonomy unit — a full 10 percent of total assets and 32 percent of group revenue — was entirely excluded from this 2025 assessment and carries its own, still-unresolved control weaknesses. Translated: the largest single acquisition in company history hadn't even been through the same inspection as the rest of the group yet.
Redwire is no stranger to this topic. The company already went through a restatement era in 2021 — late quarterly filings (NT 10-Q in May and November 2021) and an amended annual report (10-K/A), fallout from the SPAC era, when many freshly listed companies had to re-do their warrant accounting. That same period produced a shareholder class action (filed December 2021) that was already settled earlier. At the annual meeting on May 20, 2026, all nominated directors were elected and KPMG was ratified as auditor for 2026 — the record date of March 27, 2026 carried voting rights for the 198,918,728 common shares plus 46,505.13 preferred shares (equivalent to 16,067,291 votes). A routine, unremarkable outcome on its own — but a signal that current leadership continues to hold investor confidence while the control question stays unresolved in the background. Separately, since February 2026, a settlement has been working through a distinct shareholder derivative suit (Yingling v. Cannito) that also traces back to the restatement era: it provides for governance reforms and D&O-insurance-funded legal fees, received preliminary court approval on June 8, 2026, and had its final hearing scheduled for July 30, 2026. Two separate suits, one shared root: the accounting troubles of the early years after the SPAC listing. As a countermove, Redwire brought a former EY audit partner with 38 years of experience, Gregory L. Heston, onto the board and audit committee on July 14, 2026 — succeeding David Kornblatt. Whether that's enough won't be clear before the next annual report: remediation steps are planned for 2026 but not yet complete.
Update from the quarterly report as of June 30, 2026: on the safety inspection for its own books, nothing moved in the second quarter of 2026 — literally nothing:
"There was no change in our internal control over financial reporting that occurred during the three months ended June 30, 2026 […] We cannot at this time estimate how long it will take to remediate these material weaknesses."
— Redwire Corporation, SEC quarterly report 10-Q as of 06/30/2026, Item 4 (Controls and Procedures)
Two details here deserve attention. First: Redwire names no timeline for remediation whatsoever — not "shortly," not "next quarter," just "cannot at this time estimate." Second, elsewhere in the very same document sits a small but telling blemish: the "Note S — Subsequent Events" section appears in the filed document as a literal "[TBD]" placeholder — to be determined. A placeholder like that in a signed SEC filing is unusual, and it underscores how far from smooth the internal reporting process still runs. One more sharp detail: the unit carrying the single largest goodwill position, Defense Tech, is the very same one still lacking effective IT controls. And across the entire August 6, 2026 earnings call, not a single analyst asked a question about any of this — a sign the market is currently weighing operating progress more heavily than the unresolved control question, not evidence that the question has been resolved.
Uncomfortable truth No. 3: the Edge bet — $721 million of goodwill became $735 million, and the first impairment came after two quarters
Of the $160.0 million cash purchase price and the 49.8 million new shares for Edge Autonomy, the largest single chunk landed not in machinery, patents, or customer contracts, but in a balance-sheet line that's hard to pin down: goodwill. Translated: the premium a buyer pays above a company's tangible value — for expectations, market position, future hope. For Edge Autonomy the original purchase price allocation put that at $721.3 million, alongside $264.8 million of developed technology, $15.4 million of customer relationships, and $17.9 million of trade name. The item has since grown: as of June 30, 2026, Redwire reports $735.1 million of goodwill in the Defense Tech segment, and $772.2 million group-wide including the Space segment. The increase over the $721.3 million is not a new acquisition but the result of subsequent measurement-period adjustments and currency effects. Goodwill is the line that falls first at the annual impairment test when expectations don't pan out — and that's exactly what already happened at Redwire, and quickly: just two quarters after the June 13, 2025 closing, Redwire had to write down $34.7 million in the fourth quarter of 2025, $20.9 million of it against goodwill, $10.9 million against intangibles, and $2.6 million against property and equipment.
For scale: the $735.1 million of goodwill in the Defense Tech segment equals roughly 45 percent of the $1,629.9 million of equity reported as of June 30, 2026; total goodwill of $772.2 million equals roughly 23 percent of the roughly $3.4 billion market value (at the August 7, 2026 price). Put another way: Defense Tech, the segment carrying this goodwill, generated $61.9 million of revenue in the second quarter of 2026 — the goodwill alone equals roughly 12 times a single quarter of that segment's revenue. A concentration risk of this size means: should the annual impairment test — the next one due with the fiscal 2026 annual report — again trigger a write-down, it would hit reported equity directly, without a single dollar of cash moving. One additional, concrete risk specific to this goodwill: part of Edge Autonomy's business is tied to the war in Ukraine, whose associated revenue the annual report already describes as declining — should the war end, that demand driver could disappear entirely. How seriously the auditor itself treats this line shows in the fact that KPMG flags the Edge Autonomy purchase price allocation in the annual report as a "Critical Audit Matter" — a distinct, specially highlighted audit note reserved for balance-sheet items with high judgment and high significance to the financial statements. Translated: even the auditor is implicitly saying the valuation of this one item carries an unusual amount of judgment. Fairness demands the other side of the ledger too: Defense Tech, the segment Edge Autonomy anchors, is at the same time the only segment with a positive segment result (Adjusted EBITDA of plus $14.1 million in the second quarter of 2026, after plus $5.4 million in the first) — and no further impairment was required in the first half of 2026. The bet isn't lost from the outset, but it's expensive, and it has already gone wrong once.
Uncomfortable truth No. 4: the net loss is real, but larger than the operating picture — and 2025's gross margin was the exception, not the norm
Two numbers from the first quarter of 2026 deserve closer scrutiny because they point in opposite directions if you only read the headline. First: the reported net loss of $76.5 million contains more than $44 million of one-time effects — $42.1 million alone from accelerated vesting costs on "Edge Incentive Units" (a stock-based compensation component from the purchase agreement whose acceleration clause triggered in the first quarter of 2026). SG&A costs (sales, general and administrative expenses) totaled $82.9 million — 85 percent of quarterly revenue — as a result. Already across full-year 2025, the same line item had risen sharply, driven in part by $47.1 million of additional stock-based compensation, $44.4 million of which was those same Edge Incentive Units — so the Q1 2026 spike was the continuation of a pattern already set in motion in 2025, not a one-off surprise out of nowhere. Adjusted EBITDA, which strips out effects like these, came in at "only" minus $9.2 million, and Defense Tech was already positive at the segment level, at plus $5.4 million. So the net loss is real — but noticeably smaller than the headline number suggests.
Second, and this puts the gross-margin recovery from the previous chapter in perspective: across all of fiscal 2025, gross margin was just 5 percent — down from 15 percent the year before. The main reason sits in a term worth understanding once, because Redwire's numbers barely make sense without it: EAC adjustments (Estimate-at-Completion). Many space and defense contracts are multi-year fixed-price agreements — Redwire promises today's price for work that won't be finished for two or three years. If a project turns out to cost more than budgeted along the way, the company has to book that retroactively in the current period. That is exactly what happened in 2025, at a scale large enough to drive the weak margin on its own: −$54.5 million of net adjustments, after already −$17.7 million the prior year — more than a tripling. On top came $13.6 million of non-cash purchase-accounting effects from the Edge acquisition. A third cost block weighed on the 2025 income statement as well: net interest expense rose $26.2 million, $20.0 million of it from the previously mentioned "seller note" — the 15 percent-interest loan from the seller that Redwire had already retired by June 2025, but only after several months of expensive bridge financing.
Translated into an everyday picture: a construction contractor promises a customer a fixed price for a building project. If material costs rise faster than expected during construction, the contractor eats the difference — not the customer. With several large projects running at once, that can eat an entire year's margin. The jump to 27 percent in the first quarter of 2026 and the 27.8 percent in the second are therefore an encouraging signal, but not yet proof: the quarterly report doesn't break out EAC adjustments for the single quarter, and two good quarters don't disprove a multi-year series of fixed-price cost overruns. Management itself says plainly that the 27.8 percent is not the new baseline and that "low-to-mid 20 percent" is the nearer-term expectation — explicitly because of possible EAC adjustments. Whether the recovery is the new normal or a snapshot won't be clear before the next annual report at the earliest. One last footnote for anyone doing their own earnings-per-share math: because the bottom line is a loss, warrants, preferred stock, and employee purchase rights are explicitly treated as not dilutive in the earnings-per-share calculation per the quarterly report ("anti-dilutive") — the real dilution from Truth No. 1 therefore doesn't yet show up fully in the EPS figure at all, only in the raw share count.
Uncomfortable truth No. 5: the company's own revenue guidance calls for two more quarters at a freshly set record level
For full-year 2026, Redwire most recently affirmed revenue guidance of $450 to $500 million:
"For the full year ended December 31, 2026, Redwire affirms that it is forecasting revenues of $450 million to $500 million."
— Redwire Corporation, Results release, 8-K of 05/06/2026, Ex 99.1
Let's do the arithmetic on what that requires. In the first half of 2026, Redwire generated $214.0 million in total. To reach the $450 million floor, the remaining two quarters together need to deliver $236 million — an average of roughly $118 million per quarter. For the $500 million ceiling, it would be $286 million, or roughly $143 million per quarter. The strongest single quarter in company history is now the second quarter of 2026 at $117.1 million — the old record of $108.8 million (fourth quarter of 2025) was beaten for the very first time. And that is exactly the point: Redwire has just proven that a quarter at this level is possible — the guidance now requires holding that freshly set record level in both remaining quarters, and clearly exceeding it to reach the upper end.
That's not an automatic red flag — the record backlog ($542.1 million, book-to-bill 1.42), the "Andromeda" umbrella contract with the Space Systems Command announced in May 2026 with a $1.8 billion ceiling, and the "NITE-STAR" umbrella contract added in the third quarter with a $981 million ceiling (both shared award vehicles with no guaranteed individual task order, and therefore not reflected in backlog), at least supply an order base for it. A $12.8 million order for ELSA solar arrays from Moog, more than $20 million of Stalker UAS orders from the U.S. Marine Corps, and an order from the European Space Agency (with Honeywell) for space-based quantum key distribution also landed in the first quarter of 2026 — and after quarter-end, the Artemis II mission launched with Redwire technology on board. But a full backlog doesn't guarantee revenue that lands on time — as Truth No. 4 just showed. Whoever buys into Redwire's own revenue guidance is implicitly also buying the bet that the first record quarter is followed by two more at the same level — a streak this company has never once managed before.
Redwire Stock Forecast: Price Targets and What the Numbers Support
Every serious Redwire stock forecast has to open with a caveat: for a company on nine consecutive quarters of losses, there's no price-to-earnings ratio that can be meaningfully computed. What matters is, first, what the company itself is promising for the rest of the year, and second, what professionals are actually willing to pay for it today. On the first point: alongside its Q2 results, Redwire affirmed its full-year 2026 revenue guidance of $450 to $500 million — it was explicitly not raised. The CFO put visibility at 90 percent of the guidance midpoint, a sharp jump from the 75 percent cited in the first quarter — a sign management is now considerably more confident in its own numbers for the second half. On the second point, though, management dampened expectations itself: the 27.8 percent gross margin in the second quarter is explicitly not the new baseline; near term, margin is more likely to run in a "low-to-mid 20 percent" range — possibly because of ongoing cost re-estimates on individual contracts (EAC adjustments, see Truth No. 4) or engineering changes in ongoing work. Redwire still issues no guidance on Adjusted EBITDA or free cash flow.
The market reacted clearly positively to this mix of affirmed guidance, record results, and dampened margin expectations: from the August 5, 2026 close ($10.72, results released after the bell), the stock rose roughly 9.8 percent on August 6 and closed at $13.59 on August 7, 2026 — a cumulative gain of roughly 27 percent over two trading days. On the most recently reported share count (249,992,609, August 3, 2026), that puts market capitalization at roughly $3.4 billion and enterprise value (market cap plus net debt) at roughly $2.9 billion. Measured against the midpoint of Redwire's own revenue guidance ($475 million), that works out to an enterprise-value-to-sales ratio of roughly 6.1 — with Adjusted EBITDA and free cash flow both still negative. Translated: the market isn't paying for today's profits here; it's paying for the bet that this quarter's record numbers weren't a one-off.
Just how bumpy the ride there has been still shows in the 52-week range: $4.87 to $26.64, a factor of more than five — even after the two-day jump to $13.59, the stock still sits roughly 49 percent below its spring 2026 all-time high. The analyst consensus — the "professionals' view," put in context rather than taken at face value — remains "Buy," with an average price target of roughly $15.79 (Alliance Global at $16, Cantor Fitzgerald at $13.50, among others). Measured against the August 7, 2026 close, that's just over 16 percent above the current level — noticeably closer to the price than before the quarterly report, but still a snapshot of sentiment from a handful of people on one particular day, not a guarantee and not our own analysis. If you're looking for a Redwire stock forecast for 2030: neither the company nor any analyst we reviewed offers a credible multi-year price range. Any number for 2030 would be pure extrapolation off the affirmed 2026 revenue guidance, not a fact drawn from the filings.
One comparison point investors in other space and defense stocks will recognize: readers of our Intuitive Machines analysis will spot the same pattern — a revenue jump driven by acquisitions and large contracts, while the loss persists and the share count grows. The difference at Redwire, now sharper than before: one segment (Defense Tech) now carries the entire positive result, while the other (Space) is shrinking organically — so the question is no longer just "is the business growing," but "is the right business growing." Whether that's enough to outweigh the dilution is, in the end, the central math behind any Redwire stock forecast — and every reader runs that math for themselves.
For anyone who wants to track the building blocks of that math directly, three concrete, dated questions the third-quarter 2026 report will answer offer a useful anchor: first, does gross margin actually hold in management's own "low-to-mid 20 percent" corridor, or does it slide back toward the 5 percent seen for full-year 2025? Second, does Defense Tech keep growing at a double-digit pace while the slight Space decline continues or reverses? And third, what does the cover-page share count show — does it stay close to the 249.99 million from August 3, 2026, or does it reveal that the $350.4 million of open ATM capacity has already been drawn down hard? Those three numbers, not the daily stock price, will decide which of Redwire's two stories ends up on top.
One question readers regularly ask us now has a shorter answer than it did before the second quarter: Redwire still pays no dividend on its common stock — every available dollar goes into growth, integration, and debt paydown. The earlier recurring payout to holders of the Series A preferred stock is now gone entirely: that preferred stock was fully converted into common stock as of June 30, 2026, with zero shares outstanding. Whoever is hoping for cash income from Redwire still isn't waiting on a dividend — ultimately, they're waiting on a higher stock price.
Opportunities and Risks at a Glance
Both sides of the tug-of-war, side by side once more, taken equally seriously — neither cancels the other out.
What speaks for Redwire:
- Record Q2 2026: $117.1 million of revenue (up 89.6 percent year over year), record backlog of $542.1 million at a book-to-bill ratio of 1.42 (1.52 on a trailing-twelve-month basis).
- Strong order flow: the $981 million "NITE-STAR" umbrella contract with the Space Systems Command, a multi-year, high-eight-figure Penguin UAS contract with a NATO country, plus follow-on Stalker drone orders from the U.S. Marine Corps and U.S. Army.
- Debt paid down to just $48.1 million (year-end 2025: $85.2 million), the expensive Series A preferred stock fully converted into common stock, interest expense near zero, $557.0 million of cash.
- Defense Tech (Edge Autonomy) already delivers a positive segment result of $14.1 million of Adjusted EBITDA in the second quarter of 2026 — a genuine operating leg alongside the space business.
- Dual manufacturing base in the United States (Stalker) and the EU/Latvia (Penguin) sidesteps ITAR trade restrictions on orders from NATO partners.
What speaks against it:
- Internal control over financial reporting remains not effective — the quarterly report as of June 30, 2026 explicitly states "no change" and names no timeline for remediation; the subsequent-events section even appears in the filing as a literal "[TBD]" placeholder.
- Dilution genuinely continued: 249,992,609 shares as of August 3, 2026 (up 30 percent since year-end 2025), $350.4 million of open ATM capacity, and further acquisitions explicitly called "fundamental" by management.
- The namesake Space segment shrank slightly in the second quarter of 2026 ($55.2 million versus $56.7 million a year earlier) and is back in the red at negative $4.2 million of Adjusted EBITDA — so the 89.6 percent revenue growth is almost entirely inorganic.
- Inventory built up 23 percent quarter over quarter, and free cash flow remains negative (negative $35.3 million for the quarter, negative $48.0 million for the half) despite record revenue.
- Management is dampening its own margin expectations: the 27.8 percent gross margin from the second quarter is explicitly not the new baseline; near term, "low-to-mid 20 percent" is the more likely range.
What's striking is how cleanly the two lists split: the positive side is almost entirely made up of operating progress — margin, cash flow, backlog, debt. The negative side is almost entirely made up of structural questions — controls, capital structure, balance-sheet risk, the pace of guidance. That's not a coincidence; it is exactly the tug-of-war this analysis is named for: the operating business and the corporate structure have recently been moving in opposite directions, and neither side undoes the other.
A Human Conclusion
Back to the launch trap from the beginning. Its core isn't that Redwire is a bad company — the record quarter, the affirmed revenue guidance, and the debt paydown are real, documented progress, and the roughly 27 percent two-day stock jump shows the market is rewarding exactly that. Its core is that a steeply climbing price tells your brain the problem is already solved — even though the same quarterly report that announces the record quarter admits, in the same document, "no change" in its own internal control and names no timeline for fixing it. And even though that same report's segment figures show that the acquired segment with the still-ineffective IT controls is responsible for essentially the entire positive result, while the namesake space business is shrinking slightly. All three facts sit in the same document. All three are true.
The honest question for you, then, isn't "Am I missing the next SpaceX effect?" but: do you trust a management team that has now delivered operationally two quarters running, but still has no visible timeline for fixing its own accounting controls — and are you willing to keep watching your slice shrink while the segment with the weakest controls is the one carrying the growth? Both answers are legitimate. Whoever says yes is buying a bet on a management team that has proven itself operationally for two quarters straight, hoping the governance and dilution problems shrink rather than grow by the next annual report. Whoever says no would rather wait for more proof — a clean ICFR opinion, an ATM program that actually stops running, or a Space segment that turns itself around. If you answer that question yes, you have a thesis. If not, you had a rocket. What you make of it is your decision — and no Redwire stock forecast anyone hands you changes that. Not investment advice.
Sources
All original documents used in this analysis — to read for yourself:
- Redwire Corporation — SEC annual report 10-K for 2025 (filed February 27, 2026)
- Redwire Corporation — SEC quarterly report 10-Q as of March 31, 2026 (filed May 7, 2026)
- Redwire Corporation — SEC quarterly report 10-Q as of June 30, 2026 (filed August 5, 2026) — most recent periodic report evaluated
- Redwire Corporation — Second-quarter 2026 results press release (August 5, 2026)
- Redwire Corporation — Second-quarter 2026 earnings call transcript (August 6, 2026)
- Redwire Corporation — Results release, 8-K of May 6, 2026 (Ex 99.1, Q1 2026)
- Redwire Corporation — current reports (8-K) of May 20, June 9, June 18, July 1 and July 14, 2026, plus ownership filings (SCHEDULE 13D/A of May 20, SCHEDULE 13G of July 29, 2026)
- Full SEC filing history of Redwire Corporation: EDGAR overview (sec.gov)
- Fundamental data (metrics, price data, scanner metrics; data as of July 31, 2026), reconciled with the SEC filings and the SEC XBRL financial series.
Transparency & disclaimer: This analysis is a journalistic contextualization of publicly available information and is not investment advice, not a financial analysis in the regulatory sense, and not a solicitation to buy or sell securities. Stock investments carry substantial risks up to total loss. All information without warranty; the data cutoff is noted in the text throughout. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this deep dive.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 137.6 | 160.5 | 243.8 | 304.1 | 335.4 |
| Operating Income (EBIT) | -70.2 | -146.4 | -15.5 | -42.2 | -229.7 |
| Net Income | -61.5 | -130.6 | -27.3 | -114.3 | -226.6 |
| Net Margin | -44.7% | -81.4% | -11.2% | -37.6% | -67.6% |
| Earnings Per Share | -0.98 $ | -2.03 $ | -0.42 $ | -1.73 $ | -1.90 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
Our Bottom Line at a Glance
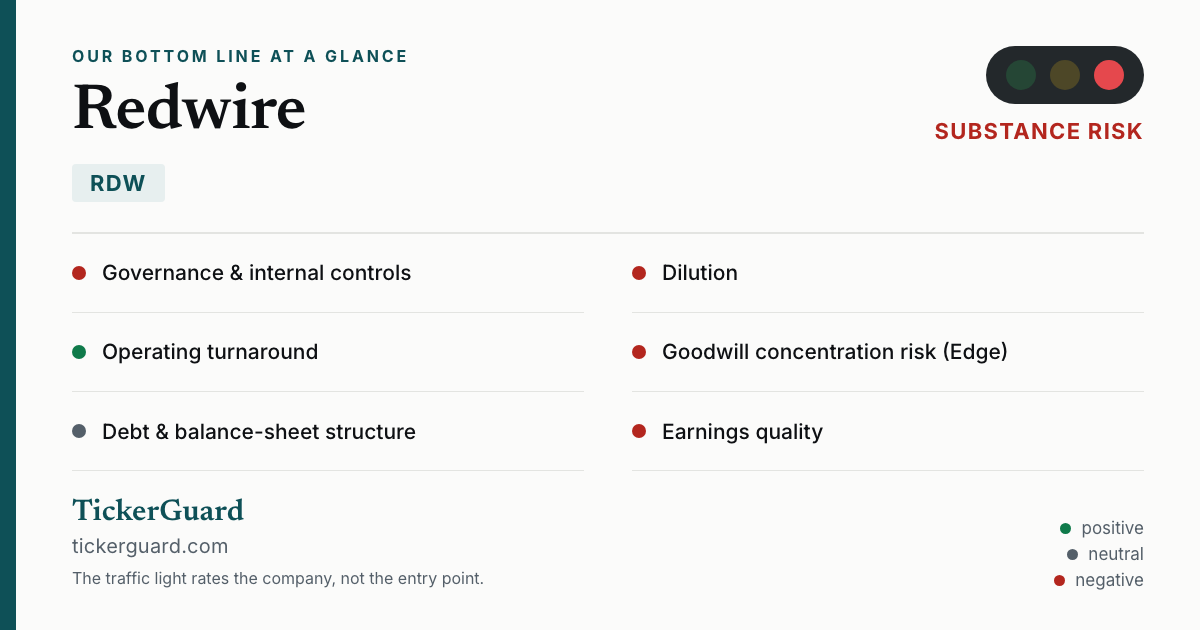
- Governance & internal controls negative
- The quarterly report as of June 30, 2026 explicitly states "no change" in internal control over financial reporting and names no timeline for remediation; the "Subsequent Events" section even appears in the filing as a literal "[TBD]" placeholder. No analyst asked about it on the August 6, 2026 call.
- Dilution negative
- Share count rose to 249,992,609 (08/03/2026) — up roughly 30 percent since year-end 2025. $350.4 million remains open on the $500 million ATM program, and management explicitly calls further acquisitions "fundamental to our DNA."
- Operating turnaround — with a segment caveat positive
- Record quarter: $117.1 million of revenue (+89.6% y/y), 27.8% gross margin, $542.1 million backlog (record). The catch: almost the entire positive result comes from the acquired Defense Tech segment (+$14.1 million Adjusted EBITDA); Space shrank slightly and is back to negative $4.2 million Adjusted EBITDA.
- Goodwill concentration risk (Edge) negative
- Goodwill from the Edge acquisition now stands at $772.2 million (Space $37.1 million, Defense Tech $735.1 million) — no further impairment in the first half of 2026, but the unit carrying the largest goodwill balance is the same one still lacking effective IT controls.
- Debt & balance-sheet structure positive
- Financial debt cut to $48.1 million, the expensive Series A preferred stock fully converted into common stock (zero outstanding), interest expense near zero, cash at $557.0 million. Total equity rose to $1,629.9 million — driven overwhelmingly by new shares, but this time also by a visibly de-levered balance sheet.
- Earnings quality & guidance pace neutral
- Net loss narrowed to $41.0 million (Q2 2026); Adjusted EBITDA stayed just negative at −$3.2 million. Full-year 2026 revenue guidance ($450–$500 million) was affirmed, not raised; management itself is dampening margin expectations ("low-to-mid 20 percent").
Redwire Space delivered a record second quarter of 2026: $117.1 million of revenue, a record $542.1 million backlog, and a noticeably de-levered balance sheet with preferred stock converted into common stock. The same report, though, states that internal control over financial reporting showed "no change" and still carries no remediation timeline, the share count grew a further roughly 30 percent since year-end 2025, and the positive result comes almost entirely from the segment with the weakest controls, while the namesake space business shrinks slightly. Not investment advice.
What Our Rating Means
Substance risk
We found at least one documented issue that threatens the company itself — regardless of how the stock is currently valued.
Red holds because the governance finding itself did not change in the second quarter of 2026 — and that is literally true: the quarterly report as of June 30, 2026 confirms "no change" in internal control over financial reporting and still "cannot at this time estimate" how long remediation will take; the subsequent-events section even appears in the filed document as a literal "[TBD]" placeholder. That remains a balance-sheet/governance breach under our criteria, not a footnote — and it now carries more weight, not less: the Defense Tech segment, which delivered essentially the entire positive result this quarter ($61.9 million revenue, +$14.1 million Adjusted EBITDA) and carries most of the $772.2 million of goodwill, is the very same unit whose IT controls remain rated ineffective. On top of that, dilution genuinely continued: 249,992,609 shares as of August 3, 2026, up roughly 30 percent since year-end 2025, with $350.4 million of ATM capacity still open and management explicitly calling further acquisitions "fundamental." In fairness, the other side deserves to be said plainly, because it does not undo this rating but does put it in context: the operating turnaround is now documented across two quarters running — record revenue, a record $542.1 million backlog, affirmed (if not raised) revenue guidance, and a balance sheet that is visibly stronger with preferred stock converted into common stock and debt cut to $48.1 million. Those results continue to speak well of the management team — but they do not cancel the governance finding; they only show work is underway on the operating front while the control question has sat unmoved for at least two quarters. Whether that is enough to move the light to yellow at the next annual report still depends chiefly on a clean remediation of internal controls — not on the stock price. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- Redwire reached our research list via our in-house stock scanner, triggered by a contradiction between balance-sheet strength and middling overall quality — on a stock that hit an all-time high of $26.64 in the spring 2026 SpaceX hype, had given back roughly two-thirds of it, and then jumped roughly 27 percent over two days after the August 5, 2026 Q2 report.
- Recency gate: the most recent periodic report evaluated is the quarterly report (10-Q) as of June 30, 2026, filed under accession no. 0001819810-26-000124 (results released after market close on August 5, 2026, call on August 6, 2026).
- Price reaction: August 5, 2026 close $10.72 (before results) → August 6 roughly +9.8% → August 7, 2026 close $13.59; market capitalization on that basis roughly $3.4 billion (249,992,609 shares).
- Risk of confusion: Redwire Corporation (Redwire Space, NYSE: RDW) is an independent company with no tie to SpaceX; name and topical similarity caused confusion on forums during the spring 2026 SpaceX-IPO hype.
- The quality light rates the company, not the entry price: whether the stock is cheap or expensive at the current price ($13.59, 08/07/2026) is a question for the scanners and valuation metrics (enterprise value to sales roughly 6.1 on the guidance midpoint), not this light.
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of August 26, 2026. Stock Watch will tell you what's changed at RDW since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Redwire Corp (RDW), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Redwire Corporation, known in the market as Redwire Space (NYSE: RDW), builds space infrastructure in its Space segment and, since the Edge Autonomy acquisition (June 13, 2025), unmanned aircraft and autonomy technology in its Defense Tech segment. In the second quarter of 2026, Defense Tech was the main growth driver, with $61.9 million of revenue and a positive segment result, while Space shrank slightly to $55.2 million.
The analyst consensus is "Buy," with an average price target of roughly $15.79 (Alliance Global at $16, Cantor Fitzgerald at $13.50, among others) — just over 16 percent above the August 7, 2026 closing price of $13.59. Redwire itself, after the second quarter of 2026, only affirmed its 2026 revenue guidance ($450 to $500 million, not raised), not a price target of its own.
That is your call to make — this analysis gives no buy or sell recommendation. In Redwire's favor: the record quarter ($117.1 million of revenue, a record $542.1 million backlog) and the de-levered balance sheet; against it: internal control remains not effective ("no change," as of 06/30/2026) and the share count has grown roughly 30 percent since year-end 2025, to 249,992,609 shares as of 08/03/2026.
Not on common stock — every available dollar goes into growth, integration and debt paydown. The earlier recurring payout to holders of the Series A preferred stock is now gone entirely: that preferred stock was fully converted into common stock as of June 30, 2026, with zero outstanding.
Record-breaking on the surface, split at the core: $117.1 million of revenue (up 89.6 percent), 27.8 percent gross margin, and a record $542.1 million backlog — but essentially the entire positive result came from the acquired Defense Tech segment (positive $14.1 million Adjusted EBITDA), while the Space segment shrank slightly and slipped back to a segment-level loss at negative $4.2 million.
No. Redwire Corporation (Redwire Space) and SpaceX are two separate, independent companies with no capital or corporate tie. Name similarity and the spring 2026 rally around the SpaceX IPO hype caused confusion on forums and social media, but that changes nothing about either company's SEC filings.
Neither Redwire nor any analyst we reviewed offers a credible multi-year price range for 2030. The only reliably documented figure is the full-year 2026 revenue guidance affirmed after the second quarter ($450 to $500 million, not raised) — any number for 2030 would be pure extrapolation, not a fact drawn from the SEC filings.
At the close on August 7, 2026, the stock stood at $13.59 — after a cumulative gain of roughly 27 percent over two trading days following the August 5, 2026 Q2 results (prior close: $10.72). The 52-week high remains $26.64 (late May 2026), the low $4.87. As a daily price, that figure is already stale the day after publication — for context, annual and quarterly figures matter, not a single snapshot.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.