Oracle: $664 Billion on the Books — and Now Customers and Shareholders Pick Up the Bill
Updated October 3, 2026: Oracle's data center build-out is now funded mainly by customers, with $11.4 billion paid in advance, and by shareholders, with $19.9 billion from new shares — no new bonds in the quarter through August 2026. And both are now owed something.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 30, 2026
- Closing price
- 130.70 $ -6.40%
- Market Capitalisation
- 377.8 $B
- P/E
- 21.8
- Growth Score
- 5/10
- AAQS
- 7/10
Price change since October 2, 2026: -8.2%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 115.00 $ to 262.60 $ · Last price: 130.70 $ (As of: October 30, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
There is an investor trap that springs shut most reliably around very large numbers: the order book trap. It works because your brain files any figure preceded by the word “orders” as money. Oracle Corporation (NYSE: ORCL) reported remaining performance obligations of $638 billion for the fiscal year ended May 31, 2026, against $138 billion a year earlier. As of August 31, 2026, after the first quarter of the new fiscal year, the figure stands at $664 billion. Even annual revenue of $67.4 billion looks small next to it.
So let us make a deal before the number does its work. Together we will read what Oracle filed with the U.S. securities regulator, the SEC — the annual report (10-K) for fiscal 2026, the new quarterly report (10-Q) as of August 31, 2026, the earnings release of September 10, 2026, and everything filed since. Anyone who puts false statements in an SEC filing risks penalties. And these filings describe not just the order book but also $28.5 billion that flowed into data centers in three months, 141 million new shares, customers paying billions in advance, $288 billion of lease commitments that appear on no balance sheet line — and one sentence in the risk factors worth reading twice.
What has changed since July 26, 2026 — the first quarter of fiscal 2027
As of this update: October 3, 2026 (10-Q for the first quarter of fiscal 2027, earnings release and earnings call of September 10, 2026). Oracle calls the June-to-August 2026 quarter the “first quarter of fiscal 2027”. The first edition of this analysis on July 26, 2026 rested on the annual report for fiscal 2026; everything below has been brought up to date, while the annual figures remain those of fiscal 2026.
The business delivered. Revenue rose 30 percent to $19.345 billion in the quarter, after $14.926 billion a year earlier. Cloud infrastructure grew 121 percent to $7.388 billion, cloud applications 10 percent to $4.219 billion, and the classic software business shrank 3 percent to $5.550 billion. Operating income climbed 57 percent to $6.728 billion, an operating margin of 34.8 percent, and net income reached $4.760 billion or $1.56 per diluted share, after $1.01. For all of fiscal 2027 Oracle now expects revenue of at least $90 billion, up 34 percent — in June the company had guided to $90 billion, now the figure is explicitly a floor — and raised its non-GAAP earnings outlook from $8.05 to $8.10 per share.
The order book keeps growing, but more slowly. Remaining performance obligations rose to $664 billion, $26 billion more than as of May 31, 2026 and $209 billion more than a year earlier. Oracle expects to recognize roughly 13 percent of that as revenue over the next twelve months, 37 percent in months 13 through 36 and 34 percent in months 37 through 60. The earnings release adds a sentence worth knowing:
“Oracle booked more than $30 billion of additional AI cloud contracts in Q1 increasing its RPO to $664 billion. Based on the structuring of those new contracts, the Company confirms there is no incremental impact on its plans to raise capital.”
— Oracle Corporation, earnings release dated September 10, 2026, Exhibit 99.1 to the SEC current report 8-K
What “structuring of those contracts” means, CFO Hilary Maxson explained on the earnings call that same evening, according to the transcript by The Motley Fool dated September 11, 2026: most of the new contracts run through prepayment, through hardware the customer brings itself, or similar mechanisms — and will drive capital spending and revenue only from fiscal 2028 onward. Which brings us to the real finding of this quarter.
Now somebody else is paying the bill. In fiscal 2026 the money for the build-out came mainly from the bond market: $43.0 billion of new senior notes. In the first quarter of fiscal 2027 Oracle did not issue a single new note. That was the announced plan: with its annual results on June 10, 2026, Oracle said it expected to raise approximately $40 billion in fiscal 2027 through a combination of debt and equity, including the $20 billion at-the-market program, and did not expect to issue additional debt in calendar 2026; the September release confirms that the new contracts do not change those plans. On paper, roughly $20 billion of that plan remains after the exhausted equity program. Instead, $11.363 billion came in as customer prepayments and $19.9 billion from selling new shares. The quarterly report records the prepayments like this:
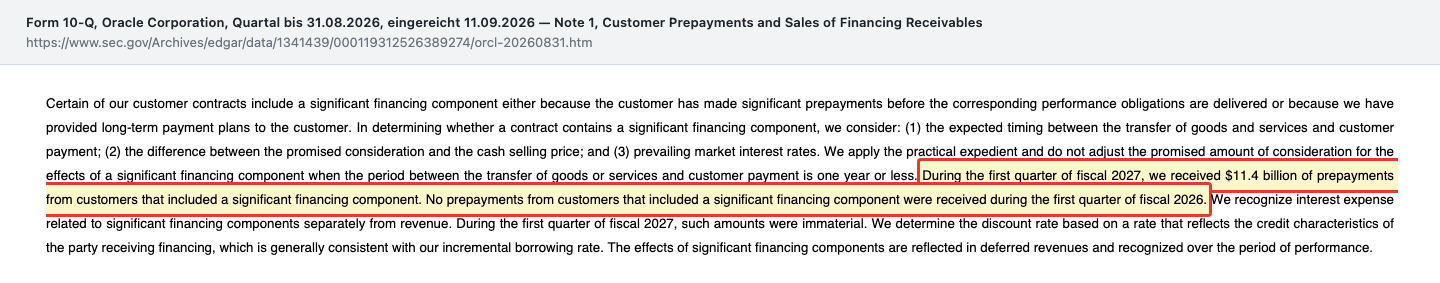
“During the first quarter of fiscal 2027, we received $11.4 billion of prepayments from customers that included a significant financing component. No prepayments from customers that included a significant financing component were received during the first quarter of fiscal 2026.”
— Oracle Corporation, SEC quarterly report 10-Q as of August 31, 2026, Note 1 (Customer Prepayments and Sales of Financing Receivables)
That changes how to read the record operating cash flow. Oracle reports $23.103 billion for the quarter, up 184 percent. Almost half of it is customer prepayments. Without them, operating cash flow would have been roughly $11.7 billion — still 44 percent above the $8.140 billion of the prior-year quarter, but a completely different order of magnitude. Capital expenditures reached $28.499 billion, more than in any earlier quarter. Free cash flow was therefore minus $5.396 billion; without the prepayments it would have been roughly minus $16.8 billion. Deferred revenues on the balance sheet — money for which Oracle still owes the service — doubled in three months from $15.395 billion to $30.789 billion.
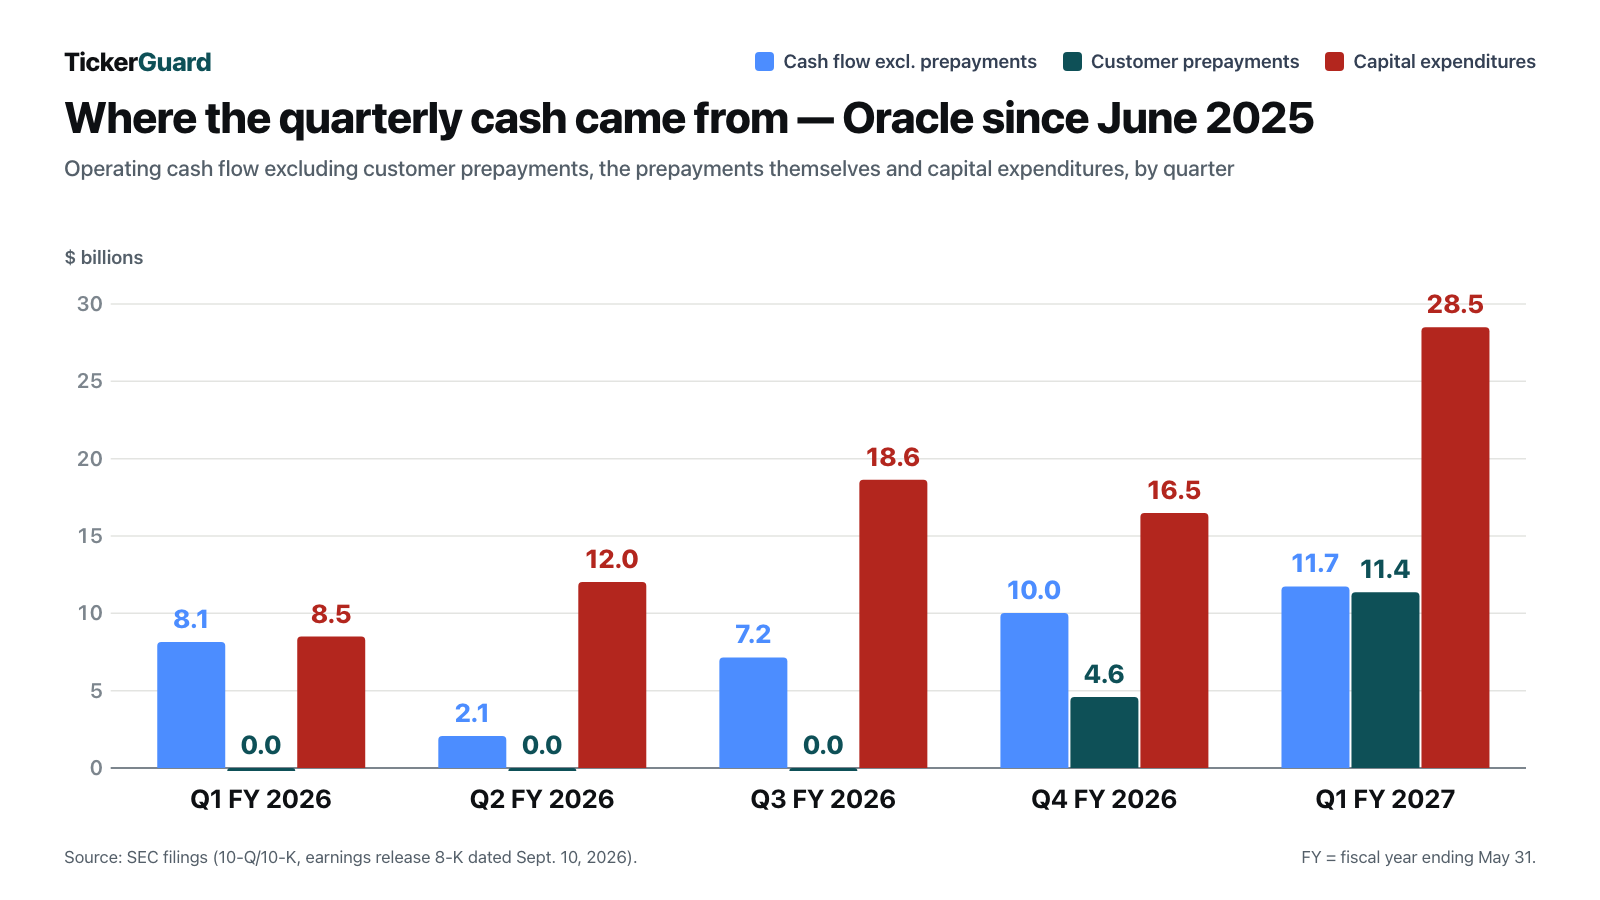
The five quarters since June 2025 side by side, rounded, in billions of dollars: operating cash flow excluding prepayments 8.1 · 2.1 · 7.2 · 10.0 · 11.7, customer prepayments 0 · 0 · 0 · 4.6 · 11.4, capital expenditures 8.5 · 12.0 · 18.6 · 16.5 · 28.5. Own cash flow reached its highest value of the series in the latest quarter; capital spending rose even more.
The second source of money is shareholders. The program allowing Oracle to sell up to $20 billion of stock into the market, in place since February 2, 2026, was untouched as of May 31, 2026. Three months later it is empty:
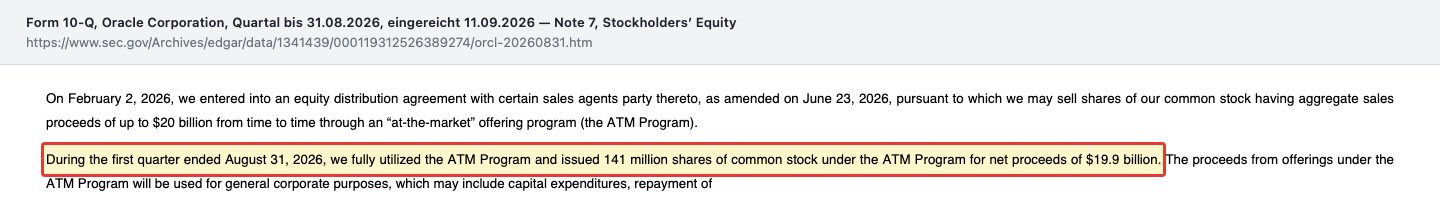
Shares outstanding rose to 3,031,501,149 (as of September 21, 2026, per the proxy statement), roughly 5 percent more than the 2,880,471,000 of June 12, 2026. Stockholders’ equity grew from $43.056 billion to $67.196 billion, the equity ratio from 16.4 to 22.2 percent. Debt edged down through repayments — $3.1 billion scheduled, $1.1 billion of commercial paper — from $129.5 billion to $125.3 billion. The balance sheet has broadened, then — but not because the build-out pays for itself; shareholders and customers put in more money.
The plan for fiscal 2027 remains enormous. On the earnings call the CFO confirmed the capital spending range. We quote here from the transcript by The Motley Fool dated September 11, 2026, not from an SEC document:
“We continue to anticipate $90 billion to $95 billion in CapEx for the full year with not more than $70 billion in net cash CapEx.”
— Hilary Maxson, Chief Financial Officer, earnings call of September 10, 2026 (transcript: The Motley Fool, September 11, 2026)
That would be 62 to 71 percent more than the $55.663 billion of fiscal 2026. At Oracle, “net cash CapEx” means capital expenditures less customer prepayments, adjusted for short-term financing related to capital expenditures — $17.966 billion in the first quarter according to Oracle’s own reconciliation ($28.499 billion of capex minus $11.363 billion of prepayments plus $0.830 billion of short-term financing repaid). Asked by Brad Zelnick (Deutsche Bank) when free cash flow would turn positive again, Maxson answered, per the same transcript: “We have not given a particular time frame on that.” — no date would be given; each individual data center project, however, generates strong free cash flow once it has ramped. She called the decline in gross margin expected and attributed it to the ramp of new data centers and the fast-growing share of the lower-margin infrastructure business. The quarterly report itself states that capital expenditures in fiscal 2027 will be higher than in fiscal 2026.
What was added off the balance sheet. Lease commitments for data centers whose lease terms have not yet begun rose in three months from $260 billion to $288 billion. Unconditional purchase and certain other obligations — mostly components for cloud infrastructure and power supply — total $34.150 billion, after $13.309 billion as of May 31, 2026. The guarantee for a lessor named in the annual report no longer appears — more on that in uncomfortable truth No. 2.
What the founder and insiders did. Lawrence J. Ellison, executive chair, chief technology officer and, at 38.2 percent, the largest shareholder, adopted a trading plan on June 22, 2026 permitting the sale of up to 50 million Oracle shares. It was disclosed in the quarterly report of September 11, 2026; on September 12, 2026 Oracle announced that Ellison had cancelled it — according to the current report of September 14, 2026, without a single share sold under it; he has no other plans to sell, the release added. The proxy statement of September 25, 2026 also lists 413 million shares that Ellison had pledged as collateral for personal loans as of September 21, 2026 — after 346 million a year earlier. Co-CEO Michael D. Sicilia sold 10,882 shares at $139.94 (September 16) and 22,562 shares at $151.59 (September 22) in September 2026 under a trading plan adopted back on December 24, 2025. On the other side, director Stephen H. Rusckowski bought 25,000 shares at roughly $139.35 each on September 29, 2026.
Our reading of the quarter in one sentence: the order book is turning into revenue, with 30 percent growth in the quarter — but the build-out is now pre-financed to a large extent by customers and co-funded by shareholders, and both are owed something in return. Customers are owed service that Oracle must deliver over years. Shareholders now hold a smaller slice of future profit. That is no alarm, but it is a different bet than in July.
Company history for investors
-
2006
New corporate shell in Delaware
Today's Oracle Corporation was named Ozark Holding Inc. until February 1, 2006 — for shareholders a change of domicile, not a change of ownership.
-
2025
Sale of the Ampere stake
On November 25, 2025 SoftBank acquires Ampere Computing; Oracle receives $4.3 billion in cash — for shareholders a one-time gain of $2.7 billion in fiscal 2026.
-
2026
Preferred stock and a $20 billion equity program
In February 2026 Oracle raises $5.0 billion through mandatory convertible preferred stock and sets up a program to sell up to $20 billion of shares — the basis for later share issuance.
-
2026
Fiscal year with a $638 billion order book
As of May 31, 2026, $638 billion of remaining performance obligations stand against free cash flow of minus $23.686 billion — for shareholders the moment the bet becomes visible.
-
2026
Program used up, customers pay in advance
In the quarter ended August 31, 2026 Oracle sells 141 million new shares for $19.9 billion and receives $11.4 billion of customer prepayments — the funding mix shifts.
What Oracle actually does — the database and the power plant
Oracle sells two very different things, and the difference explains almost everything that follows. The first is a memory: the Oracle database, where banks, insurers, government agencies and corporations keep their data, plus enterprise software for accounting, human resources and supply chains. This business is old, sticky and wonderfully predictable. Once your accounting runs on Oracle, you do not switch on a whim. The maintenance contracts attached to it — “software support” in the filing — brought in $19.804 billion in fiscal 2026 and grew by exactly one percent. Dull, but as reliable as rent.
The second is a power plant: Oracle Cloud Infrastructure, or OCI. Here Oracle rents out computing capacity — servers, graphics processors, storage, networking — on which other companies run their software and their artificial intelligence. This business is young, hungry, and grew 77 percent to $18.101 billion in fiscal 2026 and 121 percent in the first quarter of fiscal 2027. The difference from the memory business is the decisive one: a database license costs Oracle almost nothing to produce. A data center costs billions before the first customer pays a cent.
In between sit cloud applications ($15.888 billion, up 11 percent), traditional software licenses ($4.737 billion, down 9 percent), hardware ($3.084 billion) and consulting services ($5.743 billion). All told, 51 percent of fiscal 2026 revenue came from the cloud, against 43 percent a year earlier and 37 percent two years before that; in the first quarter of fiscal 2027 it was 60 percent. The company is headquartered in Austin, Texas, employed roughly 141,000 people full time as of May 31, 2026 — 43,000 of them in research and development — and spent $10.272 billion on that development.
Which names the central tension of this analysis, and it runs through every chapter: Oracle is using yesterday’s certain money to fund a bet on the day after tomorrow — and has to pay the bill right away.
How the stock reached our desk — rank 20 among turnaround candidates
We run roughly 3,500 stocks through our scanners every day. On July 25, 2026, Oracle stood at rank 20 of 62 hits in the Turnaround Candidates list (U.S. selection), with a turnaround check of 6 of 8 points. To reproduce it: open the scanner, set the country filter to “US”, and sort by the turnaround check column.
And now the sentence that has to come first with a name like this: a company then worth $331 billion does not normally belong on a restructuring list. Oracle was not there because the business was ailing. Oracle was there because the scanner does not read names — it tests two mandatory conditions, and both are purely arithmetic.
Mandatory pillar 1 — the crash. The stock must trade at least 50 percent below its all-time high. Without a real decline there is no turnaround; otherwise the list simply catches ordinary growth stocks. Oracle’s highest closing price was $328.33 on September 10, 2025. On July 24, 2026 the stock closed at $114.99 — 64.98 percent below that. Run it the other way and you see how narrow such a list is: if the price rises above roughly $164, it is no longer 50 percent down — and Oracle drops out of the scanner. September 8, 2026 showed how close that can get: a close of $162.52, just 50.5 percent below the peak. On October 2, 2026 the stock was 56.7 percent below it again at $142.30.
Mandatory pillar 2 — survival. The Altman Z-score, a well-established bankruptcy early-warning measure built from balance sheet ratios, has to sit outside the danger zone; our threshold is 1.1. One point belongs at the very front here, because the rest of the chapter only reads correctly with it: our data set does not carry the original formula but the book-value variant, Altman Z″ — four ratios, a fixed constant of 3.25, and no market-capitalization block. On that scale the distress zone starts below 1.1 and the safe zone begins at 2.6; the textbook figures of 1.8 and 3.0 belong to the original formula and do not apply here. Oracle sat at 4.14 in the data set (as of July 27, 2026), with quarterly readings between 2.77 and 3.88 since early 2025. The pillar was therefore not barely met, it was met comfortably.
The cross-check is still worth running, and it is the most honest finding in this chapter. Recomputed with the original formula and its five building blocks (as of July 25, 2026), Oracle comes out at 1.43. Almost the entire difference sits in one block: market capitalization relative to total liabilities. In that calculation it contributes 0.91 of the 1.43 points, roughly 64 percent; strip it out and 0.52 is left from the balance sheet alone. Translated: under the original formula, Oracle’s measured distance from insolvency would hang two thirds on its own share price. That feedback loop is exactly what the Z″ variant we carry avoids: its reading moves with the balance sheet, not with the quote. There is therefore no price level below which Oracle would drop out of the scanner “from below”. Remember the principle: mix up two Altman variants and the same balance sheet reads once as a shaky candidate and once as a solid company.
Only after that does the turnaround check apply, a checklist of eight points. Four test the operating turn — revenue direction, net margin, operating cash flow, a healing balance sheet — and four test market confirmation: price back above the 50-day line, three-month relative strength above twelve-month, insiders buying on balance, large funds adding. To appear at all, a stock must clear both mandatory pillars and score at least six of the eight points.
Three of the operating points could be recalculated straight out of the annual report, and they were real. Revenue in the quarter ended May 31, 2026 was $19.184 billion, up 20.6 percent year over year. The net margin rose to 22.4 percent, from 19.6 percent three quarters earlier and 21.6 percent in the prior quarter. And operating cash flow for that quarter was clearly positive at $14.620 billion. One point from the market block, on the other hand, was demonstrably missing: at $114.99 on July 24, 2026 the price sat well below the 50-day line of $171.55 — and below the 200-day line of $187.40 as well.
Remember the principle, it applies to every ranking: a rank and a score are a photograph, not a condition. The lists are recalculated daily. What the scanner measures is the direction of a few quarters. Whether the bet holds is decided in the filings. The scanner figures in this chapter — rank, turnaround check, moving averages, Altman scores — therefore deliberately show the July 2026 snapshot from when Oracle landed on our desk; everything that follows is updated to October 3, 2026. So let us read the filings.
The numbers over the years — given their due
First what genuinely impresses, and there is plenty. In fiscal 2019 Oracle booked $39.506 billion of revenue. In fiscal 2026 it was $67.357 billion — up 70 percent in seven years, and up 17.3 percent in the last year alone. Operating income rose from $13.535 billion to $20.606 billion, an operating margin of 30.6 percent. Net income came in at $17.087 billion, or $5.83 per diluted share, against $4.34 a year earlier. This is not a distressed company. This is a company with the highest revenue and operating income of all the years shown here — and the first quarter of fiscal 2027 picked up the pace further with 30 percent revenue growth.
The cash side was strong too: operating cash flow rose 54 percent to $31.977 billion — 1.87 times net income. A company that collects more cash than it books in profit generally has a clean income statement. And then comes the other side of the page.

Capital expenditures — almost entirely data centers — rose from $6.866 billion in fiscal 2024 to $21.215 billion in 2025 and $55.663 billion in fiscal 2026. That is an eightfold increase in two years. The two series for the past five fiscal years side by side, rounded, in billions of dollars: operating cash flow 9.5 · 17.2 · 18.7 · 20.8 · 32.0, capital expenditures 4.5 · 8.7 · 6.9 · 21.2 · 55.7. Through 2024 the inflow was far larger than the spending, in 2025 the two were level, and in 2026 the relationship inverted. The balance sheet shows the same move: net property, plant and equipment grew from $43.522 billion to $99.957 billion as of May 31, 2026 and on to $127.845 billion as of August 31, 2026. Oracle is building at a pace that has nothing to do with the classic software business.
What the filings say — the uncomfortable truths
Uncomfortable truth No. 1: free cash flow has flipped
Subtract $55.663 billion of capital expenditures from $31.977 billion of operating cash flow and you get free cash flow — the money left over after maintaining and expanding the business. Oracle presents the calculation itself in the annual report and arrives at minus $23.686 billion, after minus $0.394 billion a year earlier. As a percentage of net income: minus 139 percent. For six years that figure had been comfortably positive: in billions of dollars it ran plus 12.9 (fiscal 2019), plus 11.6 (2020), plus 13.8 (2021), plus 5.0 (2022), plus 8.5 (2023) and plus 11.8 (2024), before edging negative at minus 0.4 in 2025 and collapsing to minus 23.7 in 2026. The first quarter of fiscal 2027 added minus $5.396 billion — and only that little because customers paid $11.363 billion in advance.

Important for fairness: this is not cash burn in the usual sense. Oracle earns very well operationally and is spending that money, plus outside money, on assets that will be usable for decades. The annual report was already clear in June that it continues, and the quarterly report of September 11, 2026 repeats it — capital expenditures in fiscal 2027 will be higher than in fiscal 2026:

A line worth filing away: profit tells you how the books were kept. Free cash flow tells you who is fronting the money. In fiscal 2026 it was mainly the bond market: $42.7 billion net from new senior notes, $5.0 billion from preferred stock, $4.9 billion from selling investments, $3.3 billion of short-term financing related to capital expenditures, and $1.3 billion net from employee stock programs. In the first quarter of fiscal 2027 customers and shareholders fronted it — $11.363 billion of prepayments and $19.909 billion net from new shares.
Uncomfortable truth No. 2: $288 billion of rent appears on no balance sheet line
This is the finding that stays with you longest. When a company leases something, accounting rules now require the lease obligation to appear on the balance sheet — as a right-of-use asset on one side and a liability on the other. Oracle does that: $34.621 billion of operating and $9.185 billion of finance lease liabilities sat on the balance sheet as of August 31, 2026. But the requirement only bites once the lease term has commenced. And then this paragraph appears in the notes to the annual report:

Three months later, the same place in the quarterly report shows a larger number:
“As of August 31, 2026, we had $288 billion of additional lease commitments, substantially all related to data center arrangements, that are generally expected to commence between the second quarter of fiscal 2027 and fiscal 2029 and for terms of fifteen to nineteen years that were not reflected on our condensed consolidated balance sheets as of August 31, 2026 or in the maturities table above.”
— Oracle Corporation, SEC quarterly report 10-Q as of August 31, 2026, Note 6 (Leases and Other Commitments)
Take a moment for the scale. Oracle’s entire balance sheet on the same date totaled $303.259 billion. The lease commitments not yet on it total $288 billion — 95 percent of that. There is, in effect, a second balance sheet standing beside the first one, invisible, with terms of fifteen to nineteen years. That is entirely correct accounting and openly disclosed — but anyone who looks only at the leverage ratio is seeing half the picture.
One detail from the annual report no longer appears in the quarterly report: there Oracle had guaranteed up to $3.3 billion of a lessor’s borrowing under one of these leases, borrowing that matures in September 2026 — in the quarterly report as of February 28, 2026 it had been up to $2.2 billion. The quarterly report as of August 31, 2026 no longer mentions that guarantee. What became of it, the filing does not say — and the two current reports (8-K) of September 10 and 14, 2026 mention neither the guarantee nor the landlord loan. No filing since then says whether the loan was repaid, extended or refinanced.
Uncomfortable truth No. 3: the order book is a concentration, not a certainty
Now to the headline number. Remaining performance obligations are the total of all contracted services that have not yet been recognized as revenue. They rose from $138 billion (May 31, 2025) through $552.6 billion (February 28, 2026) to $638 billion as of May 31, 2026 and on to $664 billion as of August 31, 2026.

Two details deserve more attention than the size itself. First, the wording: the increase is attributed to “certain significant cloud contracts”; the quarterly report of September 11, 2026 repeats that phrase verbatim. How many contracts, and with whom, none of the filings says. Second, the schedule: as of August 31, 2026 Oracle expects to recognize roughly 13 percent of the order book as revenue over the next twelve months, 37 percent in months 13 through 36, another 34 percent in months 37 through 60, and the remainder after that. So 87 percent lies beyond the coming year, and roughly a sixth beyond five years.
The good news is in the notes to the annual report: “No single customer accounted for 10% or more of our total revenues in fiscal 2026, 2025 or 2024.” The uncomfortable news sits many pages earlier, in the risk factors, and it is the sentence worth reading twice:
“Conversely, if we overestimate customer demand or any of our key customers are unable to pay or otherwise perform under their contracts with us, we could be locked into multi-year commitments for excess data center space and related capital expenditures, as well as associated financings, without receiving corresponding revenue. … In certain OCI offerings, we are more concentrated among a number of large customers, which could increase these risks.”
— Oracle Corporation, SEC annual report 10-K for fiscal 2026, Item 1A (Risk Factors)
That is the whole bet in one sentence, written by the company itself, and the quarterly report explicitly refers back to that annual report for its risks. Oracle leases data centers for fifteen to nineteen years and finances them with notes maturing in 2066, with new shares and with money customers wire in advance. The customers meant to absorb that capacity are few and large. Remember: an order book measures what somebody promised — not what they can pay for next year. The prepayments soften that sentence somewhat, because whoever pays in advance has already proved they can pay for that part. We saw the same mechanism at the other end of the chain in our Nvidia analysis, where demand for graphics processors comes from the same handful of addresses.
Uncomfortable truth No. 4: $125 billion of debt — valued by the bond market at 85 cents on the dollar
Debt rose from $92.6 billion (May 31, 2025) to $129.5 billion (May 31, 2026). In fiscal 2026 alone Oracle issued $43.0 billion of new senior notes across fourteen tranches — from 4.45 percent for five years to 6.85 percent for forty years, maturing in February 2066. No new notes were added in the first quarter of fiscal 2027; after $3.1 billion of scheduled debt repayments and $1.1 billion of commercial paper repaid, $125.3 billion remained on the balance sheet as of August 31, 2026. Interest expense rose 29 percent to $4.599 billion in fiscal 2026 and 55 percent to $1.428 billion in the first quarter of fiscal 2027. Measured against operating income over the last four quarters of $23.057 billion and interest expense over the same period of $5.104 billion, interest coverage is roughly 4.5 times — adequate, but a long way from the comfort of earlier years.

And now the figure that makes no headlines but says more about the situation than any price target. As of August 31, 2026 the notes give a carrying value of $125.0 billion for the long-term borrowings — and a fair value of $105.7 billion. The bond market therefore valued Oracle’s debt at roughly 85 cents on the dollar. As of May 31, 2026 it was $114.4 billion against $128.1 billion, roughly 89 cents; as of May 31, 2025 $81.3 billion against $90.3 billion, about 90 cents. Part of that discount is a rate effect — older notes with low coupons lose value when market rates rise. But it may also be a verdict — and the ratio fell in the first quarter of fiscal 2027 even though Oracle added $19.9 billion of equity in that period. Professional creditors are paying less than face value for Oracle’s promises.
Fairness here means saying that the company is not under pressure. According to the annual report, as of May 31, 2026 it had an undrawn $10 billion revolving credit facility and a $10 billion commercial paper program, and it stated explicitly: “We were in compliance with all debt-related covenants at May 31, 2026.” As of August 31, 2026, $37.077 billion sat in cash and marketable securities. Near-term maturities are manageable: $7.210 billion in fiscal 2027, $10.145 billion the year after. The mountain sits far out: $90.250 billion falls due only after fiscal 2031 (all maturities as of May 31, 2026).
Uncomfortable truth No. 5: part of the record profit was one-time — and part of the cash belongs to customers
Two items you need to know to read the record numbers correctly. The first sits in fiscal 2026 non-operating income, which jumped from $60 million in fiscal 2025 to $3.547 billion. The reason is a sale. On November 25, 2025, SoftBank acquired all equity interests in chip developer Ampere Computing; Oracle received $4.3 billion in cash and recorded a realized gain of $2.7 billion. That is real money and entirely legitimate — but it does not come back. Of the $4.644 billion increase in net income, well over half traces to this single transaction. Operating income over the same period rose “only” from $17.678 billion to $20.606 billion. Oracle itself points out in the earnings release of September 10, 2026 that non-GAAP earnings per share in the second quarter of fiscal 2027 are therefore expected to fall 14 to 18 percent below the prior-year quarter; excluding the Ampere effect, the company expects growth of 21 to 25 percent.
The second item sits in the revenue recognition note and is now the larger one. In fiscal 2026 Oracle received $4.6 billion of prepayments from customers that included a significant financing component — and in the first quarter of fiscal 2027 alone $11.4 billion. In fiscal 2025 and 2024 there were no such payments at all. Translated: customers paid so far ahead of delivery that the accounting identifies what is economically a loan. The money is real and sits in operating cash flow. It is simply money for services Oracle still has to deliver — deferred revenues, long-term and short-term, stood at $30.789 billion as of August 31, 2026. Without those prepayments, operating cash flow would have been roughly $27.4 billion instead of $31.977 billion in fiscal 2026, and roughly $11.7 billion instead of $23.103 billion in the first quarter of fiscal 2027.
A third pointer in the same direction: the share repurchase, for years an Oracle hallmark, has stopped. In fiscal 2026 the company bought back 0.4 million shares for $93 million — after 3.9 million shares for $600 million (2025) and 10.6 million for $1.2 billion (2024); in the first quarter of fiscal 2027, none at all. For comparison: in fiscal 2019, fundamental data show more than $36 billion of net spending on own shares. Roughly $6.3 billion of authorization remains. The dividend, by contrast, is unchanged: $2.00 per share in fiscal 2026, $5.7 billion in total, and another $0.50 per quarter declared in September 2026.
On top of that come two funding routes that did not exist until early 2026. On February 5, 2026, Oracle issued 100 million depositary shares representing 50,000 Series D preferred shares carrying a 6.50 percent dividend, raising $5.0 billion net; they convert automatically into common stock on January 15, 2029 at 499.8126 to 624.7657 shares per preferred share. Work out the upper bound and you have the conversion floor: only below roughly $160 per common share do preferred holders receive the maximum share count — and even then, less value than they paid in. And on February 2, 2026, Oracle set up a program allowing it to sell common stock worth up to $20 billion into the market over time. Not a single share had been sold under it as of May 31, 2026, on June 23, 2026 the syndicate of appointed banks was expanded from 15 to 20 — and by August 31, 2026 the entire facility had been used with 141 million new shares.
Valuation — what the market is paying right now
Let us work in orders of magnitude rather than daily prices. At the October 2, 2026 close of $142.30 and 3,031,501,149 shares (proxy statement, as of September 21, 2026), market capitalization was roughly $431 billion. Against diluted earnings over the last four quarters of $6.38 per share that is a price-to-earnings ratio of about 22; against revenue over the same four quarters of $71.776 billion, a price-to-sales ratio of about 6.0; against equity of $67.196 billion, a price-to-book ratio of about 6.4. Adding net debt of roughly $88 billion, enterprise value comes to roughly $520 billion. For reference to the first edition: at the close on Friday, July 24, 2026, the price was $114.99, market capitalization roughly $331 billion and the P/E about 20. Since then the price has risen by just under 24 percent, but the trailing four-quarter P/E only to about 22, because earnings grew too.
For a software heavyweight with a 34.8 percent operating margin in the latest quarter, twenty-two times earnings is not an exotic price. The catch lies elsewhere: earnings over the last four quarters still include the one-time Ampere effect, and the capital that produces them is growing faster than the profit. The 141 million new shares alone spread every future dollar of profit across roughly 5 percent more holders, and the notes and preferred shares from fiscal 2026 demand interest and preferred dividends — in the first quarter of fiscal 2027 that was $1.428 billion of interest and $81 million of preferred dividends.
The professionals’ view, put in context: across 43 analyst ratings the consensus price target was $237.97 (data as of October 2, 2026), with 27 strong buy and 8 buy ratings, 7 holds and one strong sell. At the end of July the consensus target was $248.15 from 39 ratings — the target has edged down since, while the share price has risen. The number is best read not as a forecast but as the mood of a profession. For a cross-check on another badly beaten enterprise software name from the same scanner list, see our ServiceNow analysis.
One footnote that belongs in the picture: as of October 2, 2026 roughly 50.8 million shares were sold short, up from 47.8 million a month earlier — roughly 1.7 percent of shares outstanding. And since February 3, 2026 a shareholder class action has been pending in Delaware against Oracle, its chief technology officer, one of its two chief executive officers, two further executives and one board member over allegedly false statements about the cloud infrastructure business; the complaint was amended on July 14, 2026. The defendants had to respond by September 16, 2026; if they move to dismiss, briefing on that motion is to be completed by December 18, 2026. Oracle believes it has meritorious defenses and does not expect a material impact.
Opportunities and risks at a glance
Opportunities
- $664 billion of remaining performance obligations as of August 31, 2026 — contracted revenue that maps out several years of growth if performed as agreed; Oracle expects roughly $86 billion of it over the next twelve months.
- Cloud infrastructure growing 121 percent to $7.388 billion in the quarter ended August 31, 2026; the company’s own outlook for fiscal 2027 calls for revenue of at least $90 billion.
- The old business still carries: $19.804 billion of support revenue in fiscal 2026 with a high renewal rate funds a meaningful part of the build-out.
- Customers pay in advance: $11.4 billion of prepayments in the first quarter of fiscal 2027 reduce the capital requirement and, for that portion, prove the large customers can pay.
- Broader balance sheet: $67.196 billion of equity and $37.077 billion of cash and securities as of August 31, 2026; per the annual report an undrawn $10 billion revolver and all debt covenants met as of May 31, 2026.
Risks
- Capital spending of $90 billion to $95 billion planned for fiscal 2027 (per the earnings call transcript); free cash flow was minus $5.396 billion in the first quarter and roughly minus $16.8 billion excluding customer prepayments — management gave no date for the turn on the call.
- $288 billion of off-balance-sheet lease commitments with terms of fifteen to nineteen years, plus $34.150 billion of unconditional purchase and certain other obligations — both as of August 31, 2026.
- $125.3 billion of debt maturing out to 2066 and 55 percent more interest expense in the quarter; the bond market valued the long-term borrowings at roughly 85 cents on the dollar as of August 31, 2026.
- Concentration among a few large customers in parts of the cloud infrastructure business — by Oracle’s own account in the risk factors; if one falls away, the leases and their financing keep running.
- Dilution: 141 million new shares in the first quarter of fiscal 2027, plus the mandatory conversion of the preferred shares on January 15, 2029.
- An encumbered major shareholder: 413 million of the founder’s shares were pledged as loan collateral as of September 21, 2026, after 346 million a year earlier. According to the proxy statement, the governance committee does not consider this a material risk, in part because Ellison could repay the loans without recourse to the pledged shares.
A human conclusion
Back to the order book trap from the opening. It works so well precisely because it does not rest on a lie. The $664 billion are real, they sit in a filing whose accuracy the two chief executives and the CFO personally certify, and they are the result of contracts somebody signed. The error is not in the number but in what our minds automatically turn it into: a bank balance.
In the first edition of this analysis we gave you four numbers to check in the next quarterly report. Here are the answers. The order book kept growing, from $638 billion to $664 billion. Capital expenditures did not merely stay elevated, they rose to $28.5 billion in a single quarter. The $3.3 billion guarantee no longer appears in the filing. And the $20 billion program was not merely tapped — it was used up entirely. What Oracle did in the first quarter of fiscal 2027 can therefore be put like this: the company accelerated the build-out and shifted the bill from bondholders to customers and shareholders.
That may prove to be a very good corporate decision — whoever pays up front believes in the service, and whoever buys new shares believes in the company. It may also be the moment a software house listed for decades became, once and for all, a landlord of data centers, with everything that entails: leases of fifteen to nineteen years, customers who are owed service, and notes that come due in 2066.
Which of the two stories is true, nobody can know for sure today. What you can do instead is keep counting. For the next quarterly report, covering the quarter ending November 30, 2026, these are the four numbers: how much comes in again as customer prepayments? Where do the off-balance-sheet lease commitments stand? How much operating cash flow is left without prepayments? And how does the bond market value the debt? Each of them costs you five minutes.
What you make of that is your decision. And that is exactly as it should be.
Sources
- SEC quarterly report 10-Q, Oracle Corporation, first quarter of fiscal 2027 (ended August 31, 2026), filed September 11, 2026 (Notes 1, 2, 3, 5, 6, 7 and 11, Item 2 MD&A, Item 5)
- SEC current report 8-K dated September 10, 2026 (Item 2.02 quarterly results, Item 8.01 dividend declaration) with the earnings release, Exhibit 99.1
- SEC current report 8-K dated September 14, 2026 (Item 8.01, cancellation of Lawrence J. Ellison’s trading plan)
- SEC proxy statement DEF 14A dated September 25, 2026 (share ownership and pledging as of September 21, 2026) and DEF 14A dated September 26, 2025 (pledging as of September 19, 2025)
- Earnings call of September 10, 2026, transcript by The Motley Fool dated September 11, 2026 (third-party transcript)
- SEC annual report 10-K, Oracle Corporation, fiscal year ended May 31, 2026, filed June 22, 2026 (Item 1 Business, Item 1A Risk Factors, Item 7 MD&A, Notes 1, 3, 6, 9, 10 and 15)
- SEC quarterly report 10-Q, Oracle Corporation, as of February 28, 2026, filed March 11, 2026
- SEC annual report 10-K, Oracle Corporation, fiscal year ended May 31, 2025, filed June 18, 2025
- SEC prospectus supplement 424B5 dated June 23, 2026 (equity distribution program of up to $20 billion, additional sales agents) and prospectus supplement 424B5 dated February 3, 2026 (ten additional sales agents)
- SEC current report 8-K dated June 10, 2026 (quarterly and annual results, fiscal 2027 financing plan, dividend declaration, listing of the ORCL-PRD depositary shares)
- Insider filings (Form 4) on Oracle through October 1, 2026, including Stephen H. Rusckowski’s purchase of September 29, 2026 — via the SEC submissions index for CIK 0001341439 (former names, exchanges, filing history; as of October 3, 2026)
- Screening and metric data: our in-house stock scanner (data as of July 25, 2026), including the Turnaround Candidates scanner (U.S. selection, rank 20 of 62, turnaround check 6 of 8) — the lists are recalculated daily.
- Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q); price, valuation and analyst data as of October 2, 2026 (data date of the first edition: July 25, 2026).
Journalistic analysis, not investment advice and not a solicitation to buy or sell securities. Stocks can lose their entire value. All figures come from the original sources linked above and carry their respective as-of dates; metrics may have changed since the data date. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this deep dive.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2022 | 2023 | 2024 | 2025 | 2026 |
|---|---|---|---|---|---|
| Revenue | 42,440.0 | 49,954.0 | 52,961.0 | 57,399.0 | 67,358.0 |
| Operating Income (EBIT) | 10,926.0 | 13,093.0 | 15,353.0 | 17,678.0 | 20,778.0 |
| Net Income | 6,717.0 | 8,503.0 | 10,467.0 | 12,443.0 | 17,087.0 |
| Net Margin | 15.8% | 17.0% | 19.8% | 21.7% | 25.4% |
| Earnings Per Share | 2.41 $ | 3.07 $ | 3.71 $ | 4.34 $ | 5.86 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
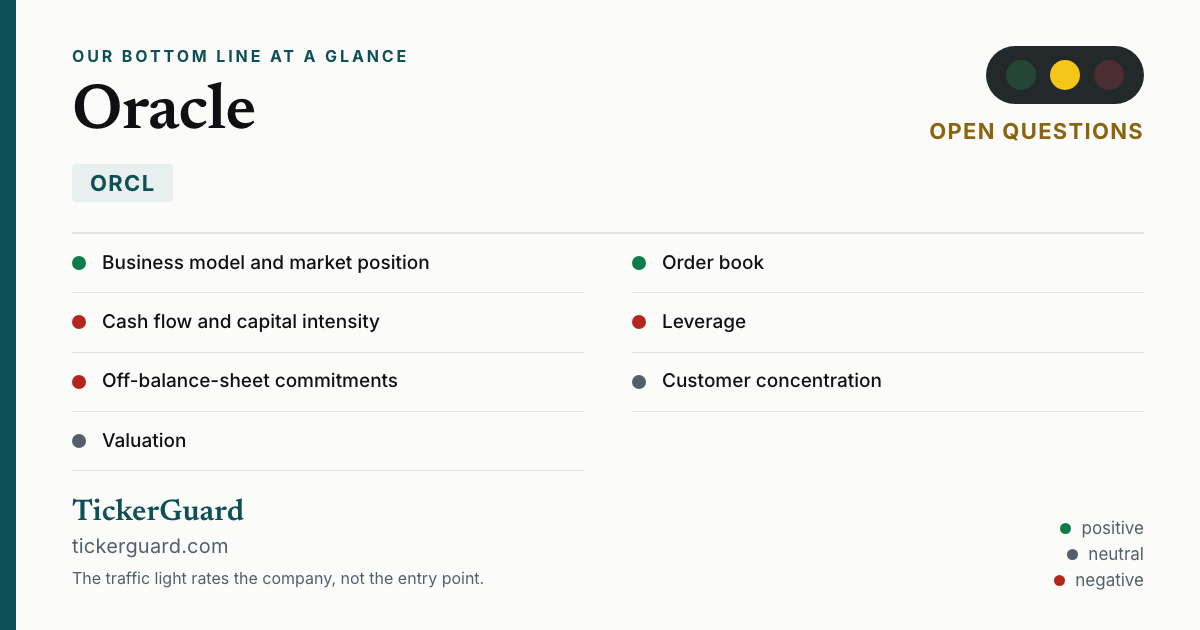
Our Bottom Line at a Glance
- Business model and market position positive
- Oracle sells the database a large part of the corporate world runs on, plus applications and, more recently, cloud computing capacity. In the first quarter of fiscal 2027 (June through August 2026) revenue rose 30 percent to $19.345 billion, cloud infrastructure rose 121 percent to $7.388 billion, and the operating margin was 34.8 percent.
- Order book and customer concentration neutral
- Remaining performance obligations rose to $664 billion as of August 31, 2026, from $455 billion a year earlier. Even the expected 13 percent for the next twelve months equals roughly $86 billion — more than all of fiscal 2026 revenue. No single customer reached 10 percent of revenue through 2026; at the same time Oracle cites a concentration among a number of large customers in parts of its cloud infrastructure business in its risk factors.
- Cash flow and capital intensity negative
- In the first quarter of fiscal 2027, $28.499 billion went into property, plant and equipment, and the CFO cited $90 billion to $95 billion for the full fiscal year, according to the earnings call transcript. Free cash flow was minus $5.396 billion — without $11.363 billion of customer prepayments it would have been roughly minus $16.8 billion. Management gave no date on the call for free cash flow turning positive again.
- Funding and leverage negative
- Debt edged down to $125.3 billion as of August 31, 2026 because the quarter was funded with $19.9 billion from new shares rather than notes. Equity rose to $67.196 billion and the equity ratio to 22.2 percent. Interest expense grew 55 percent in the quarter to $1.428 billion; the bond market valued long-term borrowings at roughly 85 cents on the dollar, after roughly 89 cents three months earlier.
- Off-balance-sheet commitments negative
- As of August 31, 2026, $288 billion of data center lease commitments appeared neither as an asset nor as a liability — $28 billion more than three months earlier; they commence between the second quarter of fiscal 2027 and fiscal 2029 and run fifteen to nineteen years. Add $34.150 billion of unconditional purchase and certain other obligations. Total assets are $303.259 billion.
- Valuation neutral
- At the October 2, 2026 close of $142.30 and 3,031,501,149 shares, market capitalization was roughly $431 billion: about 22 times trailing four-quarter diluted earnings of $6.38 per share, about 6.0 times revenue over those four quarters and about 6.4 times book value. The consensus price target across 43 analyst ratings was $237.97 (data as of October 2, 2026).
In the first quarter of fiscal 2027 Oracle showed that the order book is turning into revenue: $19.345 billion, up 30 percent, cloud infrastructure more than doubled, $664 billion of remaining performance obligations. What changed most is who pays for the build-out. In fiscal 2026 the bond market fronted the money; in the first quarter of fiscal 2027 it was customers with $11.4 billion of prepayments and shareholders with $19.9 billion from 141 million new shares. The bill remains large: $28.5 billion of capital spending in three months, $90 billion to $95 billion planned for the fiscal year, $125.3 billion of debt and $288 billion of lease commitments off the balance sheet. Oracle still poses the decisive question in its own risk factors: what happens if large customers cannot perform while the leases and their financing keep running. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
The business works — 30 percent revenue growth and a 34.8 percent operating margin in the quarter ended August 31, 2026 —, but the build-out is being paid for with customer prepayments and new shares rather than free cash flow, and $288 billion of rent sits off the balance sheet. That is not a proven breach of substance, but not proven balance sheet quality either — hence still yellow; the share price plays no part in that color. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- Oracle reached our research list through our in-house stock scanner: rank 20 of 62 in the “Turnaround Candidates” list (U.S. selection) with a turnaround check of 6 of 8 points, as of July 25, 2026. Rank and score are a snapshot of that single day — the lists are recalculated daily. Among other things the list requires a price at least 50 percent below the all-time high; on October 2, 2026 Oracle was 56.7 percent below its peak at $142.30, and on September 8, 2026 it was just inside that line at $162.52, a gap of 50.5 percent.
- Update of October 3, 2026: this edition incorporates the 10-Q for the first quarter of fiscal 2027 (period ended August 31, 2026, filed September 11, 2026), the 8-K earnings release dated September 10, 2026, the earnings call of September 10, 2026 (transcript by The Motley Fool dated September 11, 2026 — a third-party transcript we label as such; figures that also appear in the SEC filings were checked against them, while the capex plan and the free cash flow remarks appear only in the transcript), the 8-K dated September 14, 2026, the DEF 14A proxy statement dated September 25, 2026 and insider filings through October 1, 2026. Annual figures still come from the 10-K for fiscal 2026 (filed June 22, 2026). Price and valuation data as of October 2, 2026 — meant to be evergreen, with no daily price used as a buy argument.
- Identity and currency: the ticker ORCL belongs to Oracle Corporation of Austin, Texas (CIK 0001341439). The former name “Ozark Holding Inc.” (October 19, 2005 to February 1, 2006) was the vehicle for the reincorporation in Delaware, not a change of ownership. The symbol ORCL-PRD denotes depositary shares on the 6.50% Series D preferred stock. After the quarterly report of September 11, 2026, the filings through the most recent one reviewed on October 1, 2026 were the 8-K on the cancelled trading plan (September 14, 2026), the proxy statement for the November 18, 2026 annual meeting, and insider and resale notices — no acquisition, no take-private, no merger.
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of October 3, 2026. Stock Watch will tell you what's changed at ORCL since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Oracle Corporation (ORCL), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
The fiscal year ends on May 31. Fiscal 2026 ran from June 1, 2025 through May 31, 2026. The latest quarterly report (10-Q) covers the first quarter of fiscal 2027, June through August 2026; it was filed with the U.S. securities regulator, the SEC, on September 11, 2026, and the earnings release (8-K) one day earlier. Anyone comparing Oracle with calendar-year reporters is always shifting the window by about six months.
Revenue of $19.345 billion (up 30 percent), $7.388 billion of it from cloud infrastructure (up 121 percent). Operating income of $6.728 billion, net income of $4.760 billion, $1.56 per diluted share after $1.01 a year earlier. Capital expenditures were $28.499 billion and free cash flow was minus $5.396 billion. For all of fiscal 2027 Oracle expects revenue of at least $90 billion.
Remaining performance obligations are the total of all contracted services that have not yet been recognized as revenue. They stood at $664 billion as of August 31, 2026, after $638 billion as of May 31, 2026 and $455 billion a year earlier. Oracle expects to recognize about 13 percent of that as revenue over the next twelve months. The rest is spread across years — and assumes the customers stay able to pay.
Customers pay so far ahead of delivery that the accounting treats it as, economically, a loan to Oracle. In fiscal 2026 that brought in $4.6 billion, and in the first quarter of fiscal 2027 alone $11.4 billion; in fiscal 2024 and 2025 there were no such payments. The money sits in operating cash flow — Oracle still owes the service.
As of August 31, 2026 the balance sheet carried $125.3 billion of notes and other borrowings, after $129.5 billion as of May 31, 2026; per the annual report, maturities run out to calendar 2066. Interest expense rose 55 percent in the quarter to $1.428 billion, after $4.599 billion for all of fiscal 2026. The bond market valued the long-term borrowings at roughly 85 cents on the dollar as of August 31, 2026.
Oracle has leased data centers whose lease terms have not yet commenced, so they appear neither as an asset nor as a liability on the balance sheet. The quarterly report puts them at $288 billion as of August 31, 2026, up from $260 billion three months earlier, commencing between the second quarter of fiscal 2027 and fiscal 2029 with terms of fifteen to nineteen years. For comparison: total assets stand at $303.259 billion.
Under the equity program set up on February 2, 2026, Oracle issued 141 million new shares for $19.9 billion net in the June-to-August 2026 quarter; the $20 billion facility is used up. Shares outstanding rose to 3,031,501,149 (as of September 21, 2026), roughly 5 percent more than on June 12, 2026. On top of that come 50,000 Series D preferred shares that convert automatically into 25.0 million to 31.2 million common shares on January 15, 2029.
The dividend continues: $2.00 per common share in fiscal 2026 and another $0.50, declared in September 2026 and payable on October 23, 2026. Oracle bought back no stock at all in the quarter ended August 31, 2026, after $93 million for all of fiscal 2026. Roughly $6.3 billion of authorization remains available.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.