Novavax Stock: $570 Million More for a Hope
What is the market actually paying for here? Sanofi royalties, the yardstick for Novavax's licensing model, came to $0.7 million in the second quarter of 2026 — and yet the stock rose roughly 40 percent between July 24 and October 2, 2026. The surprises are getting smaller, and so is the cash. Update of October 3, 2026: what the market is paying for are two Sanofi milestones of $125 million and $75 million whose timing Novavax does not set.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 30, 2026
- Closing price
- 10.10 $ -3.70%
- Market Capitalisation
- 1.7 $B
- Growth Score
- 4/10
- AAQS
- 4/10
Price change since October 2, 2026: -3.4%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 6.20 $ to 12.80 $ · Last price: 10.10 $ (As of: October 30, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
There is a reflex that costs investors money: the beat trap. The moment a headline says a company "topped expectations", the brain switches from checking to celebrating. Yet an earnings surprise is first a statement about the estimators and only second a statement about the business. Novavax, Inc. (Nasdaq: NVAX) triggered that reflex five quarters in a row, which is why it sat at rank 49 in our Big Earnings Surprise scanner when we first published (U.S. selection, 81 hits, data as of July 25, 2026). Before we let it infect us, let us make a deal: we read the primary documents together — the 2025 annual report (10-K), the quarterly reports (10-Q) for the periods ended March 31 and June 30, 2026, and every current report (8-K) filed with the U.S. securities regulator, the SEC, through October 3, 2026. They contain the first annual profit in company history. They also contain where it came from: two contracts that were cancelled. Remember the sentence right at the start: a surprise is not an achievement, it is a difference. By now it is the sixth surprise in a row — and the first one no one-off payment helped. It promptly turned out the smallest.

Update October 2026: what the second quarter shows
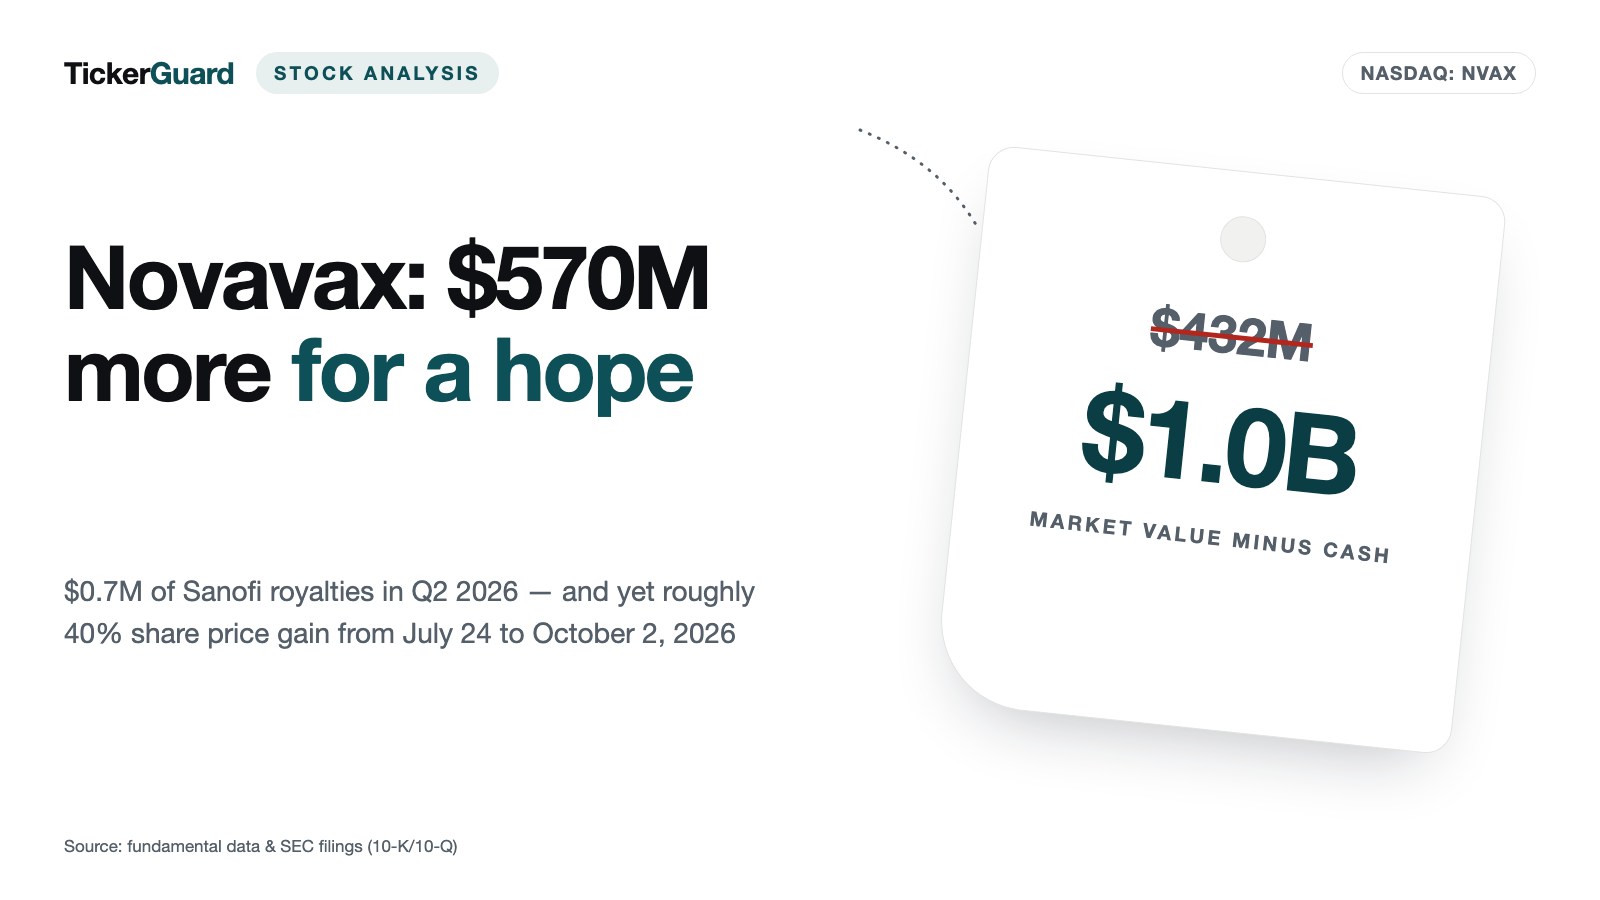
The sixth surprise was the smallest. Since our first edition of July 25, 2026, Novavax filed its quarterly report (10-Q) for the period ended June 30, 2026 on August 6, 2026, together with the earnings release as an exhibit to a current report (8-K, Items 2.02 and 9.01) and a registration of new shares for its employee plans (Form S-8). No further current report (8-K) followed through October 3, 2026. The loss per share came to $0.32 in the second quarter against $0.36 expected — a beat of roughly 11 percent (data as of October 3, 2026). It is the sixth in a row, but the first one that stays below the 20 percent threshold of our Big Earnings Surprise scanner. Under the scanner’s rule, Novavax therefore drops off exactly the list that brought the stock to our desk. And the punchline of this update belongs right here: $0.7 million of royalties in the quarter — and roughly $570 million more that the market has been paying since July for the hope of licensing income (calculation in the valuation chapter).
As of this update: October 3, 2026. The chapters on the uncomfortable truths further down carry the first-quarter basis; where a figure has changed since, the new value sits next to it. Valuation, opportunities and risks, the conclusion and the fact sheet have been brought up to date.
The numbers: revenue fell to $56.7 million, 76 percent below the prior-year quarter ($239.2 million). Most of the decline is the absence of one-off payments: a year earlier the books contained $175.0 million for the U.S. approval of the pre-filled syringe and $27.2 million of Takeda revenue. Product sales, by contrast, rose from $10.7 million to $18.9 million, driven by supplies of adjuvant, vaccine and material to partners; there were no longer any Nuvaxovid sales of its own in the quarter. The bottom line was a net loss of $53.4 million after net income of $106.5 million in the prior-year quarter. For the first half of 2026, revenue came to $196.2 million and the loss to $62.9 million.
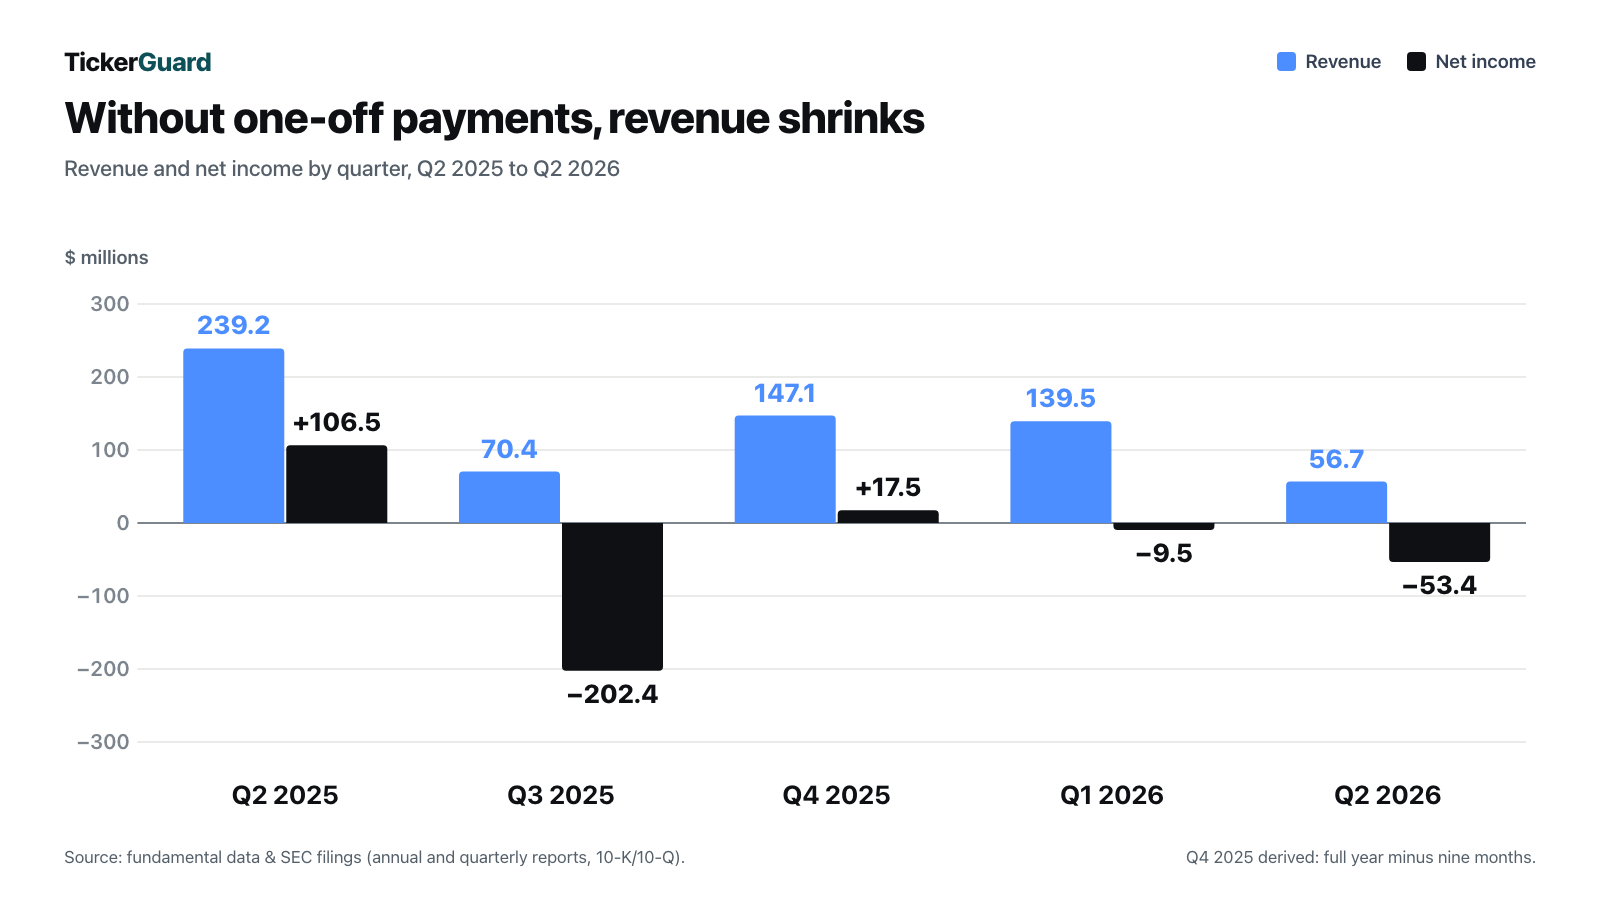
The number we said the licensing model must be measured against was even smaller in the second quarter than in the first: Sanofi royalties came to $0.7 million (first quarter: $3.5 million). Of the $35.8 million Sanofi contributed in the quarter in total, $22.6 million were cost reimbursements and $12.5 million the pro-rata release of earlier upfront and milestone payments — money that arrived long ago. In fairness, the cross-check belongs here too: in the prior-year quarter there were no Sanofi royalties at all, and COVID vaccines are sold in the fall, not in early summer. CFO Jim Kelly said on the August 6, 2026 earnings call that the majority of the remaining 2026 revenue will fall into the fourth quarter. Whether royalties can carry the model will only show in the report on that final quarter. Novavax nudged its own 2026 revenue framework up to $235 million to $275 million — explicitly excluding Sanofi royalties, supply sales and milestones, for which the company gives no guidance.
The cash: the going-concern section of the new report states the figures itself:
"As of June 30, 2026, the Company had total cash and cash equivalents, restricted cash, and marketable securities of $723.9 million, comprised of $191.5 million in cash and cash equivalents, $4.6 million in restricted cash, and $527.9 million in marketable securities, and working capital of $440.5 million. During the six months ended June 30, 2026, the Company recognized a net loss of $62.9 million and had net cash flows used in operating activities of $105.2 million."
— Novavax, Inc., Form 10-Q for the period ended June 30, 2026, Note 2 "Liquidity and Going Concern"
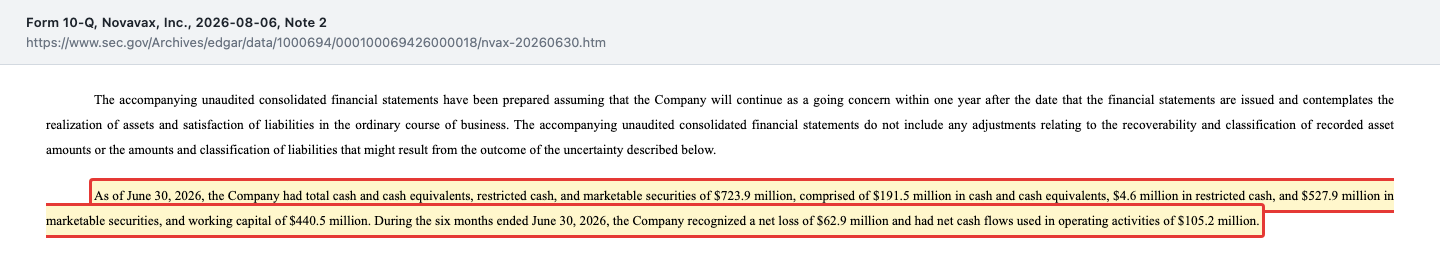
That puts the second quarter alone at an arithmetic $72.8 million of operating cash outflow (first half $105.2 million minus first quarter $32.4 million). Liquidity fell from $794.9 million to $723.9 million in three months, and shareholders’ equity slid from minus $144.8 million to minus $190.7 million. The report again concludes that capital is sufficient for the twelve months after issuance, and the MidCap covenants were met at June 30, 2026. On the call, CFO Kelly laid out the longer line:
"Today, we are announcing our expectation to earn a $75 million manufacturing tech transfer milestone payment from Sanofi mid-next year that would extend our current cash runway from 2028 into 2029."
— Jim Kelly, CFO of Novavax, second-quarter 2026 earnings call on August 6, 2026 (transcript: MarketBeat)
A second milestone comes on top: if Sanofi starts the pivotal phase 3 trial of its combined flu-COVID vaccine in the U.S. or the EU, $125 million becomes due. According to the August 6, 2026 press release, Sanofi is "in advanced discussions with regulators" about timing; Novavax gives no date. Kelly also reaffirmed the goals of reaching non-GAAP profitability — that is, excluding certain items — as early as 2028, of running the company with less than half the head count of the first quarter of 2026 by then, and of consolidating buildings and laboratories to a degree that could trigger non-cash write-offs of up to $35 million in 2027. Remember: both milestones depend on decisions Sanofi makes, not Novavax.
What happened since: on August 28, 2026 Novavax announced in a press release — not a current report — that partners Sanofi and Takeda had received approvals for the vaccine updated to the XFG variant in the U.S., the EU and Japan for the 2026-2027 season. That sets the stage for the fall season the royalties depend on. The stock rose roughly 40 percent between July 24, 2026 (closing price $7.46) and October 2, 2026 ($10.46), without Novavax filing any further current report after August 6. The biggest one-day gain came on August 19, 2026 (plus 10.8 percent), a day on which biotech stocks rallied broadly after cancer vaccine data from Moderna and Merck (Seeking Alpha, August 19, 2026: "Biotechs hit a post-pandemic high after mRNA trial win for Moderna, Merck"). Bottom line: the central tension of this analysis did not resolve in the second quarter, it sharpened. Without one-off payments, $56.7 million of revenue and a $53.4 million loss remain — and the share price today mostly pays for dates set by others.
Company history for investors
-
1987
Novavax is founded
Novavax is founded in 1987 and grows into a maker of protein-based vaccines headquartered in Gaithersburg, Maryland.
-
2024
License deal with Sanofi
Starting May 2024 Novavax hands commercialization of its COVID-19 vaccine to Sanofi and receives a $500 million upfront payment plus milestones.
-
2026
License deal with Pfizer
On January 15, 2026 Novavax signs a license and option agreement with Pfizer for the Matrix-M adjuvant, worth up to $500 million in milestones.
-
2026
First secured loan
In February 2026 Novavax agrees a secured loan of up to $330 million with MidCap Financial, pledging substantially all of its assets.
What Novavax actually does — from vaccine seller to licensor
Novavax was founded in 1987, sits in Gaithersburg, Maryland, and employed roughly 749 people as of December 31, 2025. It became famous for its protein-based COVID-19 vaccine Nuvaxovid — the latecomer among coronavirus shots, built without mRNA. The real family silver, however, is something else: Matrix-M, an adjuvant derived from the bark of the Chilean soapbark tree. In everyday terms an adjuvant is the seasoning that makes a bland dish worth eating: it makes the immune system respond forcefully to an antigen that would otherwise be weak. Matrix-M sits inside the R21 malaria vaccine commercialized by the Serum Institute of India, among others.
Since May 2024 the business model has turned on its axis. Under the collaboration and license agreement with Sanofi, Novavax handed over commercialization of its own COVID-19 vaccine: Sanofi has led sales since the 2025-2026 season, while Novavax supplies and collects. In return came a $500 million upfront payment and, through the end of 2025, a further $275 million in milestones — $50 million for a clinical database lock, $175 million for U.S. approval of a pre-filled syringe presentation, and two payments of $25 million for transferring the European and U.S. marketing authorizations to Sanofi. On top of that come royalties which the quarterly report puts in the "high teens to low twenties percent" range on Sanofi’s sales of the licensed products.
In January 2026 a second licensee arrived. On January 15, 2026 Novavax signed a license and option agreement with Pfizer covering Matrix-M in up to two infectious disease fields: $30 million immediately, up to $500 million in milestones, and tiered royalties in the high mid-single digit percentage range. That completes the picture: Novavax today sells rights, not doses.
And that brings us to the central tension of this analysis, which runs through every chapter: the licensing model is real and potentially very lucrative — but the profits of 2025 and 2026 so far come from one-off payments and from contracts that were terminated. The ongoing business still burns cash. The second quarter of 2026 confirmed it: it was the first quarter without a meaningful one-off payment, and it ended with a $53.4 million loss.
How the stock landed on our desk
Our Big Earnings Surprise scanner looks for companies whose reported earnings per share came in at least 20 percent above the consensus estimate in each of the last four completed quarters. As of July 25, 2026 Novavax sat at rank 49 of 81 U.S. hits, with a relative strength reading of 52 — meaning the stock had performed roughly in line with the median of its comparison universe. To repeat the screen yourself: open the scanner, set the country filter to U.S., read the list by rank. One caveat: these lists are recalculated daily, so a rank is a snapshot, not a property of the company.
The streak itself was striking: plus 312.7 percent in the first quarter of 2025 ($2.93 reported against $0.71 expected), plus 933.3 percent in the second ($0.62 against $0.06), plus 58.4 percent in the third (-$0.47 against -$1.13), plus 116.7 percent in the fourth ($0.11 against -$0.66) and plus 83.8 percent in the first quarter of 2026 (-$0.06 against -$0.37). The second quarter of 2026 added just plus 11.1 percent (-$0.32 against -$0.36); all figures as of October 3, 2026. Six quarters, six beats — but the last gap is too small for the scanner’s threshold.
Back in July the relative strength reading of 52 already told you the market was not celebrating. The reason is the same as the reason for the streak: the surprises arise exactly where analysts cannot model. Nobody can seriously estimate in which quarter a government terminates a supply contract and pays for the privilege, or when a partner triggers a milestone. Those payments made the quarters. A streak born of unforecastability ends the moment the one-off payments stop — with nothing at all changing in the underlying business. The second quarter of 2026 is the proof: no milestone, no termination, and the surprise shrank to 4 cents per share. Remember: the harder a number is to estimate, the bigger the surprise it produces, and the less it tells you.
The numbers over the years — what genuinely impresses
Start with what deserves respect. In two years Novavax rebuilt a company that in 2023 still lost $545.1 million and burned $714.0 million in operations. In 2024 the loss was $187.5 million and the operating cash outflow $87.3 million. In 2025 the books showed net income of $440.3 million for the first time, on revenue of $1,123.5 million — $2.72 per share basic, $2.58 diluted (all figures from the 2025 annual report, 10-K).
Behind that stands a hard restructuring. Selling, general and administrative expense fell from $468.9 million in 2023 through $337.2 million in 2024 to $157.5 million in 2025 — cut by two thirds in two years. Research and development spending went from $737.5 million to $342.3 million over the same period. The company announced a workforce reduction of roughly 25 percent in 2023 and added another 12 percent in January 2024; in 2025 it recorded $7.8 million of severance and $102.7 million of write-downs, including $97.8 million on assets held for sale. The cuts continue: selling, general and administrative expense came to $26.7 million in the second quarter of 2026, after $43.6 million in the prior-year quarter.
The balance sheet improved too. Current liabilities fell from $1,635.1 million at the end of 2023 through $1,154.4 million at the end of 2024 to $459.9 million at the end of 2025, and stood at $330.6 million on June 30, 2026. The equity shortfall shrank from $716.9 million at the end of 2023 to $127.8 million at the end of 2025 — but has widened again since, to $190.7 million at June 30, 2026. Anyone looking at this company in 2023 saw a question of survival; anyone looking today sees a business with $723.9 million in cash, restricted cash and marketable securities (June 30, 2026) and working capital of $440.5 million. That is genuine progress and it deserves to be said out loud.

Uncomfortable truth no. 1: the profit came from cancelled contracts
The annual report itself says where the $1.12 billion of revenue came from — you only have to read the second sentence:
"Revenue for the year ended December 31, 2025 was $1.1 billion as compared to $682.2 million for the year ended December 31, 2024, an increase of $441.3 million. Revenue for the year ended December 31, 2025 was primarily comprised of revenue from the termination of our APAs with Canada ("Canada APA") and New Zealand ("New Zealand APA") of $575.7 million and $27.3 million, respectively"
— Novavax, Inc., Form 10-K for 2025, Part II, Item 7

Let us take that apart. Product sales came to $685.0 million in 2025. Inside that number sit the $603.0 million from the terminated advance purchase agreements with Canada and New Zealand. What remains is roughly $82 million of vaccine, adjuvant and material actually sold. The other $438.4 million of annual revenue is licensing: $386.3 million from Sanofi (of which $225.0 million pure milestones, $91.6 million cost reimbursements, $63.9 million released deferred upfront and milestone amounts, and $5.75 million of genuine royalties), $41.7 million from Takeda and $10.4 million from other partners.
That is the core of this analysis: of $1,123.5 million in revenue, roughly $82 million came from selling goods. Everything else was payment for something being ended, transferred or licensed. A contract can only be cancelled once.

The first quarter of 2026 showed what is left once the termination payments stop: $139.5 million of revenue against $666.7 million in the prior-year quarter — down 79 percent. Product sales shrank from $621.7 million to $42.2 million, of which only $9.6 million from Nuvaxovid sales, because Sanofi now runs distribution. The bottom line was a loss of $9.5 million — and that only because Pfizer contributed a $30.0 million upfront payment. In the second quarter of 2026 even that prop was gone: $56.7 million of revenue, a $53.4 million loss, Sanofi royalties of $0.7 million (details in the update chapter above). Genuine royalties are the yardstick the licensing model has to be measured against — and their first real test is the fall 2026 season.
Uncomfortable truth no. 2: first annual profit, cash still flowing out
2025 was the first profitable year — and at the same time a year in which $244.6 million flowed out of the operating business. That is not a contradiction, it is accounting: a large part of reported revenue was money that had arrived earlier and was merely released into the income statement in 2025. The cash flow statement spells it out: deferred revenue fell by $622.9 million during the year.
An everyday picture: imagine a customer wired you $600 two years ago for ten cases of wine. This year he says he no longer wants the wine and you may keep the money. Your profit and loss account now shows $600 of revenue. Your bank account does not move, because the money has been sitting there all along. That is exactly the difference between $440.3 million of profit and $244.6 million of outflow.
The pattern continues: another $32.4 million left operations in the first quarter of 2026 and an arithmetic $72.8 million in the second — $105.2 million for the first half. For comparison, in the first half of 2025, the one with $625.2 million of reported profit, the outflow was $313.0 million. Remember: profit is an opinion, cash is a fact.
Uncomfortable truth no. 3: shareholders’ equity is negative
At March 31, 2026 total assets of $1,043.2 million stood against total liabilities of $1,187.9 million. Shareholders’ equity was therefore negative: minus $144.8 million. By June 30, 2026 the gap had widened: total assets $955.6 million, liabilities $1,146.3 million, equity minus $190.7 million. The accumulated deficit stood at roughly $4.63 billion at June 30, 2026 — that is how much money this company has lost, net, since it was founded. For context: negative equity does not automatically mean insolvency risk, because a large part of the liabilities are customer prepayments that get settled with deliveries rather than with cash — $443.3 million at June 30, 2026. But it does mean one thing clearly: there is no cushion. Any misstep hits liquidity immediately.
The interim episode is notable: at June 30, 2025 equity was briefly positive ($37.6 million) before slipping back into the red in the third quarter — driven by write-downs tied to the transfer of the 700 Quince Orchard Road site to AstraZeneca and by the exchange of the convertible notes. In October 2025 Novavax itself guided to non-cash charges of $125 million to $127 million for that quarter.
One point matters for the overall picture: the going-concern question that shadowed Novavax for years has been answered positively in the three most recent reports. The 2025 annual report and the quarterly reports for the periods ended March 31 and June 30, 2026 conclude that the company expects to have sufficient capital for the next twelve months. The section is still headed "Liquidity and Going Concern" — but its conclusion today reads differently than it did in 2023.
Uncomfortable truth no. 4: pledged for the first time — the MidCap credit agreement
Novavax financed itself with equity and unsecured convertible notes for decades. That changed in February 2026: a senior secured term loan facility with MidCap Financial Trust provides up to $330.0 million across four tranches, of which $50.0 million was funded at closing. Interest runs at one-month SOFR plus 5.00 percent with a 2.00 percent floor — 8.7 percent at March 31, 2026 and 8.6 percent at June 30, 2026; including issuance costs Novavax books an effective rate of 11.0 percent. The loan matures on March 1, 2031 and carries a 2.75 percent exit fee.
"The Credit Agreement also includes a financial covenant requiring the Company and its subsidiaries to maintain unrestricted cash of at least $100.0 million at all times."
— Novavax, Inc., Form 10-Q for the period ended March 31, 2026, Note 11

The lien is the real price. The facility is secured by a first-priority claim on substantially all assets; the Dutch subsidiary guarantees it, and the equity of Sweden-based Novavax AB — where the Matrix-M technology lives — is pledged. In plain language: the company’s most valuable asset is now collateral for a loan. At March 31 and June 30, 2026 Novavax reported compliance with all covenants; cash and cash equivalents stood at $191.5 million on June 30, 2026, plus $527.9 million of marketable securities. Novavax had not drawn further tranches through June 30, 2026. But the threshold is written into a contract now.
Financial debt stood at $301.5 million in principal at both March 31 and June 30, 2026: $26.5 million remaining of the 5.00 percent convertible notes due 2027, $225.0 million of the 4.625 percent convertible notes due 2031 issued in August 2025, and the $50.0 million MidCap term loan. Net of unamortized issuance costs, the balance sheet carries $291.0 million (March 31) and $291.5 million (June 30). Exchanging the old notes for the new ones cost a one-time non-cash charge of $28.7 million in 2025.
Uncomfortable truth no. 5: Australia could claw back $92.5 million
The notes to the quarterly report contain a sentence that never appeared in a headline:
"In the event that the Company does not, on or before the relevant contractual deadlines, receive regulatory approval for, and deliver, the seasonally updated COVID-19 Vaccine, up to $92.5 million of deferred revenue may become refundable."
— Novavax, Inc., Form 10-Q for the period ended March 31, 2026, Note 5

The background: Australia did not take delivery of the doses due in 2025 and may seek to cancel the 2025 and 2026 deliveries as well. In the third quarter of 2025 Novavax withdrew its Australian marketing application on the recommendation of the local regulator. At March 31, 2026 the agreement accounted for $48.4 million of current and $85.4 million of non-current deferred revenue. The report stated openly that a further amendment may be required and "may not be achievable on acceptable terms or at all".
The quarterly report for the period ended June 30, 2026 shows the same amounts — $48.4 million and $85.4 million — but a new route and a new tone. Alongside a regular approval, Novavax is now pursuing a special access importation approval from Australia’s medicines regulator, the TGA, and for the case that both routes fail, the report contains a sentence that was not there in March:
"The Company has been pursuing a special access importation approval from the TGA to help ensure our supply is available for Australia. The Company is awaiting a final decision on the outcome of its application for special importation. In light of these developments, if the Company is unable to receive regulatory approval by either means, the Company may seek alternatives to continued performance under the agreement."
— Novavax, Inc., Form 10-Q for the period ended June 30, 2026, Note 5
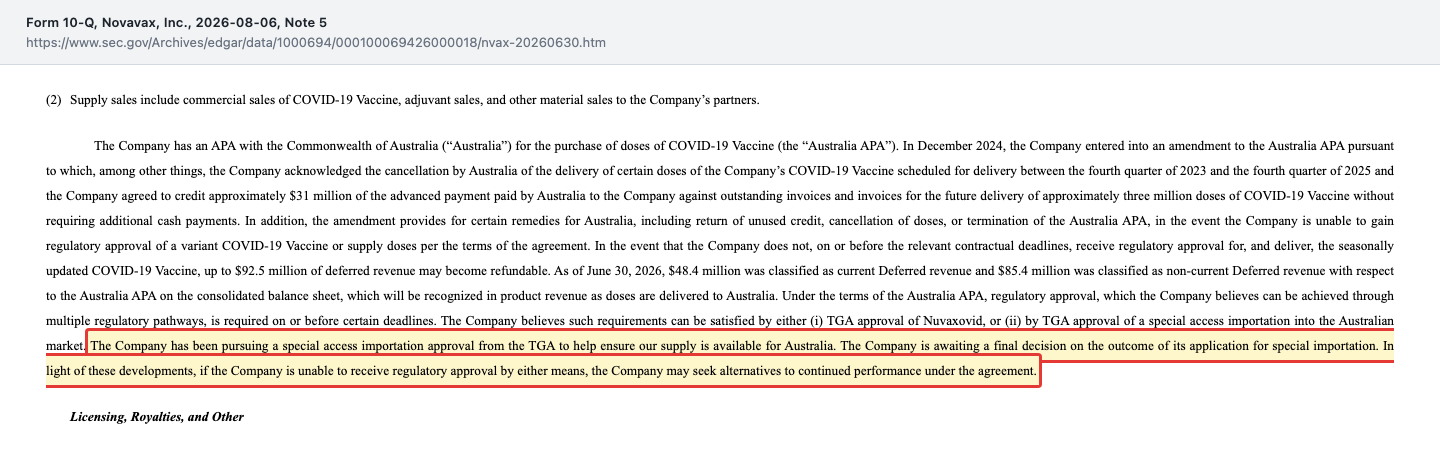
Here is the arithmetic: at March 31, 2026, $92.5 million equaled roughly 41 percent of the $228.4 million cash balance; at June 30, 2026 it is roughly 48 percent of $191.5 million of cash and cash equivalents, or about 13 percent of total liquidity of $723.9 million including securities. The MidCap minimum cash covenant sits at $100.0 million. Those numbers belong side by side. What "alternatives to continued performance" would mean in practice, the report does not say; according to the report, the amended agreement gives Australia remedies in that case up to the return of unused credit, cancellation of doses or termination — instead of revenue, a repayment of up to $92.5 million would then be on the table.
What the stock costs — orders of magnitude, not day prices
At the closing price of October 2, 2026 ($10.46) and 164,945,726 shares outstanding per the cover of the quarterly report (as of July 31, 2026), Novavax carries a market value of roughly $1.73 billion; the cross-check against the figure in the fundamental data (as of October 3, 2026) works out. At our first edition (closing price July 24, 2026: $7.46) it was roughly $1.23 billion. Against trailing twelve-month revenue of $413.8 million that is a price-to-sales ratio of about 4.2 — twice the July level, because the share price rose while revenue shrank without last year’s termination payments. Subtract liquidity of $723.9 million and add financial debt of $301.5 million in principal, and enterprise value comes to roughly $1.30 billion. There is no meaningful price-to-earnings ratio: the 2025 profit was a one-off, and for 2026 the consensus expects a loss of $0.63 per share (data as of October 3, 2026).
The more interesting order of magnitude is another one. Novavax holds $723.9 million in cash, restricted cash and marketable securities (June 30, 2026) — now roughly 42 percent of the market value, down from about 65 percent in July. Against that sit $301.5 million of financial debt and an accumulated deficit of $4.63 billion. In effect the market is paying for the cash plus an option on the licensing stream — and that option has become roughly $570 million more expensive since July on our arithmetic (market value minus liquidity: about $432 million in July, about $1,001 million in October). It is not small, but smaller than it first looks: of the up to $350 million of COVID-19 milestones under the Sanofi agreement, only $75 million remain outstanding, due on completion of the technology transfer. Fully outstanding, by contrast, are the up to $350 million for the combination influenza-COVID product (of which $125 million for the phase 3 start) — $425 million of remaining Sanofi milestones in total according to the quarterly report — plus up to $200 million for each of the first four adjuvant products and $210 million for each one thereafter. The Pfizer agreement adds up to $500 million.
The view of the professionals is sharply split. Of nine recorded analyst opinions as of October 3, 2026, unchanged, five said strong buy, one hold, two sell and one strong sell, at an average target price of roughly $14. Such a spread is not a verdict in itself but it is information: even professionals reading the same documents reach opposite conclusions here. It fits that roughly 30 percent of the free float was sold short (data as of October 3, 2026; about 28 percent in July) — a high reading, and a sign of how contested this stock is. On the other side, asset manager State Street reported a passive 7.1 percent stake on August 7, 2026 (as of June 30, 2026, Schedule 13G). If you want to understand the general shape of a licensing model with a finite clock, our Puma Biotechnology analysis offers a second example; for how an established group handles a core product in decline, see our Biogen analysis.
Opportunities and risks at a glance
Opportunities
- Two global groups as licensees. Sanofi and, since January 2026, Pfizer pay for Matrix-M. The Pfizer deal delivered $30.0 million up front and opens up to $500.0 million in milestones (8-K dated January 20, 2026).
- Two named milestones. $125 million when the phase 3 trial of Sanofi’s combination vaccine starts, $75 million on completion of the technology transfer, which Novavax expects in mid-2027 (press release of August 6, 2026).
- High royalty rates and an approved season. Royalties on Sanofi’s sales of the licensed products run in the "high teens to low twenties percent" range; for the 2026-2027 season, approvals are in place in the U.S., the EU and Japan according to the press release of August 28, 2026.
- Costs keep falling. Selling, general and administrative expense came to $26.7 million in the second quarter of 2026 after $43.6 million a year earlier; Novavax lowered its 2026 guidance for combined R&D and SG&A to $370 million to $410 million.
- Going concern confirmed. The 2025 annual report and both 2026 quarterly reports confirm sufficient capital for twelve months; liquidity stood at $723.9 million at June 30, 2026.
Risks
- The ongoing business burns cash. $56.7 million of revenue and a $53.4 million loss in the second quarter of 2026, $105.2 million of operating cash outflow in the first half.
- Royalties are still tiny. $0.7 million from Sanofi in the second quarter of 2026, $3.5 million in the first — whether the fall season carries the model will only show in the fourth quarter.
- Negative equity. Minus $190.7 million at June 30, 2026 against an accumulated deficit of $4.63 billion — there is no cushion for missteps.
- Australian repayment risk. Up to $92.5 million of deferred revenue may become refundable; Novavax is waiting for a special access importation approval and does not rule out "alternatives to continued performance".
- Secured debt with covenants. First-priority lien on substantially all assets including the equity of Novavax AB, $100.0 million minimum cash, 11.0 percent effective interest rate.
- Dilution. 29.698 million potentially dilutive securities at June 30, 2026, plus 10.71 million newly registered shares for employee plans (S-8 dated August 6, 2026) — together just under a quarter of shares outstanding.
- Dates set by others. Sanofi decides when the combination vaccine trial starts; Novavax gives no date.
A human conclusion
Back to the beat trap from the beginning. Five quarters in a row Novavax beat expectations by a wide margin — and every time for a different one-off reason: a contract termination, a regulatory milestone, a transfer, an upfront payment. In the second quarter of 2026, for the first time, no such reason was there. There was still a surprise, but it shrank to 4 cents per share, on a $53.4 million loss. That is the lesson of the beat trap: the surprise was never proof that the business is running better than expected. It was proof that nobody can seriously estimate when which counterparty writes which cheque.
At the same time it would be unfair to reduce this company to its accounting. Novavax has cut selling, general and administrative expense by two thirds, won two global groups as licensees, prepared the 2026-2027 season with approvals and answered the survival question for now. Anyone buying NVAX today is buying neither a vaccine manufacturer nor a turnaround story, but a bet on someone else’s sales force and someone else’s calendar: on Sanofi selling in the fall, the combination trial starting and the technology transfer succeeding. Since July that bet has become roughly 40 percent more expensive, while liquidity fell from $794.9 million to $723.9 million in the second quarter alone. It may pay off handsomely — the current report on the Pfizer license speaks of "billions of dollars" over the life of the agreement. It may also mean that a company with negative equity spends years waiting for milestones that others have to trigger.
What you make of that is your decision. And that is exactly as it should be.

Sources
- Novavax, Inc. — annual report on Form 10-K for 2025 (filed February 26, 2026, CIK 0001000694)
- Novavax, Inc. — quarterly report on Form 10-Q for the period ended March 31, 2026 (filed May 6, 2026)
- Novavax, Inc. — quarterly report on Form 10-Q for the period ended June 30, 2026 (filed August 6, 2026)
- Current report on Form 8-K dated August 6, 2026, Exhibit 99.1 — second-quarter 2026 earnings release with full-year outlook
- Registration statement on Form S-8 dated August 6, 2026 — additional shares for the employee plans
- Current report on Form 8-K dated January 20, 2026 — license and option agreement with Pfizer
- Current report on Form 8-K dated October 22, 2025 — site transfer to AstraZeneca and material impairments
- Current report on Form 8-K dated August 21, 2025 — exchange of the 2027 convertible notes into the 2031 notes
- Transcript of the second-quarter 2026 earnings call of August 6, 2026 (MarketBeat; third-party transcript, not a primary source)
- Novavax press release of August 28, 2026 — approvals of the updated vaccine for the 2026-2027 season
- Seeking Alpha, August 19, 2026 — sector report on the biotech rally (not a primary source)
- SEC EDGAR filing index for Novavax — filings from the latest quarterly report onward reviewed through October 3, 2026
- Fundamental data (key figures, earnings surprise history, analyst opinions, price series), data as of October 3, 2026
Disclaimer: this article is journalistic commentary on publicly available corporate filings. It is not investment advice, not a recommendation to buy or sell, and not a solicitation to buy or sell securities. Share prices can move sharply; a total loss of invested capital is possible. Every figure carries the as-of date stated in the text and may have changed since. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this deep dive.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 1,146.3 | 1,599.0 | 556.4 | 682.2 | 1,123.5 |
| Operating Income (EBIT) | -1,686.6 | -644.7 | -566.5 | -248.9 | 563.3 |
| Net Income | -1,743.8 | -657.9 | -545.1 | -187.5 | 440.3 |
| Net Margin | -152.1% | -41.1% | -98.0% | -27.5% | 39.2% |
| Earnings Per Share | -23.44 $ | -8.42 $ | -5.41 $ | -1.23 $ | 2.54 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
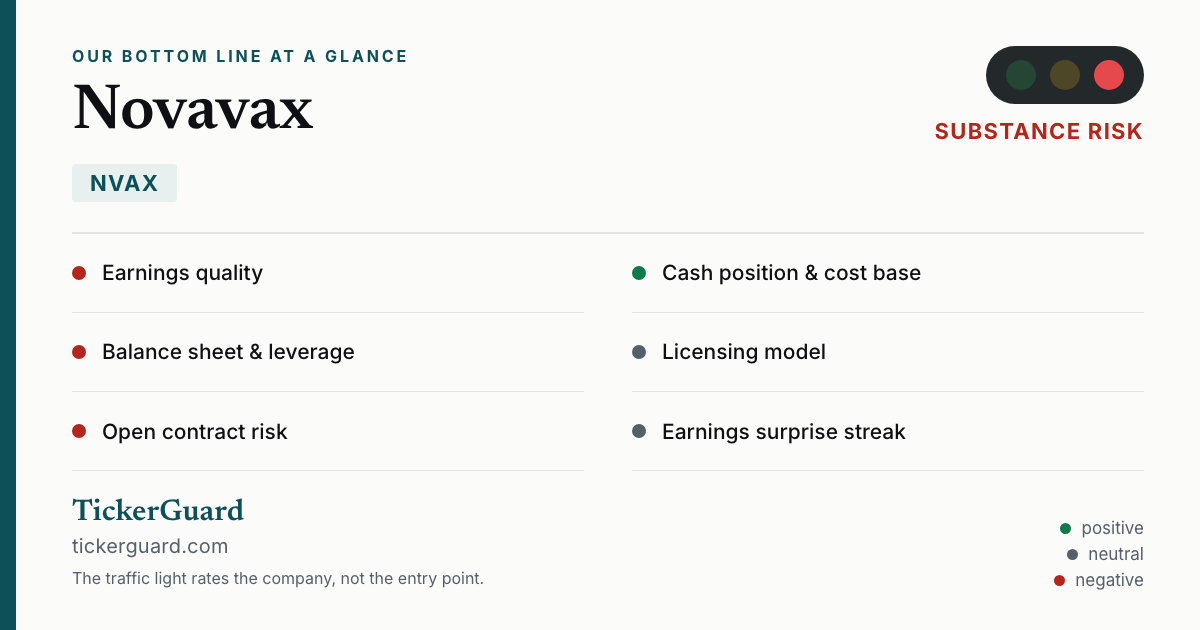
Our Bottom Line at a Glance
- Earnings quality negative
- Of $1,123.5 million in 2025 revenue, $603.0 million came from terminating the advance purchase agreements with Canada and New Zealand; actual product sales were roughly $82 million. Without one-off payments, revenue fell to $56.7 million in the second quarter of 2026 and the loss came to $53.4 million (10-K 2025; 10-Q for the period ended June 30, 2026).
- Cash position & cost base positive
- $723.9 million of cash, restricted cash and marketable securities at June 30, 2026, roughly 42 percent of a market value of about $1.73 billion (closing price October 2, 2026); selling, general and administrative expense fell to $157.5 million in 2025 from $468.9 million in 2023, and to $26.7 million in Q2 2026 (10-K 2025; 10-Q for the period ended June 30, 2026).
- Balance sheet & leverage negative
- Negative equity of $190.7 million at June 30, 2026 against a $4.63 billion accumulated deficit; secured debt for the first time, with a first-priority lien on substantially all assets, an 11.0 percent effective interest rate and a $100.0 million minimum cash covenant — met at June 30, 2026 (10-Q for the period ended June 30, 2026, Note 11).
- Licensing model neutral
- Sanofi and, since January 2026, Pfizer pay for Matrix-M; named milestones are $125 million (combination vaccine trial start) and $75 million (technology transfer, expected mid-2027). Actual royalties in the second quarter of 2026, however, came to just $0.7 million (10-Q for the period ended June 30, 2026, Note 5; 8-K dated August 6, 2026).
- Open contract risk negative
- Up to $92.5 million of deferred revenue from the Australian advance purchase agreement may become refundable; Novavax is awaiting a special access importation approval and may otherwise seek alternatives to performing the contract, with $133.8 million on the balance sheet as current and non-current deferred revenue at June 30, 2026 (10-Q, Note 5).
- Earnings surprise streak neutral
- Six consecutive quarters above consensus, but only plus 11.1 percent in the second quarter of 2026 after plus 83.8 percent in the first — without one-off payments the beat drops below the 20 percent threshold of the Big Earnings Surprise scanner (data as of October 3, 2026).
Novavax has turned itself from a vaccine seller into a licensor and posted the first annual profit in company history in 2025 — $440.3 million, more than half of the underlying revenue from two terminated supply agreements. The second quarter of 2026 shows the business without such one-offs: $56.7 million of revenue, a $53.4 million loss, $0.7 million of Sanofi royalties. On the credit side stand falling costs, $723.9 million of liquidity, two global groups as licensees and two named milestones of $125 million and $75 million; on the debit side negative equity, pledged assets and a market value that has risen roughly 40 percent since July while the cash pile shrank. Not investment advice.
What Our Rating Means
Substance risk
We found at least one documented issue that threatens the company itself — regardless of how the stock is currently valued.
The red light here is about substance, not about the share price. Two documented findings hit the company itself: shareholders' equity was negative at minus $190.7 million on June 30, 2026, $45.9 million worse than in March, against an accumulated deficit of $4.63 billion — and operating cash flow was negative in 2023, 2024 and 2025 and again in the first half of 2026, with $105.2 million flowing out. On top of that, substantially all assets have been pledged since February 2026, including the equity of Sweden-based Novavax AB, where the Matrix-M technology sits. There is a great deal on the other side: all three of the most recent reports certify sufficient capital for the next twelve months, liquidity stood at $723.9 million on June 30, 2026, management cites a cash runway into 2028, and selling, general and administrative expense keeps falling. This is therefore not a verdict of insolvency — but a company with no equity cushion, whose ongoing business still burns cash and whose Sanofi royalties most recently amounted to $0.7 million in a quarter, has not yet proven its quality: hence red. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- Currency of sources (update of October 3, 2026): the basis is the annual report (10-K) for 2025 of February 26, 2026 and the quarterly report (10-Q) for the period ended June 30, 2026 of August 6, 2026. Every document filed from that day onward was reviewed — the current report (8-K) of August 6, 2026 with the earnings release, the registration statement (S-8) of the same day and the State Street ownership report (13G) of August 7, 2026 (7.1 percent at June 30, 2026). No further filing followed through October 3, 2026; the August 6, 2026 earnings call was available as a third-party transcript.
- NVAX reached our research list at rank 49 in our in-house Big Earnings Surprise scanner (U.S. selection, 81 hits, relative strength 52, data as of July 25, 2026); with a beat of 11.1 percent in the second quarter of 2026 the stock no longer meets the scanner rule (at least 20 percent in each of the last four quarters).
- Identity verified against EDGAR: Novavax, Inc., CIK 0001000694, Nasdaq, no former names, no successor CIK, U.S. domestic filer reporting on Forms 10-K and 10-Q, fiscal year ending December 31.
- Easy to confuse: Novavax is not an mRNA manufacturer. Nuvaxovid is protein-based, and the Matrix-M platform is an adjuvant that also sits inside third-party vaccines such as the R21 malaria vaccine.
- Price and market value figures use the closing price of October 2, 2026 ($10.46) and were cross-checked against the 164,945,726 shares outstanding reported as of July 31, 2026; the first edition used the closing price of July 24, 2026 ($7.46).
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of October 3, 2026. Stock Watch will tell you what's changed at NVAX since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Novavax Inc (NVAX), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Novavax develops protein-based vaccines and the Matrix-M adjuvant, but largely leaves commercialization to partners. Sanofi has led distribution of the COVID-19 vaccine Nuvaxovid since the 2025-2026 season. Novavax supplies, keeps researching, and earns through milestones, cost reimbursements and royalties. In the second quarter of 2026 there were no Nuvaxovid sales of its own anymore; product sales of $18.9 million came from supplies to partners.
Because the profits of the first five quarters came from payments analysts cannot time: contract terminations, regulatory milestones, transfers of marketing authorizations, a $30 million upfront from Pfizer. In the second quarter of 2026 no such payment arrived — and the beat shrank to roughly 11 percent (-$0.32 against -$0.36 per share, data as of October 3, 2026).
Of $1,123.5 million in 2025 revenue, roughly $82 million came from vaccine, adjuvant and material actually sold. The remaining $603.0 million of product sales stemmed from terminating the advance purchase agreements with Canada and New Zealand, and the other $438.4 million was licensing. In the second quarter of 2026 product sales came to $18.9 million, from supplies of adjuvant, vaccine and material to partners.
No. The 2025 annual report and the quarterly reports for the periods ended March 31 and June 30, 2026 conclude that the company expects to have sufficient capital for the twelve months following issuance. At June 30, 2026 it held $723.9 million of cash, restricted cash and marketable securities. On the August 6, 2026 call, management cited a cash runway into 2028, extended into 2029 by the expected $75 million milestone.
Because liabilities exceed assets: $1,146.3 million against $955.6 million at June 30, 2026, leaving minus $190.7 million. The cause is roughly $4.63 billion of accumulated losses since 1987 plus large customer prepayments totaling $443.3 million. Part of those liabilities will be settled with deliveries rather than cash — but there is still no cushion.
From Sanofi, $125 million when the phase 3 trial of the combined flu and COVID vaccine starts and $75 million on completion of the technology transfer, which Novavax expects in mid-2027; plus further milestones and royalties in the "high teens to low twenties percent" range. From Pfizer, up to $500 million in milestones. In each case the partners decide the timing.
No. As of October 3, 2026 no Form 15 deregistration and no Form 25 delisting notice had been filed with the SEC; the stock trades on the Nasdaq Global Select Market under the symbol NVAX. No merger or acquisition agreement appears in any current report either. The most recent event filing was the current report of August 6, 2026 on the quarterly results.
Sanofi royalties. They came to $3.5 million in the first quarter of 2026 and $0.7 million in the second — outside the vaccination season. The first real test is the fourth quarter of 2026, which management says will carry most of the remaining annual revenue. If royalties grow materially, the licensing model carries the company; if they stay small, Novavax keeps living on milestones that others have to trigger.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.