Mogotes Metals: One Drill Hole, a Famous Neighbor and 609 Million Shares
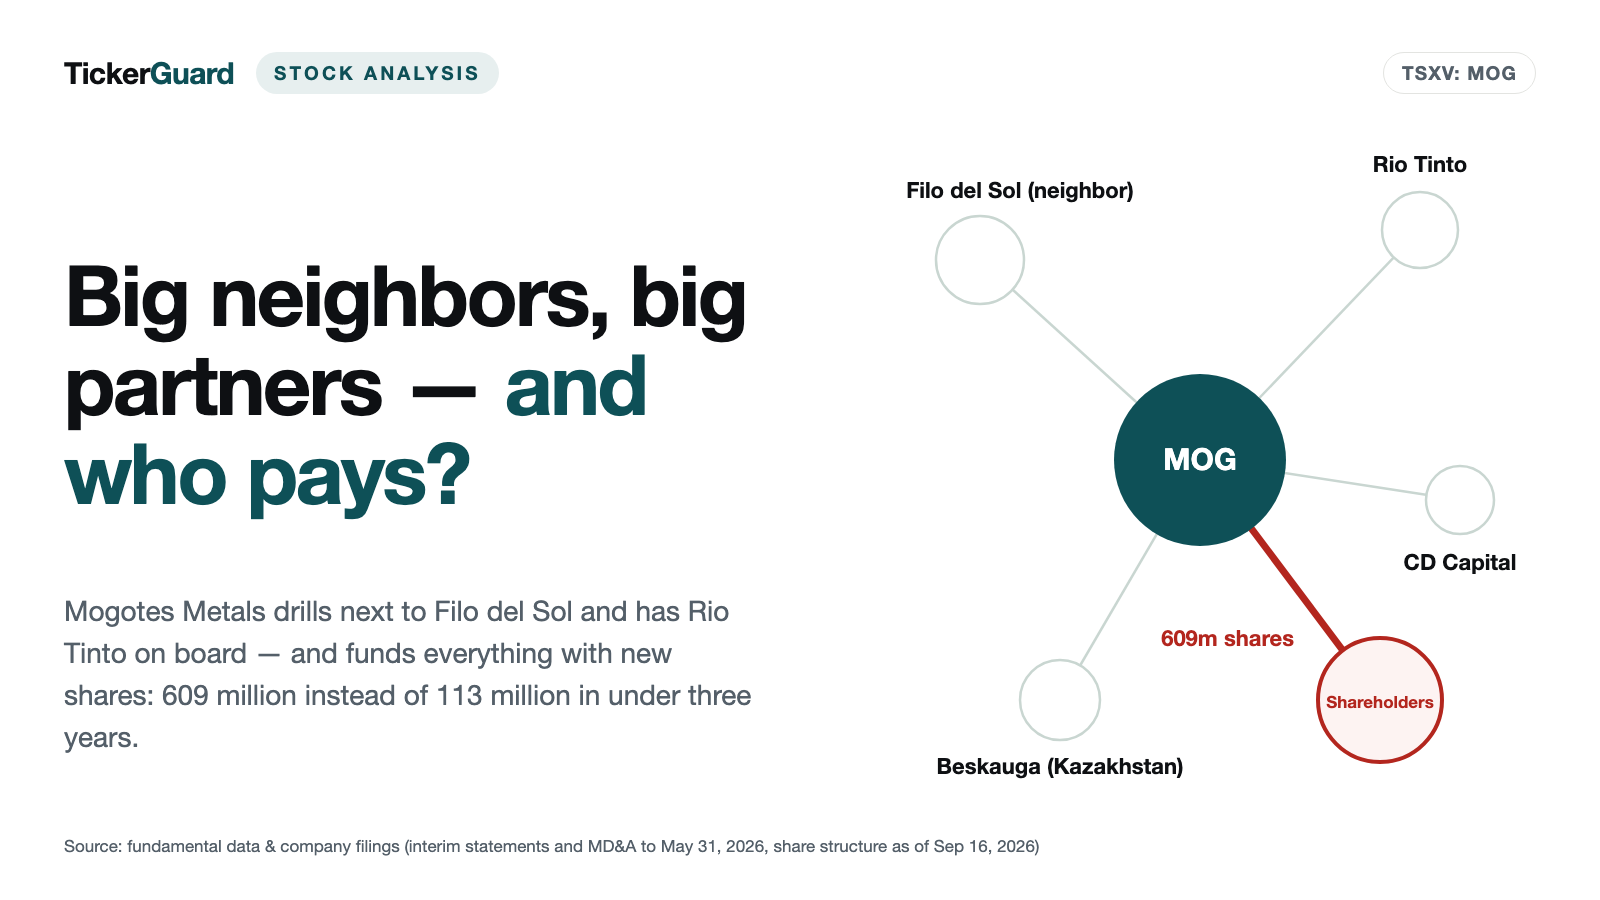
On May 14, 2026, Mogotes Metals (TSXV: MOG, OTCQB: MOGMF) jumped from C$0.225 to C$0.57 in a single session — on the back of one drill hole right next to the giant Filo del Sol deposit. Since then, Rio Tinto has become a shareholder, and Mogotes is now drilling in Kazakhstan as well. Rio Tinto agreed to pay C$0.70 per unit when the stock stood at C$0.39. Yet it is mainly shareholders who still pay for the drilling: 609 million shares instead of 113 million in under three years.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 13, 2026
- Closing price
- 0.475 C$ +3.26%
- Market Capitalisation
- 0.2 C$B
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
Last price: 0.475 C$ (As of: October 13, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
Do you know the feeling that a place must benefit from its famous neighbor? Open a restaurant next to a Michelin-starred chef, and yours suddenly seems a little better too. Psychologists call this the contagion heuristic: we transfer qualities to something simply because it has been in contact with something else. Mining even has a mocking word for it — “closeology,” the science of proximity. Let’s call it the neighborhood trap.
Mogotes Metals is a textbook case. The company drills in the Vicuña district on the border between Argentina and Chile, directly south of Filo del Sol, which BHP and Lundin Mining are developing and which Mogotes itself describes as one of the world’s largest copper-gold-silver discoveries. Its own releases, however, also contain a sentence that names the trap:
“The Qualified Person has not verified the information regarding adjacent properties such as Filo del Sol, and the information regarding mineralization on the Filo del Sol project is not necessarily indicative of the mineralization on the Filo Sur project.”
— Mogotes Metals Inc., news release of September 22, 2026, section Qualified Person
The tension running through this analysis: big neighbors, big partners, one promising drill hole — and a company without revenue that pays for every meter drilled with new shares. Let’s read the filings together. The decision is yours at the end.
What Mogotes Metals Actually Does
Mogotes is a pure explorer: it searches for copper, gold and silver but neither mines nor sells anything. It was incorporated in Ontario on August 12, 2022, and is based in Toronto. The money goes into drilling, geophysics and options on projects. The MD&A lists three projects:
- Filo Sur (Argentina and Chile) — the flagship, 100% owned by Mogotes. It adjoins BHP and Lundin Mining’s Filo del Sol. In the 2025–2026 season, Mogotes drilled 6,208 meters and reported two discoveries: the Albor breccia and the Cruz del Sur porphyry system. A porphyry is a large, generally lower-grade copper-gold deposit around a cooled body of magma; a breccia is broken rock cemented back together by hot fluids, in which metal can concentrate.
- Beskauga (Pavlodar Province, Kazakhstan) — since February 27, 2026, an option to acquire 100% for a total of US$24.7 million. The project has a historical resource estimate from 2022 that Mogotes expressly does not treat as a current resource.
- Copper Cliff (Montana) — since April 15, 2026, an option to joint venture with Kennecott Exploration, a Rio Tinto subsidiary. Mogotes can earn 51% by spending US$16 million on exploration within three years.
The MD&A describes the idea as “counter-cyclical” field seasons: drilling in the Andes happens during the southern summer (roughly November to May), in Kazakhstan and Montana during the northern summer. For the next twelve months, according to the September 22, 2026, release, Mogotes plans up to 20,000 meters at Filo Sur starting in November 2026, up to 50,000 meters at Beskauga with a preliminary economic assessment (PEA) within twelve months, and 8,000 to 9,000 meters at Copper Cliff once permitted.
Company history for investors
-
2022
Incorporation and Filo Sur option
Incorporated in Ontario on 08/12/2022, option on the Filo Sur project next to Filo del Sol in September 2022. For shareholders, the start of an unlisted explorer.
-
2024
Listing on the TSX Venture Exchange
Trading began on 06/12/2024 under MOG, first close C$0.14. By the end of November 2024, 236.8M shares were outstanding, roughly twice as many as a year earlier.
-
2025
Filo Sur at 100 percent
On 02/10/2025 the option was amended into a full acquisition of Filo Sur, plus options in Chile. In November 2025 the first fully funded drill season began.
-
2026
CD Capital, Beskauga, Albor, Rio Tinto
CD Capital came in (January), Beskauga option (02/27), Copper Cliff (04/15), price jump after FS_DDH_016 (05/14), Rio Tinto at C$0.70 (08/27/2026).
How the Stock Landed on Our Desk
The trigger was not a hit from our in-house stock scanner. The stock made our research list via the forum hot list of wallstreet-online, the ranking of the stocks most discussed by German retail investors (as of October 12, 2026). That is a signal of attention, not of quality.
The home exchange is the TSX Venture Exchange in Toronto, the market for young and small companies. Mogotes has traded there under MOG since June 12, 2024, in Canadian dollars. In the US, the stock trades over the counter as MOGMF (OTCQB), and in Frankfurt as OY4. Mogotes is not registered with the SEC. Its mandatory reports are filed under Canadian rules on SEDAR+ and posted on its investor page: interim financial statements with management’s discussion and analysis (MD&A) and audited annual statements. It reports under IFRS in Canadian dollars. The fiscal year ends November 30, so the “second quarter of 2026” in the reports is the quarter from March through May 2026.
The most recent periodic report is the interim statements as of May 31, 2026, with an MD&A dated July 29, 2026. Since then, Mogotes has announced that Stephen Nano stepped down from the board (August 7; according to the release, he remains a technical advisor), CD Capital’s exercise of rights (August 12 and 13), the closing of the Rio Tinto placement (August 27), the end of the Filo Sur season (September 4) and its exploration plans (September 22, 2026). The report for the period ended August 31, 2026, had not been published as of October 13, 2026; last year, the corresponding report came out in October.
The Numbers Over the Years — Credit Where It Is Due
An explorer has no revenue to give credit for. What does deserve credit is this: in just under three years, Mogotes has gone from a company with C$1.1 million of equity (November 30, 2023) to one that plans to drill in three countries at once — and it has won big names along the way. In January 2026, CD Capital came in, a natural-resources fund that, according to a Mogotes news release dated January 5, 2026, took a strategic stake in its neighbor Filo Corp back in 2020; through Carmel Daniele, CD Capital’s founder, the fund has been represented on the board since March 10, 2026. In August 2026, Rio Tinto followed with US$15 million.
The flip side is the net loss. At its core, it is exploration spending, because Mogotes expenses its drilling and project costs immediately instead of capitalizing them on the balance sheet. The loss was C$6.6 million in fiscal 2024, C$14.4 million in fiscal 2025 and C$20.3 million in the six months ended May 31, 2026, alone.
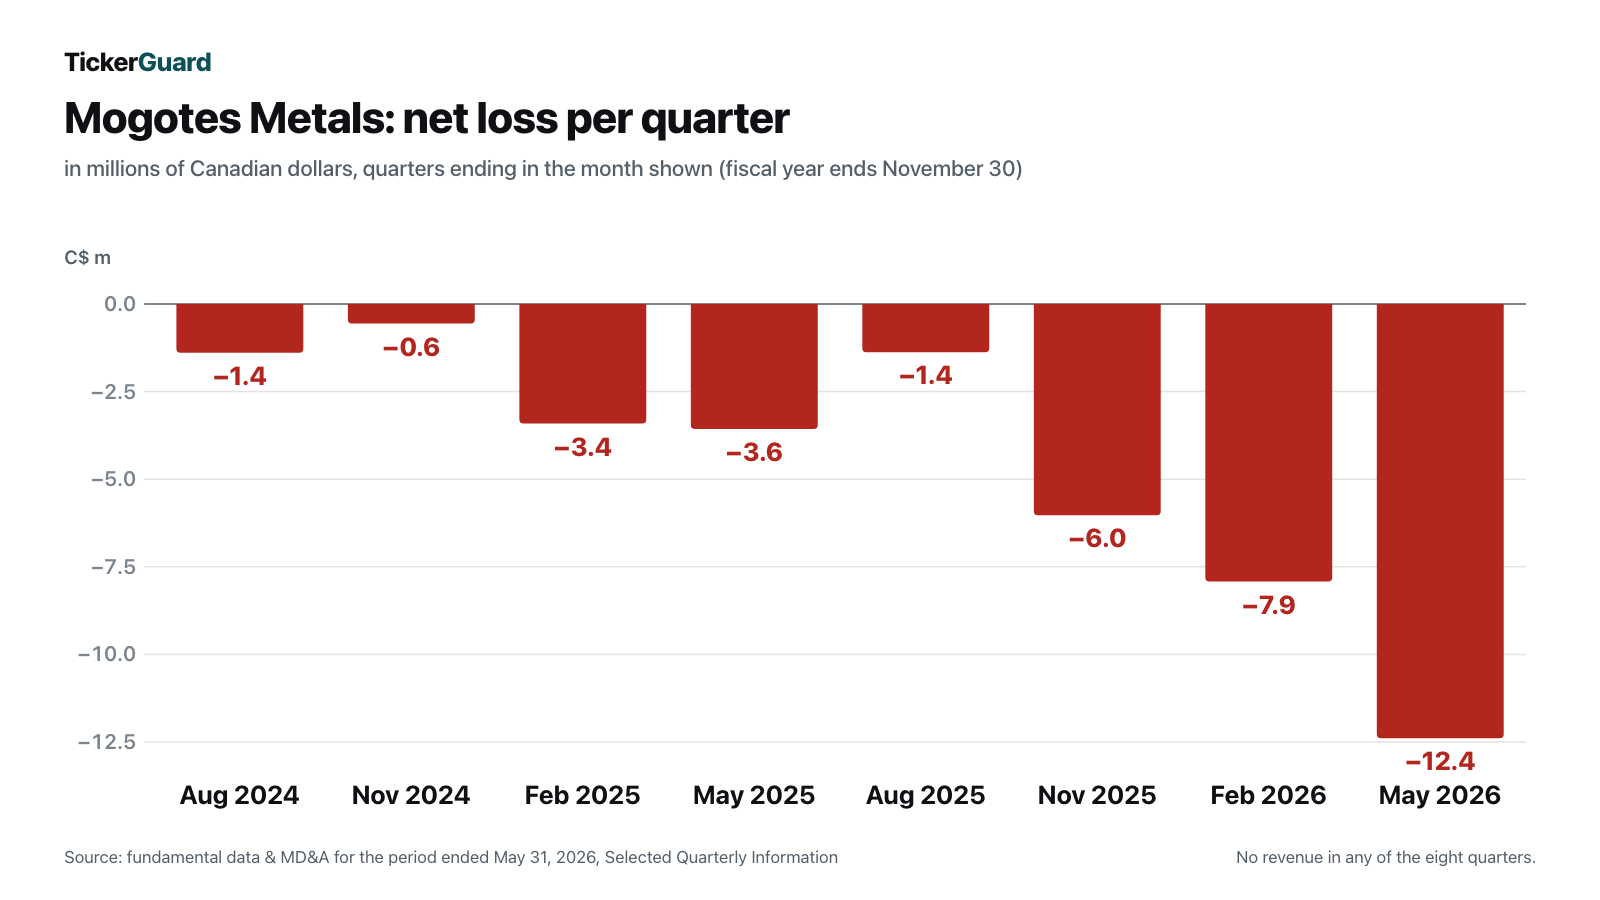
In the quarter ended May 31, 2026, C$12.5 million went into exploration and projects: C$6.3 million to Filo Sur, C$5.5 million to Beskauga (C$3.7 million of it acquisition and claims costs), C$0.3 million to Copper Cliff and C$0.4 million to generating new projects. Operating activities used C$17.5 million in the six months. At May 31, 2026, Mogotes had C$43.8 million of cash and working capital (current assets minus current liabilities) of C$41.3 million. It has no bank debt.
A lot of money came in after the reporting date: C$19.2 million from the rights exercised by CD Capital and other shareholders (August 13) and C$26.9 million from the Rio Tinto placement including pre-emptive rights (August 27). Adding both, gross, to the May 31 cash gives about C$90 million — a rough estimate: spending since June is not deducted, and proceeds from warrants and options exercised since then are not added. Extending the six-month operating cash outflow (C$17.5 million, just under C$3 million a month) through June to September would leave roughly C$78 million, before those exercise proceeds; that is our own rough estimate, which the report for the period ended August 31 will allow you to check.
What the Filings Say — the Uncomfortable Truths
Now let’s set the neighborhood aside and read the fine print. What follows is not in the corporate presentation but in the financial statements and releases.
Uncomfortable Truth No. 1: A going-concern warning despite a full treasury
An explorer without income lives on the capital markets giving it money again and again. Mogotes says exactly that in its interim statements — as an explicit warning:
“As at May 31, 2026, the Company had not yet achieved profitable operations and expects to incur further losses in the development of its business, all of which constitutes a material uncertainty which casts significant doubt about the Company’s ability to continue as a going concern.”
— Mogotes Metals Inc., interim financial statements as of May 31, 2026, note 1 Nature of operations and going concern
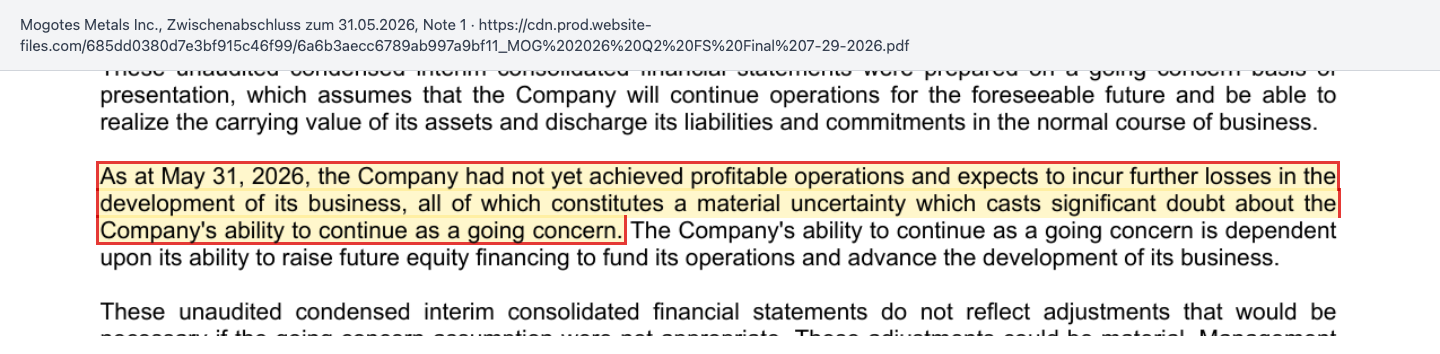
The same warning appears in a separate “Material Uncertainty Related to Going Concern” section of auditor Jones & O’Connell’s report on the financial statements for the year ended November 30, 2025 — when the company had C$18.1 million of cash and C$5.0 million of short-term investments. To be fair: such paragraphs are common for explorers without income, and with roughly C$90 million gross after the August placements, the treasury is well stocked. Still, management’s wording on the reach of its C$41.3 million of working capital at May 31, 2026, is notably cautious — it “may be sufficient” to fund the planned activities for the next twelve months. That was before the drilling plans were expanded to up to 50,000 meters at Beskauga (MD&A: more than 30,000 meters) and up to 20,000 meters at Filo Sur. The bottom line stays the same: owning Mogotes means owning a company that will sooner or later have to raise money again as long as it sells nothing.
Uncomfortable Truth No. 2: A single drill hole carries the story
On May 13, 2026, the stock closed at C$0.225. On May 14, Mogotes reported the first partial results from hole FS_DDH_016 at the Albor target: 86 meters of 0.7% copper, 0.55 grams of gold per tonne and silver. The stock closed at C$0.57 — up 153% in a single day, with 16.1 million shares traded. On paper, the market value rose that day from about C$118 million to about C$298 million.
On July 9, 2026, the results for the full hole followed: 180 meters at 0.98% copper equivalent from a depth of 108 meters, including 58 meters at 1.77%. That is a good intercept. On average, however, it contains 0.51% copper; gold, silver and molybdenum make up the rest of the “equivalent,” converted using assumptions. The stock fell from C$0.51 to C$0.375 that day. The release also contained some dampeners: the second hole at the same spot, FS_DDH_019, hit the breccia only thinly and, according to Mogotes, is not an adequate test. And regarding the copper-equivalent conversion:
“Assumed metallurgical recoveries are based on district analogs and there is not yet any metallurgical test work done on the project; actual recoveries may differ and there is no certainty that the metals will be recovered at the assumed levels.”
— Mogotes Metals Inc., news release of July 9, 2026, notes to Table 1
The season’s other holes are described honestly but make for sobering reading: at Meseta, two holes stopped at 20 and 116 meters; at Camino, one hole failed to reach its planned 1,200 meters because of technical problems; at Cumbre, two holes ended at 10 and 47 meters because winter was coming. The Cruz del Sur porphyry delivered long but low-grade intercepts (308 meters at 0.46% copper equivalent). At Luz del Sol, Mogotes found copper that its own September 4, 2026, release calls “not economic,” though it may point to a deeper target. On the day of that release, the stock fell from C$0.55 to C$0.44. There is no resource at Filo Sur. So far, the share price rests mostly on one hole.
Uncomfortable Truth No. 3: Your stake shrinks faster than the rigs drill
Dilution means: there are more shares, and your stake in the company gets smaller even if you sell nothing. At Mogotes, this is not a side effect but the funding model.
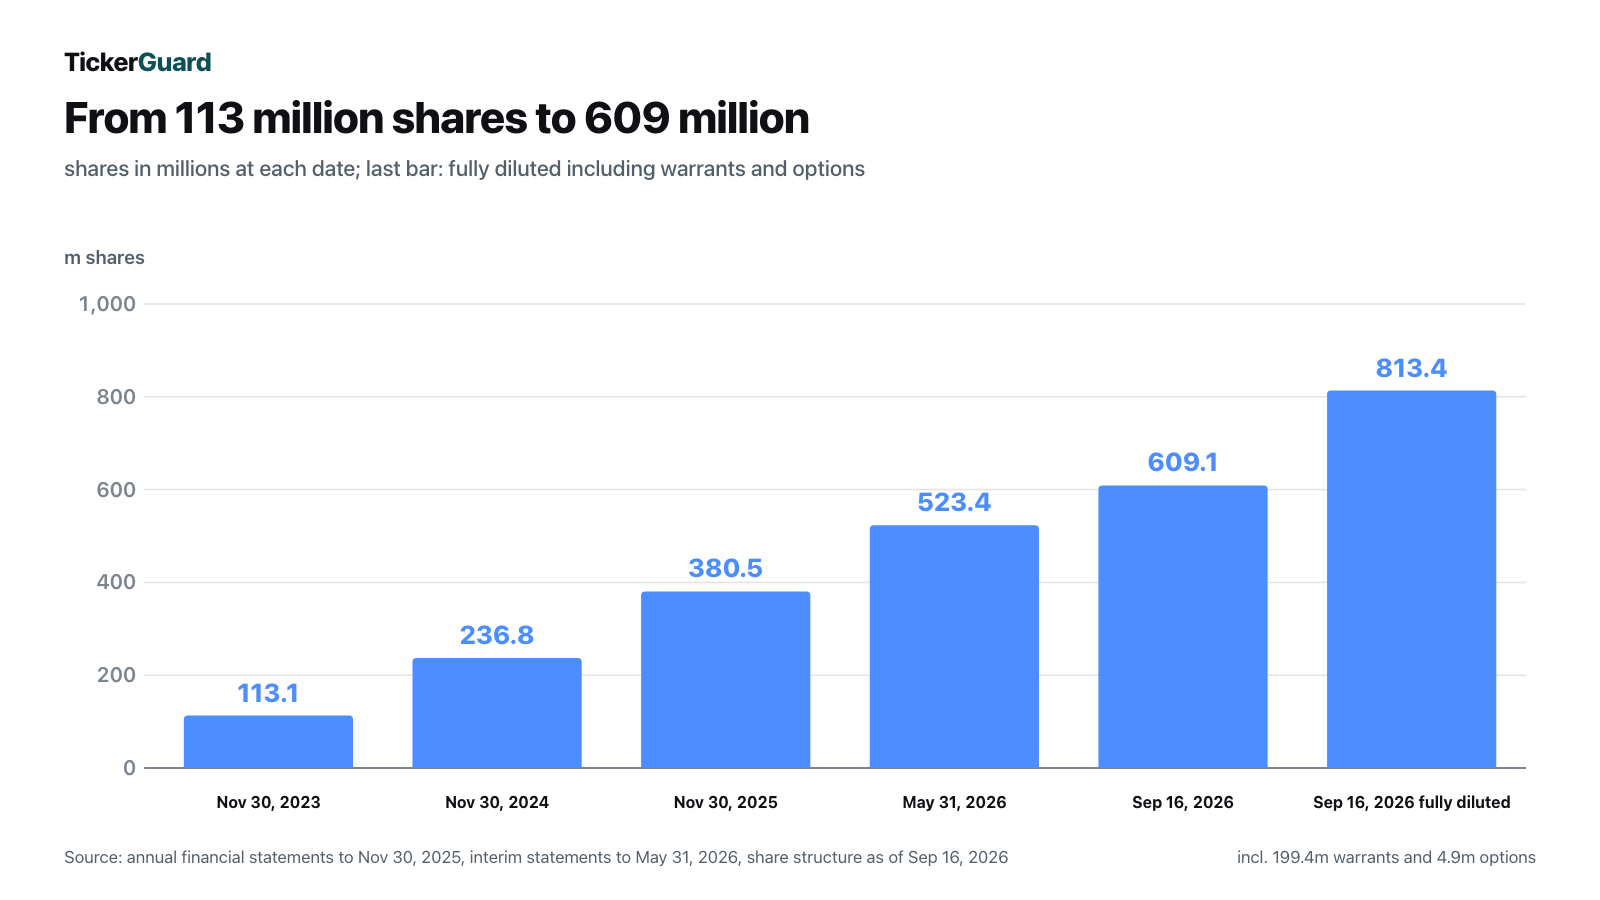
The placement prices tell the story too: in January 2026, Mogotes issued 86.8 million units at C$0.265 and 48.4 million at C$0.32, each with half a warrant. In August came the rights at C$0.49 and Rio Tinto at C$0.70; both were agreed in mid-July — Rio Tinto’s price on July 13 with the stock closing at C$0.39, the rights price on July 14 (previous close C$0.39, close that day C$0.53). The round of August 13, 2026, is worth a closer look:
“The Offering constitutes a related party transaction within the meaning of TSX Venture Exchange Policy 5.9 and Multilateral Instrument 61-101 – Protection of Minority Security Holders in Special Transactions (“MI 61-101”) as insiders of the Company purchased an aggregate of 36,689,414 Common Shares pursuant to the Offering. The Company is relying on the exemptions from the valuation and minority shareholder approval requirements of MI 61-101 contained in sections 5.5(b) and 5.7(1)(a) of MI 61-101, as the Company is not listed on a specified market and the fair market value of the participation in the Offering by the insider does not exceed 25% of the market capitalization of the Company in accordance with MI 61-101. The Company did not file a material change report in respect of the related party transaction at least 21 days before the closing of the Offering, which the Company deems reasonable in the circumstances in order to complete the Offering in an expeditious manner.”
— Mogotes Metals Inc., news release of August 13, 2026, Closing of Exercise of Rights
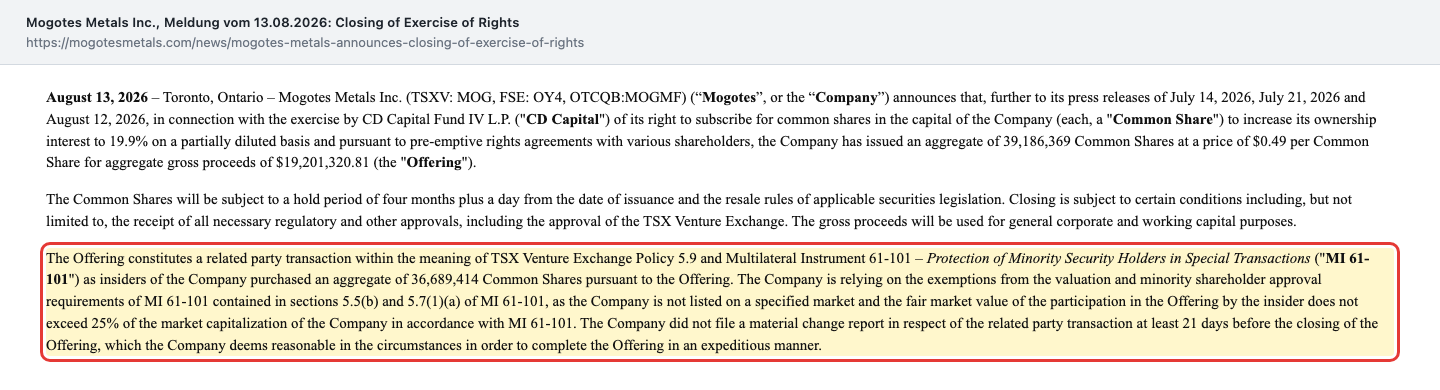
The C$0.49 price followed from the top-up right that CD Capital negotiated when it came in in January 2026; the releases do not disclose exactly how it was calculated. For comparison: when it came in in January 2026, CD Capital paid C$0.265 per unit, and on the closing date (January 30, 2026) the stock closed at C$0.42. The C$0.49 price was fixed on July 14 and at that point was above the previous day’s close (C$0.39); by the issue date of August 13, the stock had risen to C$0.60. Rio Tinto paid more at C$0.70 per unit but also received half a warrant and exclusivity over Filo Sur. In fairness: according to a clarification dated September 22, 2026, insiders also bought into the Rio Tinto round through their pre-emptive rights at C$0.70, a total of 5,503,323 shares. For you as a shareholder, this means issue prices follow contracts with fixed terms, not the price on the issue date — and large existing holders can use such rights to keep their stake while yours shrinks. Then there are the warrants: at September 16, 2026, 199.4 million were outstanding at an average of C$0.47, including 53.1 million at C$0.30 expiring January 31, 2027. Every exercise brings in cash — and new shares.
Uncomfortable Truth No. 4: Three countries, three bills
With Beskauga and Copper Cliff, Mogotes has quickly secured two expensive options on two more continents. Legally, Mogotes does not have to pay any of it: according to the MD&A, all option payments and expenditure commitments are at the company’s sole discretion. But if it does not pay, it loses the option. For Beskauga, US$22.2 million is still outstanding: US$1.0 million each on January 1, 2027, 2028 and 2029, and US$19.2 million on or before February 8, 2029. Mogotes may pay up to US$6.5 million of that in shares, at a floor of C$0.48 per share. Under the agreement, a mining licence application is also to be submitted to the Kazakh authorities by January 1, 2027. The MD&A spells out what happens if the money is not there:
“There is no assurance that the Company will have capital to make required payments, that share settlement will be available on acceptable terms, that the Beskauga Option will remain in good standing, or that Copperbelt AG will perform its obligations. Failure to meet option requirements, counterparty default, or adverse regulatory conditions could result in loss of the Company’s rights and forfeiture of all prior payments and expenditures.”
— Mogotes Metals Inc., MD&A for the period ended May 31, 2026, Risk Factors, Beskauga Option
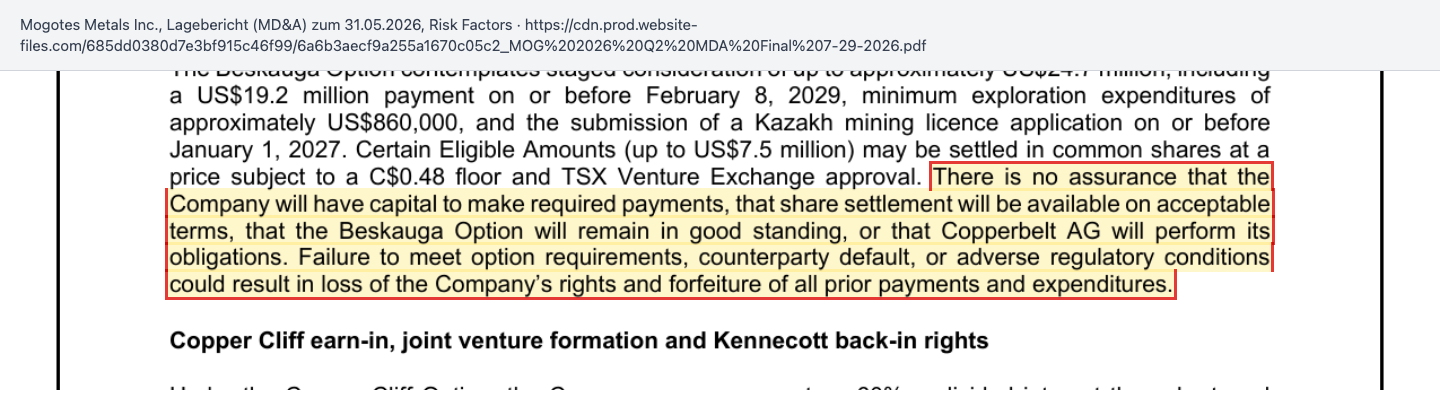
Beskauga also brings risks that Filo Sur does not have: sanctions regimes of several countries covering business in Central Asia, possible problems with banks and payments in the region, and a local currency that the MD&A links to the Russian ruble. The 2022 historical resource — indicated 111.2 million tonnes at 0.30% copper and 0.49 grams of gold per tonne — still has to be re-verified.
At Copper Cliff in Montana, the deal is structured differently. Mogotes funds exploration alone: US$4 million in the first year, US$16 million by the third anniversary for 51%. Then Kennecott can come back to the table:
“Following earn-in, Kennecott may exercise back-in rights (2% for US$32.0 million following 51% earn-in; 20% for US$140.0 million following 60% earn-in), which could dilute the Company to a minority interest and reduce operational control and strategic optionality.”
— Mogotes Metals Inc., MD&A for the period ended May 31, 2026, Risk Factors, Copper Cliff
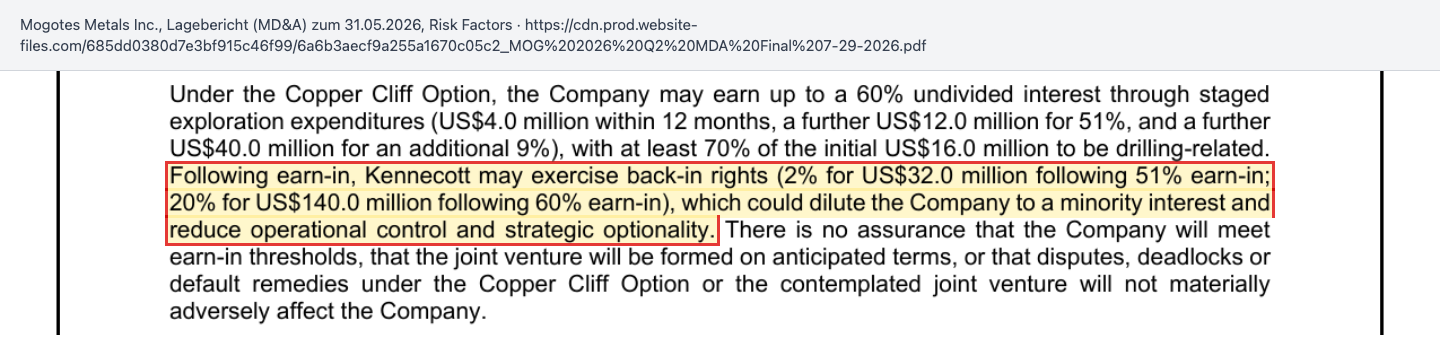
Put in everyday terms: Mogotes renovates a house at its own expense for US$16 million and gets 51% of it. If something valuable turns up inside, the owner can buy back two percent and is in charge again. For Rio Tinto, this structure secures a way back to the majority; for Mogotes, it means a big success in Montana does not automatically become a big success for Mogotes shareholders. Filo Sur is similar: since August 27, 2026, Rio Tinto has had 15 months of exclusivity there (extendable by six months), may match any third-party proposal for the project and can top up its stake to as much as 9.99%. That protects against a bargain takeover by outsiders — but it also narrows the circle of potential buyers.
Valuation: What the Market Pays for the Neighborhood
With 609,109,157 shares (as of September 16, 2026) and a close of C$0.475 on October 9, 2026, Mogotes is valued at about C$289 million. The stock closed at C$0.14 on its first trading day in June 2024, hit its highest close of C$0.67 on June 16, 2026, and on October 9, 2026, stood just under a third below the price Rio Tinto paid in August.
Classic metrics such as the price-to-earnings ratio do not apply to an explorer. As a rough guide: subtract roughly estimated cash of about C$90 million from the market value, and the market values the three projects at about C$200 million (or about C$211 million using the rough C$78 million left after spending since June) — one without a resource (Filo Sur), one with a historical resource that is no longer current plus outstanding payments (Beskauga), and one in which Mogotes still has to earn its stake (Copper Cliff). Equity was C$44.0 million at May 31, 2026; since exploration spending is expensed immediately, it says little about the value of the projects. To put the neighborhood in perspective: according to Mogotes’ release of January 5, 2026, BHP and Lundin Mining acquired neighbor Filo Corp at a valuation of C$4.5 billion — more than twenty times what the market now implicitly assigns to all three Mogotes projects combined.
For a neighbor in the same district that, by its own account, reports the highest drill grades in the Vicuña district but, like Mogotes, has not yet declared a resource for its flagship project and is still valued in the billions, see our analysis of NGEx Minerals. For how long an explorer can drill without declaring a resource, see the analysis of Collective Mining.
Upside and Risks at a Glance
What speaks for the company:
- Location. Filo Sur adjoins Filo del Sol in the Vicuña district, which Mogotes itself counts among the most prospective copper-gold-silver belts in the world.
- First discoveries. 180 meters at 0.98% copper equivalent in FS_DDH_016 (Albor) from 108 meters, plus the Cruz del Sur porphyry system.
- Strong partners. Rio Tinto (about 5%, technical alliance), CD Capital (top-up to 19.9% partially diluted, board seat).
- Well-stocked treasury. C$43.8 million at May 31, 2026, then C$46.1 million gross from two placements, no bank debt.
- Possible cash inflow. 53.1 million warrants at C$0.30 expire on January 31, 2027; if fully exercised, they would bring in about C$15.9 million (with almost 9% more shares).
- Plenty of news flow. Drilling at Filo Sur from November 2026, first Beskauga assays expected in the fourth quarter of 2026.
What speaks against it:
- Going-concern warning. Material uncertainty according to the interim statements and the auditor; Mogotes has no income.
- No resource at Filo Sur. The story rests on a few drill holes, without metallurgical tests; the best hole’s 0.98% copper equivalent contains 0.51% copper.
- Dilution. More than five times as many shares as at the end of 2023, 813.4 million fully diluted.
- Costly options. US$22.2 million for Beskauga and US$16 million of exploration for 51% of Copper Cliff — payable at Mogotes’ discretion, but if it does not pay, it loses the option and the money already invested.
- Country risks. Argentina (inflation, currency controls), Kazakhstan (sanctions, licence application by January 1, 2027), Montana (permits pending).
- Prices agreed in advance. Rights of CD Capital and other existing shareholders at C$0.49, fixed on July 14, 2026 (above the previous day’s close of C$0.39) under the top-up right from January, issued in August with the stock at C$0.60.
A Human Conclusion
Remember the neighborhood trap from the start? Mogotes has secured a coveted piece of ground, and according to its owners, the neighbor is one of the largest discoveries in the world. Rio Tinto has bought in, an experienced resource investor sits on the board, and the first good drill hole is in. For a company that has only been listed since June 2024, that is a remarkable list.
But a deposit does not necessarily stop at the property line — nor does it necessarily continue beyond it. Whether there is a deposit beneath Filo Sur will be decided by the next 20,000 meters of drilling, not by its place on the map. Until then, you as a shareholder help pay for every meter, through the new shares the company keeps issuing. The milestones are clear: the interim statements as of August 31, 2026, the warrants expiring on January 31, 2027, the first drill results from Beskauga and the start of drilling at Filo Sur in November. Look at the map if you like — but read the footnotes afterward.
What you make of it is your decision. And that is how it should be.
Sources and Data Cut-Off
- MD&A for the period ended May 31, 2026 (dated July 29, 2026) and interim financial statements as of May 31, 2026
- MD&A for the period ended February 28, 2026 and interim financial statements as of February 28, 2026
- Consolidated financial statements for the year ended November 30, 2025 (audited by Jones & O’Connell LLP) and the related MD&A
- Releases after the interim report: resignation of Stephen Nano as director, remaining technical advisor (August 7, 2026), closing of the rights exercise at C$0.49 (August 13, 2026), closing of the Rio Tinto placement (August 27, 2026), end of the Filo Sur season (September 4, 2026), exploration plans 2026–2027 (September 22, 2026)
- Further releases: partial results FS_DDH_016 (May 14, 2026), final results FS_DDH_016 (July 9, 2026), Rio Tinto announcement (July 13, 2026), CD Capital investment (January 5, 2026), appointment of Carmel Daniele to the board (March 10, 2026)
- Share structure as of September 16, 2026
- Price and market value data: fundamental data, as of October 9, 2026
Data cut-off: Company figures as of May 31, 2026, or the date stated; share count as of September 16, 2026; releases through September 22, 2026; prices as of October 9, 2026. We last checked the company’s news and reports pages on October 13, 2026; the interim report as of August 31, 2026, had not been published yet. Mogotes is not registered with the SEC; this analysis relies on its Canadian mandatory reports. Reporting and trading currency is the Canadian dollar; the option payments and spending commitments for Beskauga and Copper Cliff are in US dollars. The fiscal year ends November 30. Calculated values (market value, cash after the placements, valuation of the projects, price changes) are our own estimates and labeled as such. The key-figure tiles on this page show the current database values with their own rounding and share count and may differ from the values used here (C$0.475, 609.1 million shares).
Note: This article is journalistic commentary and not investment advice. It contains no recommendation to buy or sell and is not a solicitation to buy or sell securities. Shares of exploration companies without revenue are particularly volatile and depend on drill results, metal prices, financings and country risks; a total loss of the capital invested is possible. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this analysis.
Our Bottom Line at a Glance
- Projects and location positive
- Filo Sur adjoins Filo del Sol in the Vicuña district; first discoveries at Albor (180 meters at 0.98% copper equivalent) and Cruz del Sur. There is no resource yet.
- Partners positive
- Rio Tinto has held about 5% since August 27, 2026, and works with the company technically; CD Capital topped up to 19.9% (partially diluted) in August 2026.
- Cash and going concern negative
- No revenue, a C$20.3 million loss in the six months to May 31, 2026; material going-concern uncertainty per the financial statements. After the August placements, about C$90 million of cash gross.
- Dilution negative
- Share count from 113.1 million (November 30, 2023) to 609.1 million (September 16, 2026), 813.4 million fully diluted; in August 2026, 39.2 million shares were issued at a price of C$0.49 agreed in July.
- Options and countries negative
- US$22.2 million outstanding for the Beskauga option (Kazakhstan), US$16 million of exploration for 51% of Copper Cliff with Kennecott back-in rights — payable at Mogotes’ discretion, otherwise the option lapses; Argentina, Kazakhstan and Montana each carry their own risks.
Mogotes Metals is a copper-gold explorer without revenue, with a well-located flagship next to Filo del Sol, a promising first drill hole and Rio Tinto as a new shareholder. Everything is paid for with new shares: the share count has more than quintupled since late 2023, the financial statements carry a going-concern warning, and costly options in Kazakhstan and Montana come on top of Filo Sur. At the October 9, 2026, close of C$0.475, the company is valued at about C$289 million. Not investment advice.
What Our Rating Means
Substance risk
We found at least one documented issue that threatens the company itself — regardless of how the stock is currently valued.
Red here does not stand for Filo Sur’s location, for Rio Tinto or for the share price. It stands for a documented finding in the company’s own financial statements: the interim statements as of May 31, 2026, and the auditor’s report as of November 30, 2025, flag a material uncertainty about the company’s ability to continue as a going concern, because Mogotes has no income and remains dependent on new equity. After the August 2026 placements, the treasury is well stocked at roughly C$90 million gross, so runway is not an acute problem right now. But plans for up to 79,000 meters of drilling in twelve months, US$22.2 million for Beskauga and US$16 million for Copper Cliff make the next equity raise likely if Mogotes wants to keep all three projects. Green or yellow would only be possible with a reliable resource and financing that does not depend on new shares alone. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- The trigger for this analysis was the wallstreet-online forum hot list (as of October 12, 2026); we track the company under its home listing MOG (TSX Venture Exchange) as MOG.TO. It was not a hit from our in-house stock scanner.
- Mogotes is not registered with the SEC. The basis is the Canadian mandatory reports from the investor page mogotesmetals.com (identical to SEDAR+): interim statements and MD&A as of 02/28 and 05/31/2026, annual statements and MD&A as of 11/30/2025, releases through 09/22/2026. The interim report as of 08/31/2026 had not been published as of 10/13/2026.
- Calculated values are our own estimates: market value from 609,109,157 shares times the 10/09/2026 close; cash after the placements from C$43.8M (05/31/2026) plus C$19.2M and C$26.9M gross, without deducting spending since June and without proceeds from warrants and options exercised since then; the price jump on 05/14/2026 from closes of C$0.225 and C$0.57.
- Copper equivalent converts gold, silver and molybdenum into copper at fixed metal prices and assumed recoveries of 80% each; according to the 07/09/2026 release, no metallurgical test work has been done at Filo Sur yet.
Stock Watch
This analysis is as of October 13, 2026. Stock Watch will tell you what's changed at MOG.TO since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Mogotes Metals Inc. (MOG.TO), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Mogotes Metals is a Canadian mineral explorer based in Toronto. It searches for copper, gold and silver, mainly at its Filo Sur project in the Vicuña district on the border between Argentina and Chile. It also holds an option to acquire the Beskauga project in Kazakhstan and an option to joint venture on Copper Cliff in Montana. Mogotes has no revenue.
It is the same stock. MOG is the symbol on the home exchange, the TSX Venture Exchange in Toronto, traded in Canadian dollars. MOGMF is the US over-the-counter listing on the OTCQB in US dollars, and OY4 is the Frankfurt symbol. TickerGuard tracks the stock as MOG.TO.
Only the neighborhood. Filo Sur adjoins the Filo del Sol deposit being developed by BHP and Lundin Mining. Mogotes itself points out that the mineralization on the neighboring project is not necessarily indicative of Filo Sur. Mogotes has not yet declared a resource of its own at Filo Sur.
On August 27, 2026, Rio Tinto bought 30.4 million units at C$0.70, about US$15 million in total, giving it roughly 5%. It also gets a technical alliance for Filo Sur, 15 months of exclusivity over the project, a right to match third-party proposals and a top-up right to as much as 9.99%.
Mogotes has no income and expects further losses. Whether it can keep operating depends on raising new equity. That is why the interim statements as of May 31, 2026, and the auditor flag a material uncertainty — even though the August 2026 placements brought gross cash to about C$90 million.
The share count rose from 113.1 million on November 30, 2023, to 609.1 million on September 16, 2026. Including 199.4 million warrants and 4.9 million options, there are 813.4 million shares fully diluted.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.