Copper Giant Reports About 50 Percent More Copper — Like-for-Like It Is 23, and the Share Count Is Up Sixteenfold
About 50 percent more copper, Copper Giant (TSXV: CGNT, OTCQX: CGNRF) reported on October 14, 2026, for its Mocoa deposit in Colombia. At the old cut-off, it is 23 percent, and the grade has fallen from 0.51 to 0.45 percent copper equivalent; the new estimate also assumes higher metal prices. The growth is paid for in shares: from 16.2 million at the end of 2023 to 262.5 million in August 2026. We put tonnes, grade and cash side by side.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 25, 2026
- Closing price
- 0.84 C$ 0.00%
- Market Capitalisation
- 0.2 C$B
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
Last price: 0.84 C$ (As of: October 25, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
What happens in your head when you read “1.6 billion tonnes”? For most of us, a picture switches on: a mountain of copper, a treasure, a number too big to imagine. That is the trick of big numbers. They feel like wealth long before anyone has worked out what is inside them. Call it the billion-tonne trap — the size of a number replaces the question of what it contains.
Copper Giant is a textbook case. The Canadian company is drilling a deposit in southern Colombia that it counts among the largest undeveloped copper-molybdenum deposits in the Americas, and on October 14, 2026, it reported that the estimated resource had grown to 1.6 billion tonnes. That is real, independently estimated and published under the Canadian standard. But a tonne of rock is not yet copper. What matters is grade, cost, and how many slices of the pie each shareholder ends up holding.
That is the tension running through this analysis: tonnes versus grade — and growth versus dilution. So let us set the headline aside and read the resource release, the interim financial statements and the MD&A together. Then you decide what the number is worth.
What Copper Giant Actually Owns
Copper Giant Resources Corp. was incorporated under the laws of British Columbia on June 5, 2008, and is based in Vancouver. Until May 1, 2025, it was called Libero Copper & Gold Corporation; since then, it has traded on the TSX Venture Exchange under the symbol CGNT. It describes itself as part of the Fiore Group, a private Canadian group in the natural resource sector. It has no revenue and no reserves. What it has is a project.
That project is Mocoa, in the department of Putumayo, about ten kilometres north of the town of Mocoa, near the border with Ecuador. The deposit was discovered in 1973 during a geochemical survey by the United Nations and the Colombian government; B2Gold later drilled it. In 2018, the company, then Libero, bought the project from B2Gold for 208,000 of its own shares and a 2 percent net smelter return royalty; another 1 percent royalty remains with the previous owner, AngloGold Ashanti. Altogether, 3 percent of future net smelter returns goes to third parties before a shareholder sees anything.
Mocoa is a porphyry deposit. Think of it this way: not a thick vein like in a gold-rush movie, but a huge block of rock with fine copper and molybdenum minerals scattered through it like raisins in a very large loaf of bread. Deposits like this supply much of the world’s copper — but only if they can be mined on an enormous scale and at low cost. That is why every hundredth of a percent of grade counts.
The figures under the Canadian standard NI 43-101, effective September 24, 2026, prepared by the independent consultancy APEX Geoscience:
- Indicated: 290 million tonnes at 0.54 percent copper equivalent, containing 2.13 billion pounds of copper and 240 million pounds of molybdenum.
- Inferred: 1.60 billion tonnes at 0.40 percent copper equivalent, containing 9.36 billion pounds of copper and 0.89 billion pounds of molybdenum; of that, 120 million tonnes lie below the conceptual pit for a possible underground operation.
“Inferred” means there are drill holes, but too few to know the quantity reliably. “Indicated” is one step more certain. Only a reserve is the part for which an economic study has shown that mining pays. “Copper equivalent” converts the molybdenum into copper so that two metals can be expressed in one number. For a sense of what a copper mine that actually produces looks like, see our Freeport-McMoRan analysis.
Around the project, Copper Giant has completed some homework over the past twelve months. In October 2025, its subsidiary Libero Cobre signed a binding agreement with the Inga Condagua Indigenous nation under the prior consultation process (Consulta Previa). On April 28, 2026, Colombia’s National Mining Agency (ANM) approved the integration of titles FJT-131 and FJT-141 into a single concession — with a reset exploration stage. And in September 2026, the consultancy Mira Geoscience delivered a targeting study in which a machine-learning prediction model (a so-called random-forest method) delivered 34 locations that the company consolidated into 17 target areas and ranked itself — 13 of them beyond the known resource and its interpreted extensions.
Company history for investors
-
2018
Mocoa bought from B2Gold
For 208,000 shares and a 2 percent royalty; another 1 percent stays with AngloGold Ashanti. The foundation for everything since — and 3 percent that goes out before shareholders.
-
2024
Ten-for-one share consolidation
In February 2024, every ten old shares became one. That left 16.2 million shares at the end of 2023 on an adjusted basis — and already 57.3 million at the end of 2024.
-
2025
Libero becomes Copper Giant
New name in May, Consulta Previa with the Inga Condagua in October, a 1.12 billion tonne resource in November. Shares outstanding rose to 153.2 million.
-
2026
Denarius comes in, Trafigura locks up concentrate
A C$31.0 million placement at C$0.72 per share on August 21, plus 20 percent of future concentrate for Trafigura. Afterwards: 262.5 million shares.
-
2026
Resource grows, grade falls
On October 14: 290 million tonnes Indicated and 1.6 billion Inferred; at the old cut-off, grade fell from 0.51 to 0.45 percent copper equivalent. The PEA is planned for the fourth quarter.
Why There Is No Annual Report With the U.S. Securities Regulator
Copper Giant files no annual report (10-K) and no quarterly report (10-Q) with the U.S. securities regulator, the SEC. That is normal for a Canadian company with its home listing in Toronto and is not a warning sign. The U.S. symbol CGNRF has traded on the OTCQX, the top tier of the U.S. over-the-counter market, since September 9, 2026; before that, the stock traded on the OTCQB as LBCMF.
Reporting follows Canadian law (National Instrument 51-102) via the SEDAR+ platform: audited annual financial statements with a Management’s Discussion and Analysis (MD&A), plus quarterly interim statements that are not audited. The documents in this analysis come from the OTC Markets mirror of the SEDAR+ filings and from the company’s news archive. That is why every figure carries the line “Source: fundamental data & company financial statements (SEDAR+)”.
How the Stock Landed on Our Desk
Copper Giant made our research list through wallstreet-online’s list of the most discussed and searched-for stocks in October 2026, a German retail investor forum. That is an attention signal, not a quality signal. In Frankfurt, the stock trades as 29H0 (ISIN CA21750C1014); price discovery happens on the TSX Venture Exchange in Canadian dollars.
Why the attention? The price chart explains it: the stock closed 2025 at C$0.49, traded as high as C$1.48 on September 8, 2026 — and stood at C$0.84 on October 23, 2026. The decline did not start with the resource release, but it continued afterwards: the stock closed at C$1.00 on October 14 and at C$0.84 a little over a week later.
Our in-house stock scanner is the wrong tool for a company with no revenue: its quality filters work with earnings, margins and cash flow. The one metric that still says something is the Piotroski score of 2 out of 9 points (data as of the quarter ended June 30, 2026) — a financially healthy company scores 8 or 9. You can look up price data and metrics at any time on our Copper Giant stock page.
On freshness: the latest periodic report is the interim financial statements as of June 30, 2026, approved on August 28, 2026. Through October 25, 2026, four releases followed — the move to the OTCQX (September 9), the targeting study (September 16), drill results (September 22) and the new resource (October 14). The statements for September 30, 2026, had not been filed at press time; TSX Venture companies have 60 days after quarter-end.
The Numbers Over the Years — Given Their Due
First, what is genuinely impressive. For 2026, Copper Giant planned 23,000 metres of drilling, more than 80 percent above the previous year and by its own account the largest exploration program in company history, and now runs four drill rigs. The results hold up: according to the September 22, 2026 release, drill hole MD-073 returned 804 metres at 0.56 percent copper equivalent, including 103 metres at 1.07 percent — more than twice the 0.51 percent average of the resource at the time. According to the company, roughly 10,000 metres already drilled are not yet in the new estimate.
The balance sheet is also solid for an explorer. As of June 30, 2026, it showed C$16.8 million in cash against only C$2.5 million in liabilities; there is no bank debt, and the MD&A says the company has no plans to use debt financing at present. After the balance sheet date, another C$31.0 million came in from the placement with Denarius Metals and others, plus C$3.4 million from exercised warrants and options.
Now the other half. Revenue: zero. The net loss was C$8.36 million in 2024 and C$15.80 million in 2025; in the first half of 2026 alone it reached C$18.15 million. Of that, C$9.19 million was exploration — the purpose of the company — and C$7.65 million was stock options, which cost no cash but do cost ownership. Operating cash outflow was about C$7.0 million in 2024, C$14.0 million in 2025 and C$9.1 million in the first half of 2026, C$5.5 million of it in the second quarter alone.
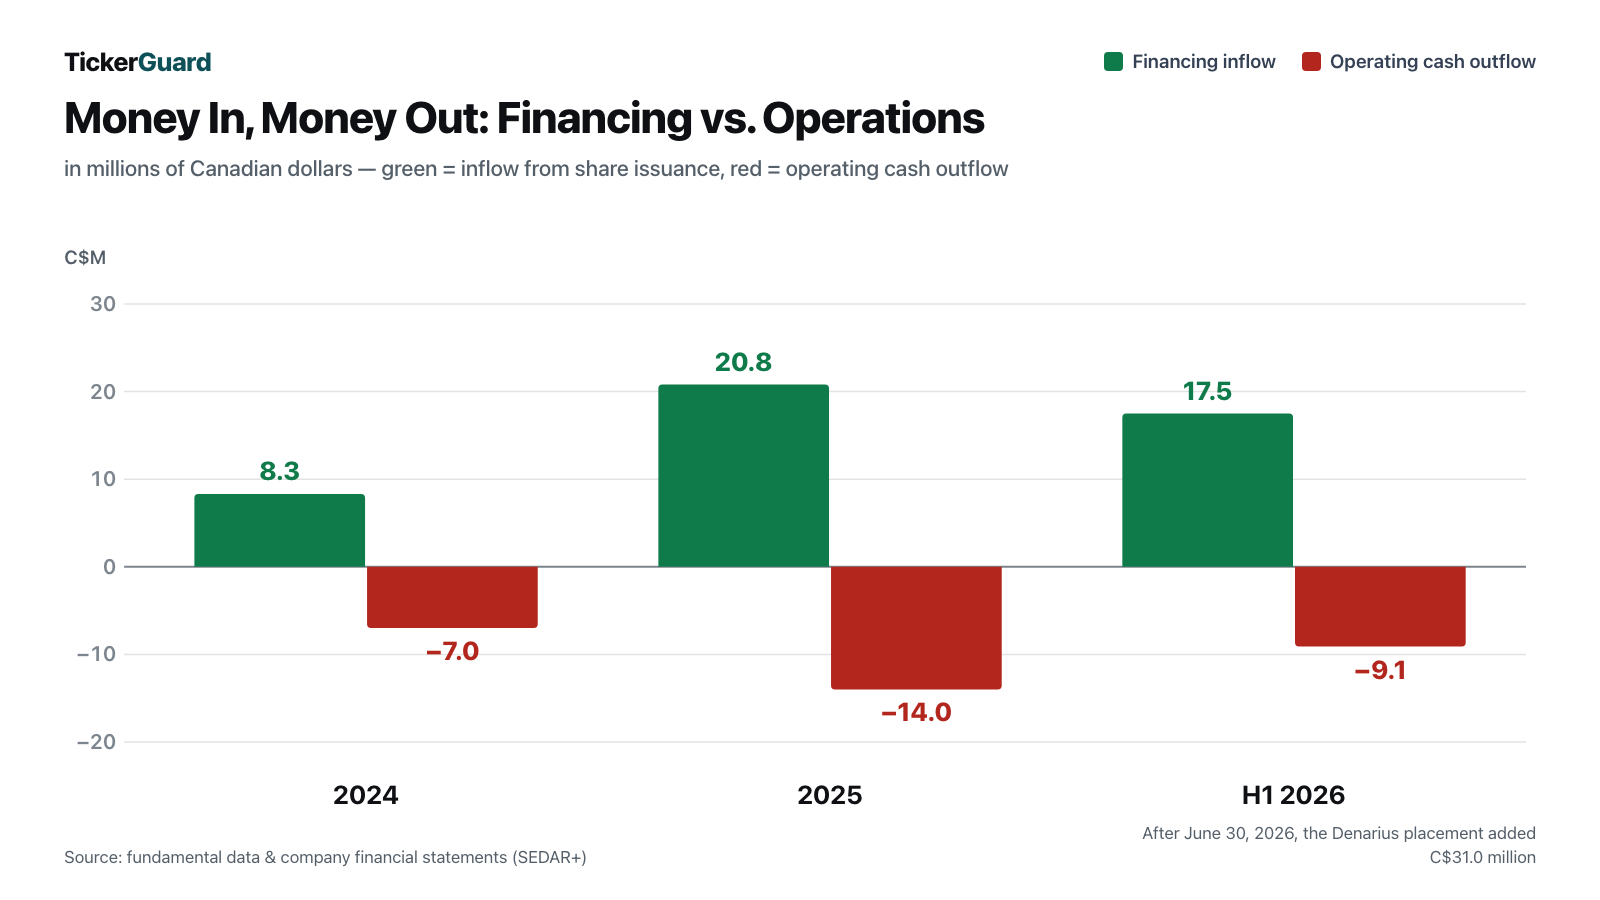
The pattern is typical for an explorer that is ramping up drilling: the outflow grows, and it is covered with new shares. The second chart shows what that means for the share count:
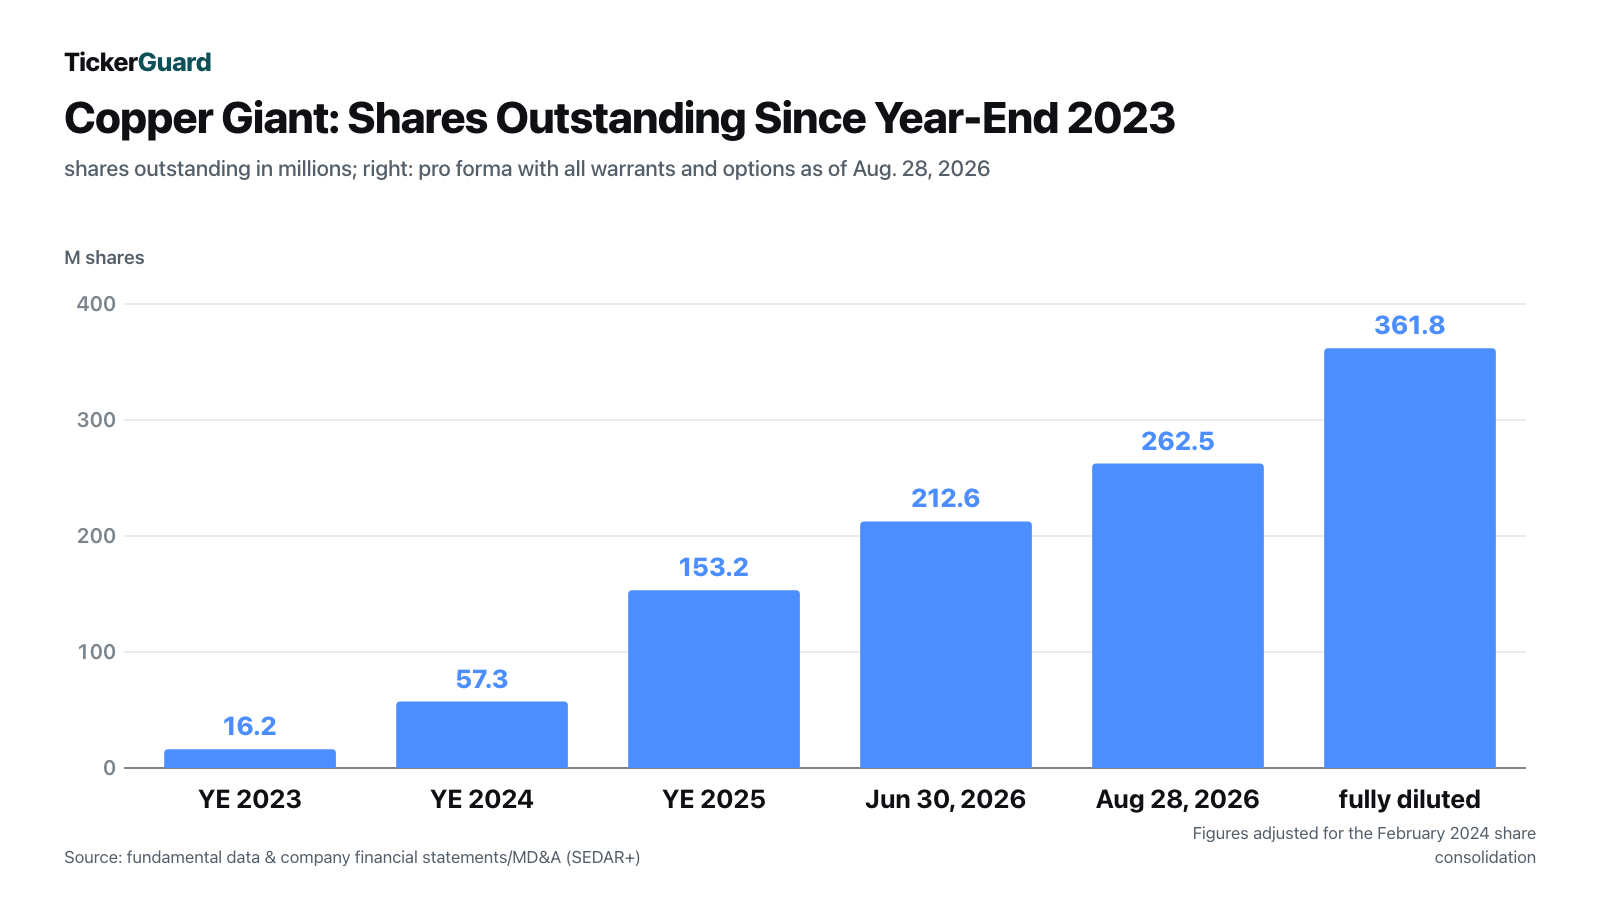
Dilution — your slice of the pie gets smaller as more people sit down at the table — is meant literally here. Anyone who owned 1 percent of the company at the end of 2023 and did not buy more held about 0.06 percent in August 2026. That is not an accusation: an explorer with no revenue can only finance itself this way, and placement prices have risen — from C$0.20 in July 2025 to C$0.40 in January 2026 and C$0.72 in August 2026. But you always have to divide the size of the deposit by the number of shares.
What the Filings Say — the Uncomfortable Truths
Now the passages that appear in no headline. All of them come from the company’s own documents.
Uncomfortable Truth No. 1: More Tonnes, Lower Grade
The October 14, 2026 release opens with an increase of “approximately 50%” in contained copper. That is correct if you compare the new estimate at its new, lower cut-off of 0.15 percent with the old one at 0.25 percent. The cut-off is the line above which rock counts as ore — lower it, and the tonnage grows automatically while the average grade falls. To its credit, the company does the like-for-like comparison itself, further down on page 3 of the release:
“The Inferred grade at that cut-off is 0.45% CuEq* against 0.51% CuEq* in 2025.”
— Copper Giant Resources Corp., news release of October 14, 2026 on the Mocoa mineral resource estimate, page 3
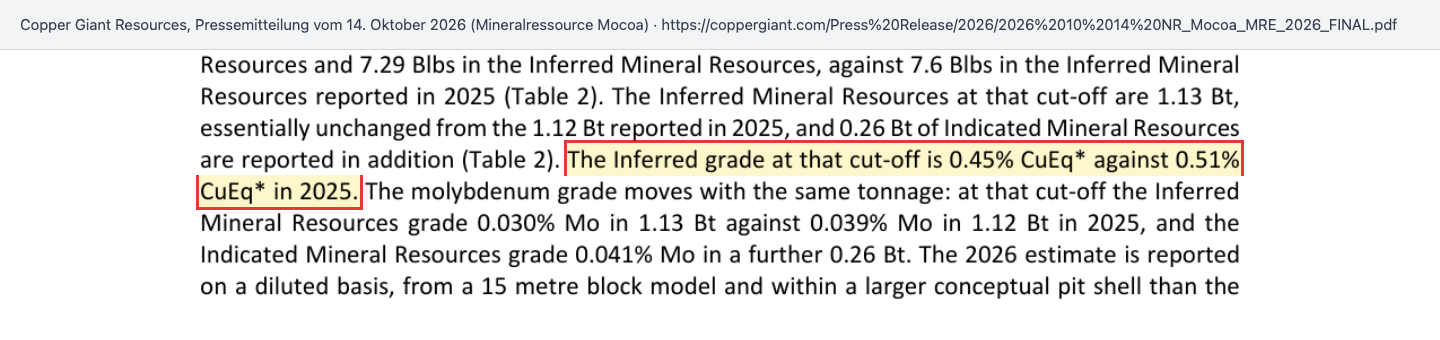
On a like-for-like basis, copper within the pit grows by 23 percent: 2.04 billion pounds Indicated plus 7.29 billion Inferred against 7.6 billion Inferred in 2025. The Inferred tonnage at that cut-off barely moves, at 1.13 billion tonnes. Part of the explanation is method: the new estimate is reported on a “diluted” basis, including the waste rock that inevitably comes along in mining — the old one was not. That is more honest, but it lowers the grade. Bottom line: Mocoa is bigger and better understood than a year ago, but on average it is not richer.
Uncomfortable Truth No. 2: The Math Assumes Higher Metal Prices
Whether rock counts as a resource depends on whether it could reasonably be mined at some point at given prices and costs. Those assumptions shifted noticeably between the two estimates:
“Economic assumptions used include US$4.75/lb Cu, US$25.00/lb Mo, process recoveries of 88% for Cu and 90% for Mo, a US$7/t processing cost, G&A costs of US$1.50/t, and a 3% NSR royalty.”
— Copper Giant Resources Corp., news release of October 14, 2026, note 6 to Table 1
For comparison, the MD&A as of June 30, 2026, lists the assumptions behind the November 2025 estimate: $4.00 per pound of copper, $20 per pound of molybdenum and a $10 per tonne processing cost. Higher prices and lower costs mean that lower-grade rock becomes mineable on paper, the pit gets bigger and the cut-off falls. That is not a trick but standard practice — and the recovery assumptions actually became more conservative (88 instead of 90 percent for copper). It does mean that part of the growth depends on copper and molybdenum prices. If they fall, the resource shrinks again on paper.
Uncomfortable Truth No. 3: It Runs on Outside Money — and the Money Costs Ownership
The treasury is well stocked, but it is still borrowed from the future — from future buyers of new shares. The interim statements as of June 30, 2026, put it plainly in their first note:
“The Company has not generated revenue from operations to date and will require additional financing or outside participation to undertake further exploration and subsequent development of its mineral properties.”
— Copper Giant Resources Corp., interim financial statements as of June 30, 2026, note 1, page 6
In its report on the 2025 financial statements dated April 23, 2026, the auditor flagged a material uncertainty related to going concern — at the December 31, 2025 balance sheet date, the company held C$8.6 million in cash. The situation has eased considerably since: C$16.8 million as of June 30, 2026, followed by another C$34.4 million. The interim statements themselves no longer contain the material-uncertainty language; the MD&A dated August 28, 2026, still contains it in its liquidity section: dependence on new equity represents “material uncertainties that give rise to significant doubt” about the company’s ability to continue as a going concern. At the second-quarter outflow of C$5.5 million, about C$51 million would last roughly nine quarters on paper — but with four drill rigs and the PEA, the pace is likely to rise. For a mine whose construction cost the PEA has yet to put a number on, the money is not enough.
How shares are handed out is part of the picture too. On March 11, 2026, directors, officers, employees and consultants received 8,650,000 options at C$0.94 with a ten-year term, almost all vesting immediately. Their calculated value was C$7.74 million; about C$7.5 million of it was expensed in the first quarter — almost two-thirds of the quarterly loss of C$11.5 million. C$5.95 million of the half-year option expense went to key management. On top of that come 81.8 million outstanding warrants with exercise prices between C$0.20 and C$0.60 (as of August 28, 2026; weighted average C$0.40 as of June 30, 2026), most of which can be exercised far below the market price; if all were exercised, about C$32 million would flow in by our rough estimate. That is a quiet cash reserve for the company and quiet dilution for you.
Uncomfortable Truth No. 4: One Project, One Country
At its core, Copper Giant is a single project in a single country. The newly integrated concession was explicitly reset to a new exploration stage; construction and mining stages still lie ahead of the project. The MD&A itself lists political uncertainty in Colombia, Canada and elsewhere, possible sanctions on Colombia and “violence and instability in Colombia” among its risks. Whether and when a mine is permitted is up to Colombian authorities — and their framework can change with every government. For investors, that means the project depends on permits from a country whose political risks the MD&A itself lists.
One appointment from August was withdrawn again. On August 6, 2026, Copper Giant announced that it would appoint Carlos Augusto Suárez Rojas to its board, the founder of the Bogotá consultancy Estrategia & Poder, which according to the release designed and executed, under his leadership, the strategy for the presidential campaign of Colombian President Abelardo De La Espriella. With the closing release of August 21, 2026, the company withdrew the appointment:
“Carlos Augusto Suárez Rojas, who was previously disclosed as an incoming director, will not be joining the board of directors due to potential upcoming conflict of interest.”
— Copper Giant Resources Corp., closing release of the placement, August 21, 2026, Corporate Update
The release does not say what conflict of interest is meant.
As for the partners in the August round: Denarius Metals, which itself produces gold in Colombia, holds about 15 percent with 40 million shares; according to the closing release, Frank Giustra reached 15.55 percent on a partially diluted basis; both of them and CEO Ian Harris may not sell the shares bought in the placement for two years (Denarius 40.0 million, Giustra 2.78 million, Harris 0.28 million). And commodity trader Trafigura secured the right and obligation to take 20 percent of the copper and molybdenum concentrate for ten years — from the start of commercial production, which does not exist yet.
“Copper Giant will grant Trafigura the right and obligation to purchase 20% of the copper concentrate and 20% of the molybdenum concentrate produced from the Mocoa Project.”
— Copper Giant Resources Corp., news release of August 6, 2026 on the Denarius financing and the Trafigura offtake agreement
With the offtake agreement, a major commodity trader secures part of future production early. But it is not money for construction, and it commits part of future production today. Anyone thinking about Mocoa should look at both halves together.
Valuation: What You Pay per Pound of Copper in the Ground
With 262,526,544 shares (August 28, 2026) and a TSX Venture closing price of C$0.84 on October 23, 2026, Copper Giant has a market value of about C$220.5 million. Subtracting the cash as of June 30, 2026, and the C$34.4 million received through August 28 leaves, by our rough estimate, an enterprise value of about C$170 million — actually somewhat more, because money has flowed out since July.
With no revenue or earnings, price-to-earnings and price-to-sales ratios are meaningless. The usual yardstick for explorers is the price per unit of metal in the ground. Spread over the 11.49 billion pounds of copper in the full resource, you pay about 1.5 Canadian cents per pound; on the 2.13 billion pounds in the Indicated category alone, it is about 8 cents.
Is that a lot or a little? The cleanest comparison is with the company itself. At the end of 2025, with 153,174,512 shares and a closing price of C$0.49, Copper Giant was worth about C$75 million; less C$8.6 million in cash, that left about C$66 million for the 7.6 billion pounds of copper in the November 2025 estimate — about 0.9 Canadian cents per pound. So the market now pays considerably more per pound than ten months ago, even though the grade has fallen on the old yardstick. A pound of copper in the ground is not a pound of copper on the market: between them lie an economic study, permits, construction financing and many years of time.
How differently the market values explorers at this stage is shown in our Mogotes Metals analysis, a copper-gold explorer in Argentina. There is hardly a “pros’ view” here: we found no verifiable analyst coverage of Copper Giant with a named author.
Opportunities and Risks at a Glance
Opportunities
- By the company’s own account one of the largest undeveloped copper-molybdenum deposits in the Americas, with 290 million tonnes in the Indicated category for the first time since October 2026.
- Higher-grade sections such as 103 metres at 1.07 percent copper equivalent (September 22, 2026 release) and about 10,000 drilled metres not yet in the estimate.
- C$16.8 million in cash as of June 30, 2026, plus C$34.4 million afterwards, and no bank debt.
- Strategic partners: Denarius Metals with about 15 percent, an offtake agreement with Trafigura, a two-year lock-up on the placement shares of Denarius, Frank Giustra and the CEO.
- Completed consultation with the Inga Condagua and an integrated concession with no forestry-reserve overlap.
- Preliminary Economic Assessment (PEA) announced for the fourth quarter of 2026 — the first number on economics.
Risks
- No reserves, no economic study, concession in its exploration stage; 85 percent of the tonnes are only “Inferred.”
- At the old cut-off, grade fell from 0.51 to 0.45 percent copper equivalent; the resource assumes $4.75 per pound of copper.
- Share count up sixteenfold since the end of 2023; 81.8 million warrants and 17.5 million options outstanding.
- One project in one country: the MD&A itself names political uncertainty, violence and possible sanctions as risks.
- Auditor’s material-uncertainty paragraph on going concern in the report dated April 23, 2026; the MD&A dated August 28, 2026, still contains it in its liquidity section.
- Royalties totaling 3 percent to B2Gold and AngloGold Ashanti, and 20 percent of concentrate already committed to Trafigura.
A Human Conclusion
Remember the billion-tonne trap from the start? Copper Giant gives it the perfect number, and the number is not wrong. Mocoa is huge, better drilled than ever, and the company has money, partners and a completed consultation with its neighbours. What the headline does not say sits three paragraphs further down: at the old yardstick the grade has fallen, the math uses higher metal prices, and every additional tonne was paid for with new shares.
The coming weeks bring hard checkpoints with dates: the technical report on the new resource by the end of November 2026, the interim statements as of September 30, 2026, and the economic study the company has announced for the fourth quarter. Only that study turns tonnes into a calculation with construction costs, operating costs and returns. Until then, 1.6 billion tonnes is a measure of size — not a valuation.
What you make of it is your decision. And that is how it should be.
Sources and Data Status
- Interim financial statements as of June 30, 2026 (not audited, approved on August 28, 2026) and MD&A as of June 30, 2026 (current to August 28, 2026) — latest periodic report, retrieved via the OTC Markets mirror of the SEDAR+ filings
- MD&A for fiscal 2025 and the 2025 consolidated financial statements with the auditor’s report dated April 23, 2026
- News release of October 14, 2026: updated Mocoa mineral resource estimate
- News release of August 6, 2026: Denarius Metals financing and Trafigura offtake and the closing release of August 21, 2026
- News release of September 16, 2026: Mira Geoscience targeting study and drill results of September 22, 2026
- News release of April 28, 2026: title integration and the releases of October 9, 2025 (Consulta Previa), November 24, 2025 (2025 resource), February 17, March 11, May 5 and September 9, 2026 in the company’s news archive
- Price, volume and metric data: source fundamental data, as of October 23, 2026
Data status: company figures as of June 30, 2026, or the date stated; shares, warrants and options as of August 28, 2026; resource effective September 24, 2026; price and market value as of October 23, 2026. The news archive was last checked on October 25, 2026; the latest release is dated October 14, 2026. All amounts in Canadian dollars unless marked as U.S. dollars ($).
Note: This article is journalistic analysis and not investment advice. It contains no recommendation to buy or sell and is not a solicitation to buy or sell securities. Shares of exploration companies without revenue are especially volatile; a total loss of the capital invested is possible. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this deep dive.
Our Bottom Line at a Glance
- Size of the deposit positive
- Since the estimate of October 14, 2026, Mocoa comprises 290 million tonnes of Indicated and 1.60 billion tonnes of Inferred resources containing 11.49 billion pounds of copper in total. About 10,000 drilled metres are not yet included.
- Ore quality negative
- At the old 0.25 percent cut-off, the Inferred grade fell from 0.51 to 0.45 percent copper equivalent and the molybdenum grade from 0.039 to 0.030 percent. The estimate assumes $4.75 instead of $4.00 per pound of copper.
- Financial strength positive
- As of June 30, 2026, the company held C$16.8 million in cash, followed by C$34.4 million from the placement and exercised rights; there is no bank debt. Operating cash outflow in the second quarter was C$5.5 million.
- Dilution negative
- Shares outstanding rose from 16.2 million at the end of 2023 to 262.5 million on August 28, 2026. 81.8 million warrants and 17.5 million options are outstanding; in March 2026, 8.65 million options at C$0.94 went to management and consultants.
- Confidence level and permits neutral
- No reserves, no economic study, concession in its exploration stage. Completed are the Consulta Previa with the Inga Condagua (October 2025) and the title integration (April 2026); the PEA is announced for the fourth quarter of 2026.
With Mocoa in Colombia, Copper Giant owns what it calls one of the largest undeveloped copper-molybdenum deposits in the Americas and on October 14, 2026, reported 1.6 billion tonnes of Inferred and, for the first time, 290 million tonnes of Indicated resources. At the old cut-off, the grade fell from 0.51 to 0.45 percent copper equivalent, and the math uses higher metal prices. Everything is financed with new shares: 262.5 million in August 2026 after 16.2 million at the end of 2023. After the Denarius Metals placement, the treasury is well stocked; an economic study is still missing. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
Yellow, because the central operational question is open: whether Mocoa can be mined economically at a grade of 0.40 to 0.54 percent copper equivalent will only be shown by the PEA announced for the fourth quarter of 2026. Red would be wrong in our assessment: the auditor did flag a material uncertainty related to going concern in April 2026, and the MD&A dated August 28, 2026, still contains it in its liquidity section. But the interim statements as of June 30, 2026, no longer contain that language, management believes resources are sufficient for twelve months, and with about C$51 million from cash and inflows through the end of August, the money lasts well over four quarters at the second-quarter pace, with no bank debt. Green is ruled out as long as there are no reserves and no economic study. This rating has nothing to do with the share price. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- This analysis was prompted by wallstreet-online’s list of hotly discussed and searched-for stocks (October 2026), not by a scanner hit. We carry the company under its home listing CGNT on the TSX Venture Exchange (internally CGNT.TO); the U.S. symbols CGNRF (previously LBCMF) and the Frankfurt symbol 29H0 refer to the same stock.
- Copper Giant is not an SEC reporting company. All company figures come from the Canadian disclosure documents (SEDAR+), retrieved via the OTC Markets mirror of the filings and the company’s news archive: interim statements and MD&A as of 06/30/2026 (current to 08/28/2026), 2025 annual statements and MD&A, and news releases through 10/14/2026. The statements for 09/30/2026 had not been filed as of 10/25/2026.
- Calculated values are our rough estimates: market value from 262,526,544 shares (08/28/2026) times the 10/23/2026 closing price; enterprise value net of the 06/30/2026 cash and the C$34.4 million received through 08/28/2026, before funds spent since July; value per pound of copper on the 11.49 Blbs of the full resource; warrant potential from the expiry table as of 06/30/2026 less warrants exercised and expired afterwards.
- Possible confusion: until May 2025 the company was called Libero Copper & Gold Corporation (U.S. symbol LBCMF). All share counts before February 2024 are adjusted for the ten-for-one consolidation.
Stock Watch
This analysis is as of October 25, 2026. Stock Watch will tell you what's changed at CGNT.TO since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Copper Giant Resources Corp. (CGNT.TO), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Copper Giant is a Canadian copper-molybdenum explorer based in Vancouver; until May 2025 it was called Libero Copper & Gold. It owns 100 percent of the Mocoa porphyry deposit in southern Colombia. The company drills, estimates resources and is preparing a first Preliminary Economic Assessment (PEA) for the fourth quarter of 2026. It has no revenue.
According to the estimate effective September 24, 2026 (reported October 14, 2026): 290 million tonnes Indicated at 0.54 percent copper equivalent and 1.60 billion tonnes Inferred at 0.40 percent, containing 11.49 billion pounds of copper in total. At the old 0.25 percent cut-off, the Inferred grade fell from 0.51 to 0.45 percent. There are no reserves.
For ongoing exploration, yes: as of June 30, 2026, it held C$16.8 million in cash, followed by C$31.0 million from a placement and C$3.4 million from exercised warrants and options; there is no bank debt. That is not enough to build a mine. In April 2026, the auditor flagged a material uncertainty related to going concern.
Adjusted for the ten-for-one consolidation of February 2024, there were 16.2 million shares at the end of 2023; on August 28, 2026, there were 262,526,544. Another 81.8 million warrants and 17.5 million options are outstanding; fully diluted, that would be about 361.8 million shares.
Denarius Metals subscribed for 40 million shares at C$0.72 in August 2026 and holds about 15 percent. According to the closing release of August 21, 2026, Frank Giustra reached 15.55 percent on a partially diluted basis. Denarius, Giustra and CEO Ian Harris may not sell the shares they bought in the placement for two years.
Copper Giant is a Canadian company with its home listing on the TSX Venture Exchange and reports under Canadian law (National Instrument 51-102) via SEDAR+: audited annual statements with an MD&A and unaudited quarterly interim statements. The U.S. symbol CGNRF trades over the counter on the OTCQX without SEC reporting obligations.
Its home market is the TSX Venture Exchange under CGNT, traded in Canadian dollars. In the U.S., the stock has traded as CGNRF on the OTCQX since September 9, 2026 (previously LBCMF on the OTCQB), and in Frankfurt as 29H0; the ISIN is CA21750C1014. Buying in U.S. dollars adds currency risk against the Canadian dollar.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.