ASP Isotopes Stock: Five Future Stories, a $255 Million War Chest — Still No Isotope Revenue, and Shipments Slipped Again
Since July, the ASP Isotopes share price has nearly halved, the first isotope shipments have been pushed back again, and the CEO tells shareholders he is "as frustrated" as they are. Yet the company promises several megatrends at once: nuclear medicine, silicon-28 for quantum computers, HALEU nuclear fuel for TerraPower, helium from South Africa. We read the annual reports (10-K) for 2024 and 2025, the quarterly reports (10-Q) through June 30, 2026, and every current report through early October 2026: still zero revenue from enriched isotopes after the second quarter, first shipments pushed into the second half, 76 percent of 2025 revenue from a Hong Kong road-construction side business — and a share count that has more than tripled since the end of 2023. Against that stands a $255 million war chest. Not investment advice — just an inventory of which of the five stories actually earns money yet (updated October 2, 2026).
 Thomas Mücke
Founder & Publisher
As of Today
As of: November 2, 2026
- Closing price
- 1.90 $ -4.00%
- Market Capitalisation
- 0.2 $B
- Growth Score
- 5/10
- AAQS
- 4/10
Price change since August 4, 2026: -53.7%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot

Chart
Interactive price chart (TradingView).
52-week range: 1.90 $ to 9.20 $ · Last price: 1.90 $ (As of: November 2, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
Update of October 2, 2026: share price down from $5.01 to $2.70 (closes of July 10 and October 1, 2026), first isotope shipments pushed back again, the first insider purchase since July, by a board member — everything new is in the chapter "Update October 2026" and has been worked into the other chapters.
There is an investor trap that catches the curious ones in particular: the sticker-album trap. It works like this: a stock offers not one future story but five at once — cancer medicine! quantum computers! the nuclear renaissance! a helium shortage! — and instead of rigorously checking a single one, your mind pastes all five into the album and feels five times as safe. The opposite is true: five promises are five times the homework. A textbook example of that album is ASP Isotopes Inc. (Nasdaq: ASPI) of Dallas: an enricher of rare isotopes with plants in South Africa, whose customer list features TerraPower — the nuclear company backed by Bill Gates. The stock landed on our desk in July 2026 via a faint Reddit signal (more on that below). So let’s make a deal: before you fill the album, we read together what the company itself reported, under penalty of law, to the U.S. securities regulator, the SEC — the annual reports (10-K) for 2024 and 2025, the quarterly reports (10-Q) through June 30, 2026, and every current report through early October 2026. And these filings contain one sentence that turns the whole album upside down: the company has not yet earned a single dollar from enriched isotopes. In the end, you decide for yourself.
Update October 2026: What the second quarter shows
The stories are getting longer, the cash pile shorter. Since our first edition in July 2026, the first isotope shipments have been pushed back again, the share price has nearly halved, CEO Paul Mann writes to shareholders himself: "we are as frustrated as the rest of the shareholders" — and for the first time since July a board member has bought shares. The evidence is in the quarterly report (10-Q) as of June 30, 2026, filed on time this time on August 14, 2026, and in a good dozen further current reports.
The numbers behind it: Revenue came to $5.1 million in the second quarter after $1.2 million in the prior-year quarter — $3.9 million from the radiopharmacies, $0.7 million from liquefied natural gas (LNG) sold by the Renergen plant and $0.6 million of collaboration revenue from TerraPower. That adds up to $9.3 million for the first half (prior year: $2.3 million). The net loss fell to $33.6 million (prior-year quarter: $75.1 million) — but only because the fair-value loss on the company’s own convertible notes shrank from $63.8 million to $3.5 million. The company’s own adjusted measure (the "headline loss," which strips out those marks) points the other way: from $11.2 million to a $30.1 million loss. Selling, general and administrative expenses rose to $28.9 million for the quarter, research and development to $6.8 million. Operating cash outflow reached $41.1 million in the first half, and liquidity shrank within three months from $290.5 million to $254.9 million ($219.6 million in cash plus $35.3 million in short-term investments as of June 30, 2026).
And the core business? The quarterly report repeats the sentence this analysis revolves around, now with a new cut-off date:
"We commenced commercial production of enriched isotopes at both of our ASP enrichment facilities located in Pretoria, South Africa during the first half of 2025. However, we have not generated any revenue from the sale of our enriched isotopes as of June 30, 2026."
— ASP Isotopes Inc., SEC quarterly report 10-Q as of 06/30/2026, Item 2 "Management’s Discussion and Analysis"
The dates have slipped: the 2025 annual report targeted first commercial shipments of silicon-28 for the second quarter of 2026 and of carbon-14 for mid-2026; the quarterly report as of March 31, 2026, then said Si-28 "around mid-year" and C-14 and ytterbium-176 in the third quarter. Now the 10-Q names only the second half of 2026 for all three. The reasons are in the shareholder letter the company furnished on August 4, 2026, as its earnings release (8-K, Item 2.02): more than 200 compressors from a former supplier had to be upgraded in the Si-28 plant because they were not helium-tight — enrichment has reached 98 percent so far, initial product is to ship at 99 percent, while quantum computing requires 99.995 percent. For C-14, the Canadian customer’s feedstock has not yet arrived in sufficient quantities, and the ytterbium plant went down after a power surge broke a laser in the second half of 2025, restarted only in the first quarter of 2026 and still needs a vessel for continuous operation to reach commercial volumes.
ASP Isotopes did not hold a conventional earnings call. Instead, management took analysts’ questions at its first Capital Markets Day in London on September 8, 2026, excerpts of which are on file with the SEC as Form 425. Three statements from it, from the shareholder letter and from the press releases matter to you: first, Renergen is to deliver liquid helium — the shareholder letter named the start of production before September 30, 2026, the press release of August 20, 2026, first deliveries to customers in September, and at the Capital Markets Day management said "commercial product" should come by the end of September — and ENDRA’s registration statement (S-4) of October 2, 2026, now expects the first commercial liquid helium delivery only in the fourth quarter of 2026 ("commercial liquid helium delivery expected during the fourth quarter of 2026"), so this date has already slipped once too. Second, management forecasts about $14 million of 2026 revenue for the PET Labs group (the radiopharmacies), after $6 million in 2025. Third, management names a 2031 target of more than $300 million of EBITDA (earnings before interest, taxes, depreciation and amortization) — expressly without a reconciliation to audited figures, because the future values are "not available without unreasonable effort." That is a target, not a forecast with a worked calculation. Bottom line, the first invoiced isotope shipment remains the event everything has to be measured against. We work the consequences for share count, debt and valuation into the respective chapters below.
Company history for investors
-
2025
Commercial production begins in Pretoria
Both ASP enrichment plants commence commercial production in the first half of 2025 — the first operational proof of the core technology.
-
2025
Acquisition of Skyline Builders
In August 2025 subsidiary Quantum Leap Energy acquires a 79 percent voting stake in Hong Kong builder Skyline — deconsolidated again effective March 29, 2026.
-
2026
Acquisition of Renergen
Since January 2026 South African helium and LNG producer Renergen belongs to the group, paid for with 14.27 million new shares — and slated to be spun out again via a merger with ENDRA.
-
2026
Note exchange for 23.2 million shares
In July 2026 QLE noteholders swap roughly $109.2 million of principal for new ASPI shares — the largest single dilution jolt for shareholders so far.
-
2026
First shipments postponed
The August 2026 quarterly report names only the second half of 2026 for the first isotope shipments; through June 30 there was still no isotope revenue.
What ASP Isotopes actually does — and what it doesn’t
Isotopes are atoms of the same element with different weights — carbon is not just carbon. Many high-tech applications need one particular variety in extreme purity, and that is exactly what ASP Isotopes is aiming at: the company builds sorting machines for atoms. The technology — the Aerodynamic Separation Process ("ASP") and the Quantum Enrichment ("QE") technology — came with the acquisition of assets from the South African firm Klydon; two enrichment plants in Pretoria commenced commercial production in the first half of 2025, per the annual report (10-K) for 2025. With them, the company wants to serve three markets at once: nuclear medicine (carbon-14 for drug research, ytterbium-176 as the feedstock for the cancer therapeutic lutetium-177 — plus a growing network of its own radiopharmacies in South Africa and the U.S., including the 51 percent stake in PET Labs), semiconductors (silicon-28, regarded as the ideal host material for quantum computers; three purchase agreements are signed) and nuclear fuels: subsidiary Quantum Leap Energy ("QLE") is to produce HALEU — higher-enriched uranium for the next generation of small reactors — and lithium-6, with TerraPower as its first contracted customer and a standalone listing as the declared plan. Since January 2026 the group has also included South African helium and LNG producer Renergen (Virginia Gas Project) — which, however, is already on its way back out; more on that below. Sounds like a peddler’s tray? In parts it is — in 2025 the group even included a Hong Kong road builder. Which brings us to the central tension of this analysis, running through every chapter: ASP Isotopes has real plants, real contracts and a real war chest — but the core business the market is paying for has no revenue yet, and the group rebuilds itself faster than an annual report can portray it. How quickly big narratives turn into dilution is something we dissected at Eos Energy — and what it looks like when a capital-hungry buildout is paid for in fresh shares, at Amprius.
Where the stock shows up in our scanner — and where it doesn’t
We run roughly 3,500 stocks through our scanners every day. ASP Isotopes reached the research list via the Reddit hype run — and delivers a remarkable pattern there: just 2 mentions in 24 hours, but a jump from rank 785 to rank 233 (ApeWisdom, as of July 17, 2026). Attention building, no noise yet. The following scanner figures are a snapshot from July 2026, when the stock landed on our desk. In the ranking filters of our in-house stock scanner, the stock did not appear at all at the time (data as of July 10, 2026) — not in the quality rankings, not in the value rankings, not in the trend rankings. The stock page’s metrics explain why: the Piotroski F-Score — a nine-point test of the direction of the books — stands at a meager 2 of 9, the price-to-sales ratio was around 30 at the time (see below for today’s valuation), and a P/E ratio does not exist for lack of profits. The Altman Z-Score (an early-warning gauge for financial distress) sits around 4 thanks to the full cash box — above the danger zone — and the fundamental grade of B owes more to the balance-sheet cushion and growth pace than to earning power. Two more things stand out (both data as of July 10, 2026): institutional investors added on balance (10 buyers versus 5 reducers, roughly $16 million net) — while the insider data showed 19 sales and not a single purchase, including sales by the CEO. Since then the picture has turned slightly (Form 4 filings through October 1, 2026): CEO Paul Mann, COO Robert Ainscow and General Counsel Donald Ainscow sold shares in early September at prices around $3.90 to $4.30 — Paul Mann and Robert Ainscow, per the filings, under pre-arranged trading plans (Rule 10b5-1). Per Form 4, all of Paul Mann’s reported sales (roughly 251,000 shares from September 2 to 4, 2026) served only to cover taxes on vested stock awards; he still held roughly 9.3 million shares afterward. For Robert Ainscow, that applied to part of the sales; in Donald Ainscow’s case, the company sold the shares automatically to cover taxes. And at the end of September, board member Robert Ryan became the first insider to buy since our first edition: 23,000 shares at roughly $2.68 to $2.70 (purchases on September 28 and 30, 2026). Another board member, Todd Wider, had however filed a Form 144 on September 25, 2026, giving notice of a planned sale of up to 200,000 shares (market value per the notice roughly $590,000); no Form 4 reporting a completed sale had been filed by October 1, 2026. Still, remember the pattern: when a stock appears in no quality ranking but wants to be on everyone’s lips, the story is carrying the valuation — not the books.
The numbers over the years — honestly appraised
First, what genuinely impresses — and here that is not revenue, but the ability to raise capital and put plants on the ground. In 2025 alone, ASP Isotopes took in $371.6 million from financing activities, including an October 2025 stock offering that raised roughly $199.3 million net at $12.25 per share. The result: $285.6 million in cash plus $47.7 million in short-term investments as of December 31, 2025 (as of March 31, 2026: $207.3 million plus $83.2 million; as of June 30, 2026: $219.6 million plus $35.3 million — $254.9 million combined). Both Pretoria plants commenced commercial production in the first half of 2025, per the annual report; first commercial shipments of enriched C-14 and Si-28 are now targeted for the second half of 2026 — and the C-14 offtake agreement with a Canadian customer carries a take-or-pay clause of roughly $2.5 million per year. Reported revenue jumped too: from $4.1 million (2024) to $23.8 million (2025), and continuing operations generated $4.2 million in the first quarter of 2026 (prior year: $1.1 million) and $5.1 million in the second (prior year: $1.2 million) — carried by the radiopharmacy acquisitions and, for the first time, LNG from Renergen. Read only this paragraph and you see a growth company on the verge of a breakout. Now look at what that revenue was made of:

And the bottom line? The company lost $32.4 million in 2024, then $159.8 million in 2025 — on $23.8 million of revenue. Selling, general and administrative expenses alone nearly doubled to $48.2 million, plus $12.4 million of research and development. And even those figures tell only half the story, because the largest loss item was not an operating one at all — more on that in a moment. Remember the rhythm: at ASP Isotopes, three things have grown reliably so far — the cash pile, the cost base and the share count. Which brings us to the uncomfortable truths.
What the filings say — the uncomfortable truths
Uncomfortable truth no. 1: The core business has not earned a dollar yet — three quarters of 2025 revenue was road construction
The most important line of the entire annual report sits inconspicuously in the liquidity discussion — and it clarifies what ASP Isotopes, despite production being under way, is not yet: a seller of isotopes.
"We have not generated any revenue from the sale of our enriched isotopes, and our ability to generate product revenue from the sale of enriched isotopes sufficient to achieve profitability on a consolidated basis will depend on the continued successful development and commercialization of our current or future enriched isotopes."
— ASP Isotopes Inc., SEC annual report 10-K for 2025, Item 7 "Management’s Discussion and Analysis"

So where did the $23.8 million come from? $5.7 million from the product business — essentially nuclear medical doses sold by the radiopharmacy subsidiaries in South Africa and the U.S. And $18.2 million from Hong Kong: in August 2025, nuclear-fuels subsidiary QLE had acquired a 79 percent voting interest in builder Skyline Builders (Nasdaq: SKBL), which performs road and drainage works. The concentrations footnote makes the consequence official: "Revenues from two customers in our construction services segment represent approximately 32.2% ($7.7 million) and 13.7% ($3.3 million), respectively, of our consolidated revenues for the year ended December 31, 2025" (10-K 2025, Item 7A "Quantitative and Qualitative Disclosures About Market Risk," section "Major Customers"). Nearly half the consolidated revenue of a nuclear technology company thus hung on two construction customers in Hong Kong in 2025 — and since March 29, 2026, Skyline has been deconsolidated again (retained stake roughly 8.6 percent, gain on deconsolidation $19.3 million). In fairness: the continuing business is genuinely growing — to $9.3 million in the first half of 2026 after $2.3 million — and the C-14 and Si-28 shipments now targeted for the second half of 2026 could bring the first real isotope revenue. But as of the filings we read, this holds: the five stories in the album have together produced less revenue than a single road site in Hong Kong.
Uncomfortable truth no. 2: A $159.8 million loss — the largest item comes from the company’s own convertible notes
At first glance the 2025 net loss is a shock number: almost five times the prior year, more than six times revenue. The annual report states it plainly:
"For the years ended December 31, 2025 and 2024, we reported a net loss of $159.8 million and $32.4 million, respectively. As of December 31, 2025, we had an accumulated deficit of $231.3 million."
— ASP Isotopes Inc., SEC annual report 10-K for 2025, Item 1A "Risk Factors"

What matters is the anatomy of that loss. The operating loss was $59.9 million — a lot, but not exotic for a company in plant buildout. The largest single item sits below it: a $123.7 million fair-value loss on the company’s own convertible notes ("change in fair value of convertible notes payable"). In an everyday image: subsidiary QLE borrowed money through notes that will later convert into shares — and because the market value of those conversion rights rose along with the hopes priced into the stock, the group has to mark its own debt up and book the difference as a loss. That costs no cash, but it is no accounting blemish either: as of December 31, 2025, these notes stood at $199.3 million on the balance sheet (June 30, 2026: $203.4 million), and they get settled in equity — shareholders pay that bill in the currency of dilution. July 2026 showed how concrete that gets: roughly half the notes were exchanged not into equity of the subsidiary but directly into ASP Isotopes stock (more on that in truth no. 3). Even the company’s own adjusted measure (the "headline loss," a South African reporting tradition) came to a $69.2 million loss for 2025 (in the recast of July 16, 2026: $69.4 million) — and already $36.4 million in the first half of 2026. The operating cash outflow was real: $37.8 million (2024: $16.7 million; $41.1 million in the first half of 2026 alone). Remember the distinction: a loss from fair-value marks spares the cash box — but it is the price tag of growth being paid for with future shares.
Uncomfortable truth no. 3: The share count has more than tripled since the end of 2023
Which brings us to the currency in which ASP Isotopes actually pays for its growth: its own stock. The series from the equity statements reads like a time-lapse:

From December 31, 2023 (48.9 million shares) through December 31, 2024 (72.1 million), December 31, 2025 (111.7 million) and June 30, 2026 (130.1 million) to August 14, 2026 (153,309,380 shares per the cover of the quarterly report), the count has more than tripled — up 213 percent in a little over two and a half years. The biggest single jolt came in July 2026 (agreed on July 15, closed on July 16): holders of convertible notes issued by subsidiary QLE exchanged roughly $109.2 million of principal plus accrued interest for 23,160,682 new shares of ASP Isotopes — about $4.71 of note principal per new share, plus accrued interest, against a closing price of $4.58 on the day before closing (8-K of July 16, 2026, on the event of July 15; price per the S-3ASR prospectus of July 16, 2026). The new shares were registered for resale right away. Management calls the exchange "broadly economically neutral" and justifies it with the aim of later distributing QLE equity to its own shareholders in a tax-efficient way. Per the 10-Q, roughly $80.6 million of principal of these notes remains with third parties. Your slice of the cake shrinks when new slices keep being cut: whoever owned one percent of the company at the end of 2023 owns roughly 0.32 percent today. The loss per share was $2.11 in 2025 (2024: $0.63) and $0.33 in the first half of 2026. Fairness requires adding: a pre-revenue company must finance itself with equity, and ASP Isotopes has at times done so at strong terms — the October 2025 offering raised $199.3 million net at $12.25 per share, more than four times the closing price of October 1, 2026 ($2.70). You should simply know which side of these transactions you are on as a buyer: growth paid for with fresh shares is never entirely free — in 2026 it was paid for in two big jolts, in January and in July.
Uncomfortable truth no. 4: Star customer TerraPower may cancel at any time, without cause
The strongest card in the album is nuclear fuel: TerraPower — the reactor company co-founded by Bill Gates — has signed two supply agreements with ASP Isotopes for HALEU (higher-enriched uranium, the fuel of the next reactor generation) and in May 2025 committed a loan of up to $22 million toward building a uranium enrichment facility in South Africa (10 percent interest, maturing May 2032; the company plans first drawdowns from the third quarter of 2026). That is a genuine vote of confidence — a customer helping finance its supplier’s factory. But the risk section of the same annual report hangs a price tag on that vote of confidence:
"The HALEU supply agreements with TerraPower are terminable, for convenience, at TerraPower’s sole election; accordingly, QLE may never realize any revenue or profit as a result of these agreements."
— ASP Isotopes Inc., SEC annual report 10-K for 2025, Item 1A "Risk Factors" (Quantum Leap Energy)

Add the location question the report itself raises: the enrichment is to happen in South Africa — producing HALEU there requires licenses, permits and political goodwill on several continents, and TerraPower’s loan disbursements are expressly tied to such conditions. None of this makes the agreements worthless; the take-or-pay clause in the C-14 business and the co-financed factory suggest the partners are serious. But a contract the customer can end at any time without consequences is not a backlog — it is a signed statement of intent. Here the album pastes in a promise, not a result.
Uncomfortable truth no. 5: Late filings, a control weakness and a class action
How reliable are the numbers themselves? The annual report for 2025 arrived only after a deadline extension (NT 10-K) on April 10, 2026 — and had to be amended by a 10-K/A on April 30; the quarterly report as of March 31, 2026, was likewise filed only after an extension (NT 10-Q) on May 20. The report as of June 30, 2026, by contrast, arrived on time. Management itself attests a material weakness in its own reporting apparatus — and writes in the 10-Q as of June 30, 2026, that it cannot "at this time" estimate how long remediation will take:
"The material weakness identified relates to the lack of formal control documentation and consistent execution of control procedures, and the lack of a sufficient complement of personnel within the finance and accounting function with an appropriate degree of knowledge, experience and training."
— ASP Isotopes Inc., SEC annual report 10-K for 2025, Item 9A "Controls and Procedures"

Then there is legal history: in November 2024, a short-seller report about the company was published and the stock fell — and on December 4, 2024, a shareholder filed a putative securities class action in the U.S. District Court for the Southern District of New York (Corredor v. ASP Isotopes Inc., Case No. 1:24-cv-09253), alleging materially misleading statements by the company, its CEO and its CFO between October 30 and November 26, 2024; no court has found these allegations to be true. The parties have since reached an agreement in principle to settle: the court preliminarily approved it on July 9, 2026, and the final approval hearing is set for December 15, 2026; the 10-Q does not state a settlement amount. In addition, four shareholder derivative suits against board members were filed in 2026 (Jenis, Stewart, Albers, Manrique; Texas and New York), two of which were stayed in July 2026 in light of settlement discussions. And finally a governance detail: on August 29, 2025, CEO Paul Mann bought Skyline shares and warrants for $2.5 million as an individual investor — in the very Hong Kong construction group that group subsidiary QLE was acquiring in parallel — and became Executive Chairman of Skyline effective January 1, 2026. The annual report discloses this (10-K 2025, note on the Skyline acquisition); it remains a double role that fits the picture of unusually high complexity. None of this is a verdict on its own. Taken together, though, it means: a group that buys, re-hangs and sells off companies within months is running on a reporting function it has itself certified as weak.
Valuation: $414 million of market value for five options and $255 million of cash
The share price has nearly halved since our first edition: from $5.01 (close of July 10, 2026) to $2.70 (close of October 1, 2026). With 153,309,380 shares, that comes to roughly $414 million of market value — cross-checked against the $2.68 price of board member Robert Ryan’s purchase on September 30, 2026, reported on Form 4 on October 1, 2026. Classic metrics only help so much here: a P/E ratio does not exist (losses). The price-to-sales ratio sits around 33, calculated on trailing four-quarter continuing revenue of roughly $12.7 million (full-year 2025 excluding Skyline $5.7 million per the recast figures of July 16, 2026, minus the first half of 2025 at $2.3 million, plus the first half of 2026 at $9.3 million). Let’s count differently: subtract the $254.9 million of cash and short-term investments (June 30, 2026) and the market is paying roughly $159 million for the operating package — that is, for five options: the radiopharmacy business (the only one with running revenue), the first C-14, Si-28 and Yb-176 shipments in the second half of 2026, the HALEU project with TerraPower including the planned QLE listing, the Renergen value after the announced Noble Africa spin-out (per the S-4 registration statement, ASP Isotopes together with the other Noble investors will hold roughly 89.4 percent afterward, ASP Isotopes alone roughly 26.2 percent of the Class A shares and all Class B shares with roughly 98.9 percent of the votes; closing is planned for the fourth quarter of 2026, and per the S-4 the agreement can be terminated if it has not closed by December 31, 2026 — the 10-Q still named December 24), and the 8.6 percent remainder of Skyline (carrying amount $24.9 million as of June 30, 2026). Two caveats belong here: the end-of-June cash pile is likely smaller after third-quarter outflows, and Renergen carries roughly $57 million of loans against it (June 30, 2026), of which roughly $45 million with the DFC, the IDC and Standard Bank, part of which have breached covenants (formally "in default"; more in our side-finds). On top of that comes a new commitment: with an addendum of September 29, 2026, ASP Isotopes raised its intra-group credit line for Renergen from $80 million to up to $120 million, which the merger agreement amendment of October 1, 2026, permitted; by the closing of the merger it is to rise to up to $200 million. $56.8 million was outstanding as of May 31, 2026 (ENDRA’s 8-K of October 1 and registration statement on Form S-4 of October 2, 2026). A credit line is not a drawdown — but it shows where a growing share of the cash can flow: into the helium business, in which outside shareholders will also hold a stake after the merger. How long the cash lasts can be roughly estimated: in the first half of 2026, $41.1 million went out in operations and $10.2 million into plant and equipment, together a good $25 million per quarter. At that pace, the $254.9 million would last roughly ten quarters on paper — excluding acquisitions, investments, debt repayments or the helium Phase 2 buildout, and therefore a rough estimate, not a forecast. Each of the five options may prove valuable; none of them demonstrably is today. Whoever buys today pays a much smaller hope premium than in July — but is still buying a bundle of bets that has so far mostly produced new shares.
Opportunities and risks at a glance
What speaks for ASP Isotopes:
- A war chest that buys time: $219.6 million in cash plus $35.3 million in short-term investments (June 30, 2026); per the 10-Q, the company expects its funds to last more than twelve months from the issuance of the financial statements (August 14, 2026).
- Real plants instead of paper plans: both ASP enrichment facilities in Pretoria commenced commercial production in the first half of 2025 per the annual report; first shipments of C-14, Si-28 and Yb-176 are targeted for the second half of 2026, three Si-28 purchase agreements and a C-14 contract with a take-or-pay clause (~$2.5 million per year) are signed.
- A customer co-financing the factory: TerraPower signed two HALEU supply agreements and a loan of up to $22 million (May 2025) for the planned uranium enrichment facility, with first drawdowns planned from the third quarter of 2026 — plus the option of listing subsidiary Quantum Leap Energy separately.
- The continuing business is growing fast: $9.3 million of revenue in the first half of 2026 after $2.3 million a year earlier — carried by the radiopharmacy network in South Africa and the U.S. plus LNG; Renergen’s helium plant has been in commissioning since August 2026 (first commercial delivery expected in the fourth quarter of 2026 per the S-4), and the Noble Africa deal could make the Renergen value visible.
- The hope premium has shrunk: net of liquidity as of June 30, 2026, the market is paying roughly $159 million for the operating package (price $2.70 on October 1, 2026; outflows since the end of June are not yet reflected), and at the end of September a board member bought shares for the first time since July.
What speaks against it:
- The core business has no revenue yet: not one dollar from enriched isotopes through June 30, 2026 (10-Q), and first shipments have slipped again; 76 percent of 2025 revenue came from the since-deconsolidated Hong Kong construction business.
- Rising losses, heavy dilution: a "headline loss" of $30.1 million in the second quarter of 2026 after $11.2 million a year earlier, $41.1 million of operating cash outflow in the first half; share count up from 48.9 million to 153.3 million (+213 percent since the end of 2023), 23.2 million new shares from the July 2026 note exchange alone.
- The most important contract is one-sidedly terminable: TerraPower may end both HALEU agreements at any time without cause — "QLE may never realize any revenue or profit as a result of these agreements" (10-K 2025).
- Debt with strings attached: per the 10-Q, covenants on Renergen’s loans from the DFC ($22.8 million) and the IDC ($8.5 million) have been breached (formally "in default"); the extended Standard Bank loan requires waivers by November 30, 2026, and its cross-default clause also covers debt of the parent.
- Governance baggage: an ongoing material weakness in internal controls, two late filings in 2026 (NT 10-K, NT 10-Q) plus a 10-K/A, a class action in settlement proceedings (hearing December 15, 2026), four derivative suits against board members, the CEO’s private investment in acquisition target Skyline — plus a permanent rebuild and location, permitting and currency risks in South Africa.
A human conclusion
Back to the sticker-album trap from the beginning. Its trick is not that the pictures are fake — Pretoria is producing, TerraPower has signed, the helium in South Africa is real. Its trick is that abundance itself feels like proof: five stories can’t all fail. They can’t — but they don’t all have to succeed either, and today you are paying for all five. The inventory from the filings is more sober: one business earns money in a small way (radiopharmacy), one was bought and sorted out again within seven months (road construction), one has been bought and is already on its way back out (helium), and the two big ones — Si-28 and HALEU — are still waiting for their real test: the first shipments we noted for mid-2026 back in July now sit in the second half, and the contract partner may exit at any time. Add a reporting function with a certified weakness and a share count that has more than tripled in a good two and a half years. That is exactly how the sticker-album trap works over time: in your head, every postponed sticker is easily pasted over with the next story — yesterday quantum computers, today the helium shortage, tomorrow the 2031 EBITDA target. Our honest translation: this is not an investment album, it is a betting slip with five fields — funded by a war chest that is shrinking but can keep the game going for a while yet. If the first C-14 or Si-28 shipments are actually invoiced — or the helium first announced for September and now expected in the fourth quarter of 2026 demonstrably reaches customers — the album gets its first redeemed sticker. Until then: check each story one at a time, the way the filings do — not as a bundle. What you make of it is your decision. And that is exactly as it should be.
Sources
All original documents used in this analysis — for your own reading:
- ASP Isotopes Inc. — SEC annual report 10-K for 2025 (filed April 10, 2026, after an NT 10-K extension; amended by the 10-K/A of April 30, 2026)
- ASP Isotopes Inc. — SEC annual report 10-K for 2024 (filed March 31, 2025)
- ASP Isotopes Inc. — SEC quarterly report 10-Q as of 06/30/2026 (filed August 14, 2026)
- ASP Isotopes Inc. — 8-K of August 4, 2026, Item 2.02: shareholder letter on the second quarter of 2026 (Exhibit 99.1)
- ASP Isotopes Inc. — 8-K of July 16, 2026 (event of July 15): exchange of QLE convertible notes for 23,160,682 shares and S-3ASR prospectus of July 16, 2026 (resale of those shares)
- ASP Isotopes Inc. — 8-K of July 16, 2026: 2025 figures recast without the discontinued construction business
- ASP Isotopes Inc. — 8-K of August 20, 2026: extension of the Standard Bank of South Africa loan to Renergen, including the Put Option Agreement
- ASP Isotopes Inc. — press release of August 20, 2026 (helium plant commissioning) and Form 425 of September 9, 2026 (transcript of the Capital Markets Day of September 8, 2026)
- ASP Isotopes Inc. — 8-K of October 2, 2026 (reference to the registration statement for the Renergen merger); ENDRA Life Sciences Inc. — 8-K of October 1, 2026 (amendment to the merger agreement) and registration statement on Form S-4 of October 2, 2026
- ASP Isotopes Inc. — insider filing (Form 4) of October 1, 2026 (purchase by Robert Ryan)
- ASP Isotopes Inc. — notice of proposed sale (Form 144) of September 25, 2026 (Todd Wider)
- ASP Isotopes Inc. — SEC quarterly report 10-Q as of 03/31/2026 (filed May 20, 2026, after an NT 10-Q extension)
- ASP Isotopes Inc. — SEC quarterly report 10-Q as of 09/30/2025 (filed November 19, 2025)
- ASP Isotopes Inc. — SEC quarterly report 10-Q as of 06/30/2025 (filed August 14, 2025)
- ASP Isotopes Inc. — 8-K of June 25, 2026: Agreement and Plan of Merger (Noble Africa / ENDRA Life Sciences)
- ASP Isotopes Inc. — Form 425 of July 17, 2026 (investor webinar on the Noble Africa spin-out)
- Complete SEC filing history of ASP Isotopes Inc.: EDGAR overview (sec.gov)
- Fundamental data (metrics, quarterly series; data as of July 10, 2026, prices through the close of October 1, 2026), reconciled against the SEC filings.
- Screener and rating data: in-house stock scanner (data as of July 10, 2026); Reddit mentions: ApeWisdom (as of July 17, 2026).
Transparency & disclaimer: This analysis is a journalistic contextualization of publicly available information and is not investment advice, not a financial analysis in the regulatory sense, and not a solicitation to buy or sell securities. Stock investments involve substantial risks up to and including total loss. All information without guarantee; the data cut-off is noted in the text for each figure. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this deep dive.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | – | 0.0 | 0.4 | 4.1 | 23.8 |
| Operating Income (EBIT) | -2.6 | -5.1 | -16.0 | -26.4 | -57.2 |
| Net Income | -2.6 | -4.9 | -16.3 | -32.3 | -175.1 |
| Net Margin | – | – | -3,761.0% | -780.3% | -734.2% |
| Earnings Per Share | -0.08 $ | -0.14 $ | -0.49 $ | -0.58 $ | -2.11 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
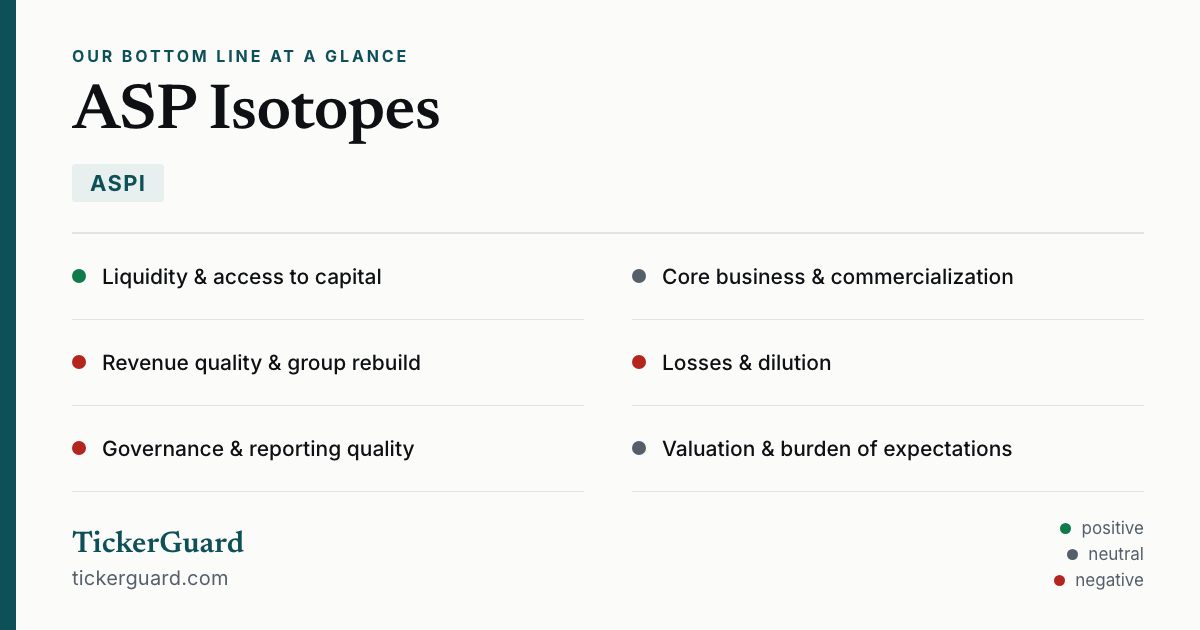
Our Bottom Line at a Glance
- Liquidity & access to capital neutral
- $219.6 million in cash plus $35.3 million in short-term investments (June 30, 2026), down from $290.5 million three months earlier. Per the 10-Q, funds last more than twelve months from the issuance of the financial statements (August 14, 2026) — but the $35.6 million drop in liquidity during the second quarter shows how fast the cash pile is shrinking.
- Core business & commercialization negative
- Both Pretoria plants have been producing since the first half of 2025 and offtake agreements for Si-28 and C-14 are signed — yet there was no isotope revenue through June 30, 2026, and first shipments have slipped to the second half of 2026 (compressors, missing feedstock, laser failure).
- Revenue quality & group rebuild negative
- 76 percent of 2025 revenue came from Hong Kong construction acquisition Skyline (deconsolidated March 29, 2026); Renergen was acquired in January 2026 and is to be spun out again via a merger with ENDRA. The continuing business is growing (Q2 2026: $5.1 million) but remains small against the cost base.
- Losses & dilution negative
- "Headline loss" of $30.1 million in the second quarter of 2026 after $11.2 million a year earlier; share count up from 48.9 million to 153.3 million (+213 percent since the end of 2023), including 23.2 million new shares from the exchange of QLE convertible notes in July 2026.
- Governance, debt & reporting quality negative
- An ongoing material weakness in internal controls; breached covenants on Renergen loans from the DFC and the IDC (formally "in default"), a bank loan with a November 30, 2026 waiver deadline and a cross-default clause reaching the parent; a class action in settlement proceedings and four derivative suits against board members (10-Q as of 06/30/2026; 8-K of 08/20/2026).
- Valuation & burden of expectations neutral
- Roughly $414 million of market value (close of $2.70 on October 1, 2026); net of June 30 liquidity, roughly $159 million for the operating package — at about 33 times continuing revenue. The helium start, the Renergen spin-out and the QLE listing could make value visible; none of it is proven yet.
A betting slip with five fields: the cash still lasts ($254.9 million on June 30, 2026), but none has paid out — not one dollar of isotope revenue, shipments postponed again, a share count tripled since the end of 2023. Not investment advice.
What Our Rating Means
Substance risk
We found at least one documented issue that threatens the company itself — regardless of how the stock is currently valued.
Whoever buys today pays a smaller hope premium than in July but is still betting that at least two of the five stories deliver before dilution and the cost base eat through the war chest — while carrying key contracts the customer can cancel at will, a certified control weakness, loans with breached covenants and a group in permanent rebuild. Whoever waits checks four pieces of evidence in the next quarterly report (10-Q): the first invoiced C-14/Si-28 shipments, first helium revenue, the Renergen lenders' waivers by November 30, 2026, and the trajectory of the share count. As long as that evidence is missing, the stock is a bundle of hopes. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- ASPI reached the research list in July 2026 via the Reddit hype scanner: just 2 mentions in 24 hours, but a jump from rank 785 to rank 233 of the most-discussed stocks (ApeWisdom, as of July 17, 2026). In our in-house stock scanner, the stock appeared in no ranking filter at the time (data as of July 10, 2026).
- Update of October 2, 2026: incorporates the quarterly report (10-Q) as of June 30, 2026, and all SEC filings through October 2, 2026, including ENDRA’s registration statement (S-4) for the Renergen merger. There was no earnings call; management commentary comes from the shareholder letter of August 4, 2026, and the transcript of the Capital Markets Day of September 8, 2026.
- Price and valuation figures are dated to the close of October 1, 2026 ($2.70; market value roughly $414 million on 153,309,380 shares per the 10-Q cover of August 14, 2026); analyses are evergreen, daily prices are not a buy argument. The Noble Africa/ENDRA merger was still subject to approvals and closing conditions as of this writing.
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of October 3, 2026. Stock Watch will tell you what's changed at ASPI since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for ASP Isotopes Inc. (ASPI), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
ASP Isotopes Inc. (Nasdaq: ASPI, headquartered in Dallas) is building a platform for enriching rare isotopes, with plants in Pretoria, South Africa (ASP and QE technology). Target markets are nuclear medicine (C-14, Yb-176), semiconductors and quantum computing (Si-28), and nuclear fuels (HALEU, Li-6) via its subsidiary Quantum Leap Energy. Running revenue so far comes mainly from the radiopharmacies in South Africa and the U.S. and from Renergen's LNG sales; first-half 2026 revenue was $9.3 million.
Per the quarterly report (10-Q) of August 14, 2026, revenue rose to $5.1 million (prior-year quarter: $1.2 million), of which $3.9 million from radiopharmacy, $0.7 million from LNG and $0.6 million from TerraPower. The net loss fell to $33.6 million (prior year: $75.1 million) because a large fair-value loss on convertible notes dropped away; the adjusted "headline loss," by contrast, rose from $11.2 million to $30.1 million. Liquidity fell from $290.5 million to $254.9 million.
The two enrichment plants in Pretoria have been producing since the first half of 2025, but per the 10-Q no isotope revenue had been generated through June 30, 2026. First commercial shipments of C-14, Si-28 and Yb-176 are now targeted for the second half of 2026 (2025 annual report: Si-28 in the second quarter, C-14 mid-2026). Management cites compressors from a former supplier that had to be upgraded, missing C-14 feedstock from the customer and a laser failure at the ytterbium plant.
Consolidated revenue rose from $4.1 million to $23.8 million in 2025 — of which $18.2 million (76 percent) came from the road and drainage construction business of Skyline Builders (Nasdaq: SKBL), a Hong Kong builder acquired in August 2025 and deconsolidated again effective March 29, 2026. Excluding Skyline, 2025 revenue was $5.7 million per the recast figures.
The share count grew from 48.9 million (December 31, 2023) to 153,309,380 (August 14, 2026), an increase of 213 percent. On July 16, 2026, alone, 23,160,682 new shares were created when holders of convertible notes issued by subsidiary Quantum Leap Energy exchanged roughly $109.2 million of principal for ASPI stock. Per the 10-Q, roughly $80.6 million of principal of these notes remains with third parties.
TerraPower — the reactor company co-founded by Bill Gates — has signed two supply agreements for HALEU (higher-enriched uranium) with ASP Isotopes and in May 2025 committed a loan of up to $22 million toward a uranium enrichment facility in South Africa (10 percent interest, maturing 2032, first drawdowns planned from the third quarter of 2026). Important per the 10-K 2025: both supply agreements are terminable by TerraPower at any time, for convenience.
ASP Isotopes acquired South African helium and LNG producer Renergen on January 6, 2026, for 14.27 million of its own shares worth roughly $92.9 million. Under the merger agreement of June 25, 2026, Renergen is to merge with ENDRA Life Sciences via the holding company "Noble Africa"; per the registration statement (S-4) of October 2, 2026, the combined company is to be named "4K Resources Inc." and trade on Nasdaq under the ticker LHE (NOBA had been named earlier). Per the shareholder letter of August 4, 2026, ASP Isotopes would then hold roughly 89 percent; the S-4 names roughly 89.4 percent for ASP Isotopes together with the other Noble investors and roughly 98.9 percent of the votes for ASP Isotopes. Closing is planned for the fourth quarter of 2026, requires approval by ENDRA stockholders and was still pending as of October 2, 2026.
Cheaper than in July, but not cheap: at the closing price of $2.70 (October 1, 2026), market value is roughly $414 million and price-to-sales on trailing four-quarter continuing revenue is around 33; a P/E ratio does not exist. Net of $254.9 million of liquidity (June 30, 2026), the market pays roughly $159 million for a bundle of still-unproven options — against which Renergen carries roughly $57 million of loans (June 30, 2026).
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.