Alpha Pro Tech Nearly Stopped Buying From Its Main Supplier – and Its Cash Grew by Half
In the third quarter of 2026, the maker of protective apparel and building wraps ordered $87,000 of goods from its Indian partner, down from $5.72 million. A little over half of the cash increase was earned; the rest came from emptied warehouses and tariff money. The real test comes when inventory has to be rebuilt at higher freight and resin costs.
 Thomas Mücke
Founder & Publisher
As of Today
As of: November 10, 2026
- Closing price
- 6.30 $ +12.60%
- Market Capitalisation
- 62.0 $M
- P/E
- 18.9
- Growth Score
- 4/10
- AAQS
- 2/10
Price change since November 10, 2026: +0.8%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 4.30 $ to 6.60 $ · Last price: 6.30 $ (As of: November 10, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
Imagine your bank balance jumps from $17,000 to $25,500 in nine months. You feel richer — until you do the math. Part of the money is there because you ate your way through the pantry and did not restock. Another part is a refund you may still have to share with your roommates. Only some of it is money you actually earned. That is exactly what the balance sheet of Alpha Pro Tech (NYSE American: APT) looks like as of September 30, 2026.
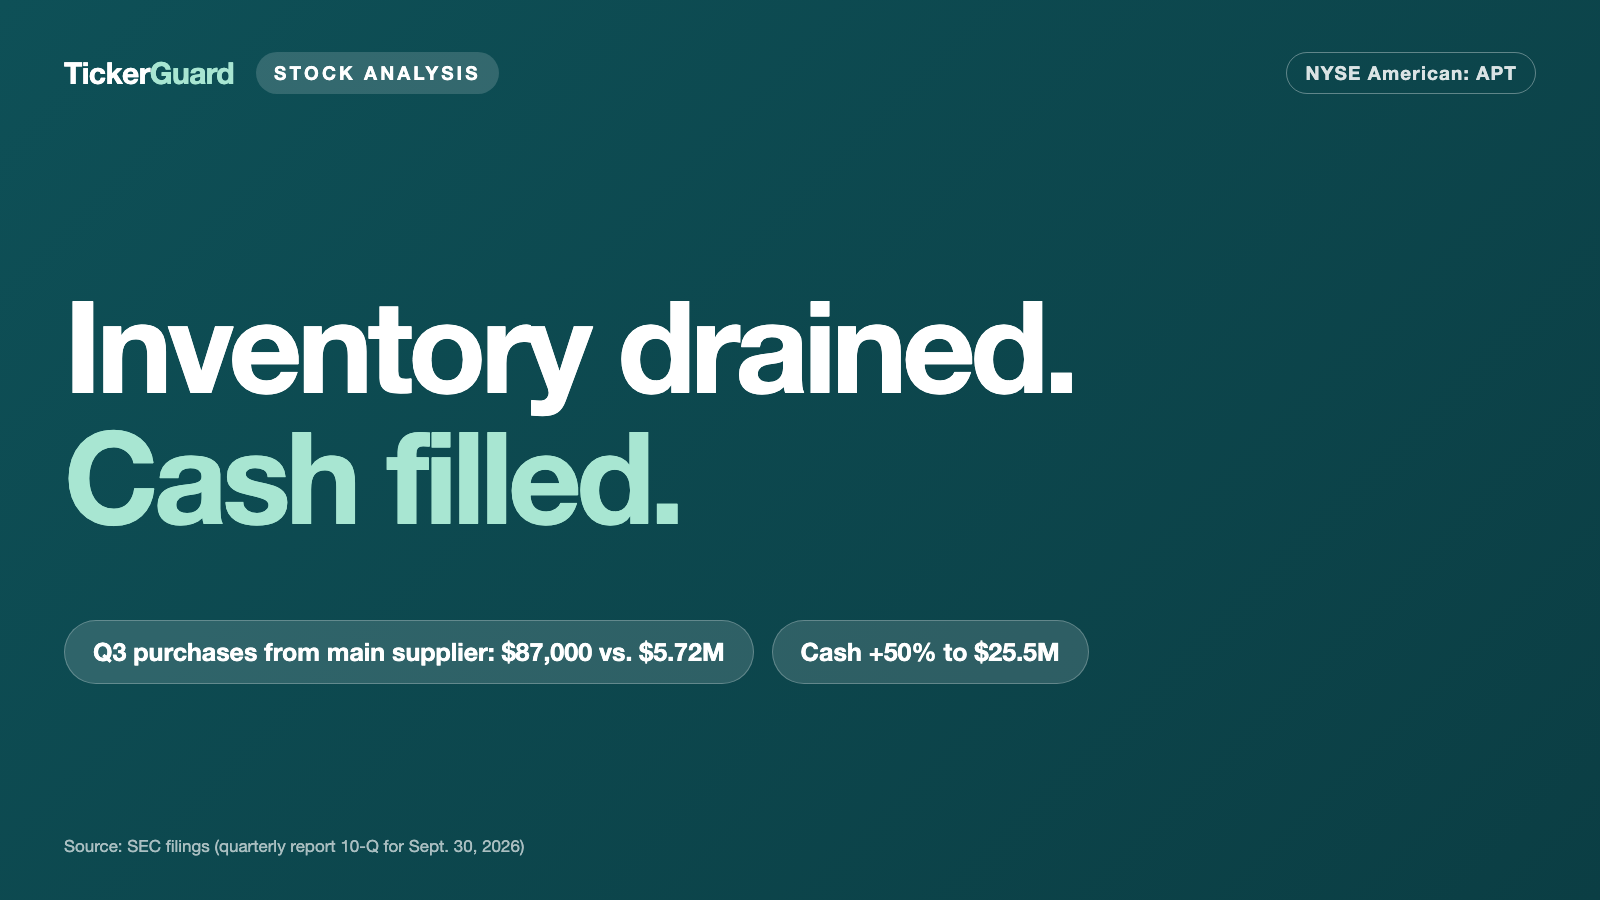
Cash rose by $8.56 million (up 50.4 percent) in nine months to $25.55 million, with zero bank debt. Net income contributed $4.45 million. Most of the rest came from emptied warehouses ($5.74 million) and from refunded tariffs that the company has largely booked as a liability. How drastically inventory was drawn down shows up in one number from the notes: from its most important supplier, the Indian joint venture Harmony, Alpha Pro Tech bought just $87,000 of goods in the third quarter — a year earlier it was $5.72 million. What that means for you: the big cash pile is real, but not all of it is earned, freely available money.
We call this the bank-balance illusion: when you see a large cash balance, you read it as proof of a good business — and stop asking where the money came from and whom it belongs to. For a company the market valued at about $64 million (closing price on November 10, 2026), that distinction matters a lot.
Let us make a deal: before the bank balance impresses you, we read together what Alpha Pro Tech itself filed with the U.S. securities regulator, the SEC — the quarterly report (10-Q) and the earnings release (8-K) of November 10, 2026, the quarterly reports before it and the annual report (10-K) for 2025. Lying to the SEC carries penalties, which is why these filings are among the most reliable sources there are. In the end, you decide.
What Alpha Pro Tech actually does — house wrap, roof underlayment and disposable protective apparel
Alpha Pro Tech is a Delaware corporation, incorporated in 1994 as the successor to a business organized in 1983. Headquarters are in Aurora, Ontario, in Canada; manufacturing takes place in Nogales, Arizona, and Valdosta, Georgia. As of March 2, 2026, it had 122 full-time employees. The annual report describes the business in one line:
“Alpha Pro Tech is in the business of protecting people, products and environments.”
— Alpha Pro Tech, annual report 10-K for 2025, Item 1 “Business”
In everyday terms, there are two workshops under one roof. The larger one, Building Supply, sells weatherization products: house wrap (the sheet behind the siding that keeps out wind and moisture), synthetic roof underlayment that sits under shingles or tiles, and other woven materials. In 2025 this segment generated $36.0 million in revenue. The competition is DuPont and Berry Global in house wrap, Owens Corning and GAF in roof underlayment. The smaller workshop, Disposable Protective Apparel, sells single-use garments — shoe covers, bouffant caps, gowns, coveralls — plus face masks and face shields for clean rooms, labs, hospitals and industry; that segment brought in $23.1 million in 2025. For a comparison within the industry, see our analysis of Lakeland Industries, a maker of industrial protective clothing.
One detail shapes everything that follows: a lot of the goods come from India. Alpha Pro Tech owns 41.66 percent of Harmony Plastics, a joint venture with the Indian manufacturer Maple Industries that produces roof underlayment, wraps and protective apparel in a semi-finished state. In 2025 Alpha Pro Tech bought $19.4 million of goods there — about a third of revenue. A company that imports that much lives and dies by U.S. tariffs.
That defines the central tension of this analysis, and it runs through every chapter: the business is doing better in 2026 and the balance sheet is debt-free — but almost half of the jump in cash comes from one-off effects of the tariff dispute that will not repeat and are partly not even settled yet.
Company history for investors
-
1994
Incorporated in Delaware
Alpha Pro Tech is formed as the successor to a business organized in 1983. For shareholders: a long history as a small specialist.
-
1999
Buyback program starts
Since then about 22.0 million shares have been repurchased and retired for $58.6 million. For shareholders: the main lever for earnings per share.
-
2005
Harmony joint venture in India
A 41.66% stake in Harmony Plastics. For shareholders: low-cost production, but a large supplier that Alpha Pro Tech does not control.
-
2020
Pandemic record
Revenue of $102.7 million, net income of $26.9 million. For shareholders: a one-off — afterward the business returned to its old level.
-
2026
Tariff refunds after Supreme Court ruling
About $3.5 million in IEEPA tariffs came back, mostly booked as a liability. For shareholders: more cash, ownership of the money still open.
-
2026
Auditor change to MNP
The audit committee dismissed Tanner LLP on September 14, according to the filing without disagreements. For shareholders: the 2026 annual audit is the new firm's first.
How the stock landed on our desk
Alpha Pro Tech landed on our desk through the quarterly report itself: on November 10, 2026, the company filed its 10-Q for the third quarter (July 1 to September 30, 2026) and the earnings release the same day. The headlines are strong: revenue of $16.60 million versus $14.79 million (up 12.3 percent), net income of $1.93 million versus $0.98 million (up 97.2 percent), earnings per share of $0.19 versus $0.09. The stock closed that day at $6.25, 12.6 percent above the prior close of $5.55; the 52-week range ran from $4.34 to $7.50 (source: fundamental data, as of November 10, 2026).
Turn those numbers into a ratio and you see an apparent bargain: a price-to-book ratio just below 1 — in plain terms, the market values the company at less than what it owns on paper after deducting all liabilities. On top of that, about 40 percent of the market value sits in the bank as cash. This is exactly where the bank-balance illusion kicks in. So remember from the start: at Alpha Pro Tech, the earnings jump is mostly real — the cash jump only in part.
One-offs first: what is left of the quarter without the tariff money
On February 20, 2026, the U.S. Supreme Court ruled that the President lacked authority to impose tariffs under the emergency law IEEPA (International Emergency Economic Powers Act). That mattered for Alpha Pro Tech, because goods from India had carried a 50 percent tariff. According to the quarterly report, the company recovered about $3.5 million of previously paid tariffs, including interest, in the first nine months of 2026. According to the quarterly report, the U.S. government has appealed the court decisions on the refunds and the litigation continues. Since the IEEPA tariffs were rescinded at the end of February 2026, a new 10 percent tariff applies under a different law (Section 122 of the Trade Act of 1974).
Alpha Pro Tech discloses the effect of the refund itself — admirably open for a company this size. In the third quarter it contributed $70,000 through lower cost of goods sold and $97,000 in interest, together $167,000 before tax and $124,000 after tax. The comparison (millions of U.S. dollars, quarterly report of November 10, 2026):
| Item | Q3 2026 | Q3 2025 | 9M 2026 | 9M 2025 |
|---|---|---|---|---|
| Net income as reported | 1.925 | 0.976 | 4.453 | 2.833 |
| of which tariff refund (after tax) | 0.124 | – | 0.343 | – |
| Net income excluding tariff refund | 1.801 | 0.976 | 4.110 | 2.833 |
| Diluted EPS ($) | 0.19 | 0.09 | 0.43 | 0.27 |
| Diluted EPS excluding refund ($) | 0.18 | 0.09 | 0.40 | 0.27 |
| Gross margin excluding refund | 41.4% | 39.7% | 38.2% | 38.4% |
The table tells two stories. The first is good: even without the tariff money, quarterly net income rose 84.5 percent, and income from operations rose 73.2 percent to $1.90 million. Protective apparel did the heavy lifting: segment revenue climbed 30.2 percent to $7.2 million. For disposable protective garments, which make up 90 percent of the segment (up 30.6 percent), the report credits stronger sales through distribution partners and, to “a considerable portion,” higher selling prices. Building products grew just 1.7 percent to $9.4 million. The second story is more sober: over nine months, the gross margin excluding the refund was 38.2 percent, slightly below the prior year (38.4 percent). The strong third quarter made up for a weak first half — no more than that.
Two further items help earnings without coming from the company's own sales: its share of Harmony's profit rose to $254,000 in the quarter (prior year $27,000), and interest income to $306,000 ($169,000) — $97,000 of which is the refund interest mentioned above. The Harmony item is remarkable: it rose even though Alpha Pro Tech bought almost nothing there in the same quarter (more on that below); in the other direction, Alpha Pro Tech sold $477,000 of goods to Harmony (prior year $213,000). Where Harmony's higher profit comes from, the report does not explain. Remember: the tariff money in earnings is small. The tariff money in the cash balance is large. The latter is what we turn to below.
The numbers over the years — an honest look
First, what genuinely impresses. Alpha Pro Tech has been profitable every single year since 2010, without one loss year according to its annual reports. It has no bank debt, and it consistently returns its surplus to shareholders — not as a dividend (by its own account it has never paid one) but through share buybacks. Since 1999 it has repurchased and retired 22.0 million of its own shares for about $58.6 million. In July 2011 there were still 22.4 million shares outstanding; at the end of October 2026 there are 10.3 million. Put simply: a shareholder since 2011 now owns more than twice as large a slice of the pie without buying a single extra share.
Now the other side. The business itself has barely grown over those years, and without the pandemic that would be even clearer:
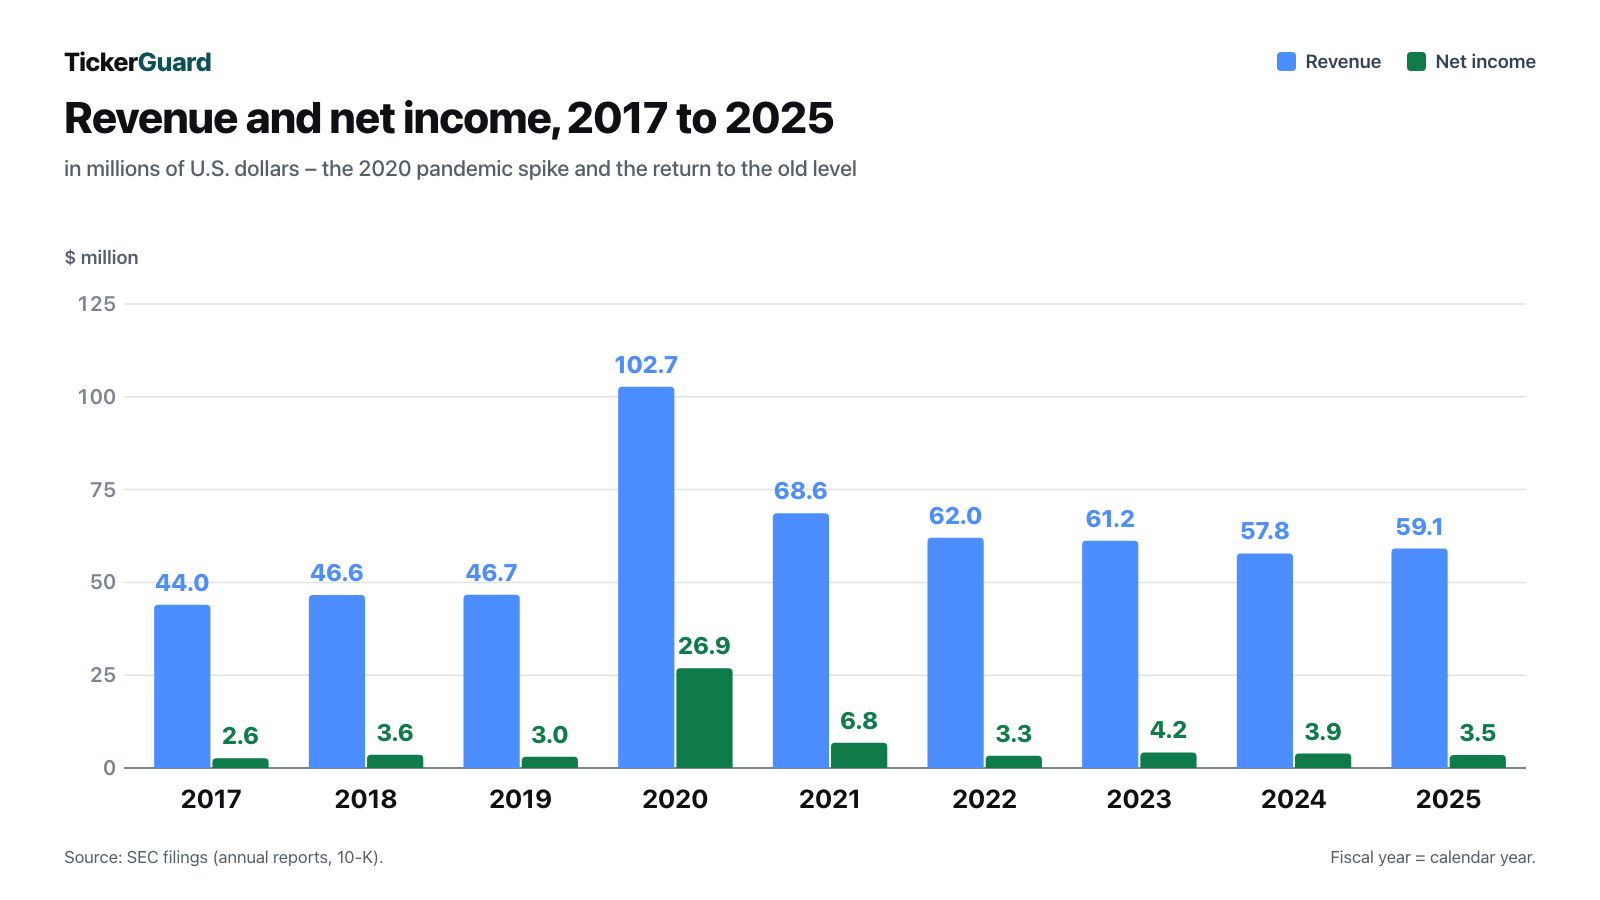
In 2020 Alpha Pro Tech suddenly sold masks and protective apparel in pandemic volumes: $102.7 million in revenue and $26.9 million in net income, or $1.92 per share. After that the business normalized year by year. In 2025 revenue was $59.1 million (up 2.3 percent) and net income $3.53 million, after $3.93 million in 2024; tariffs pushed the gross margin down from 39.6 percent to 38.1 percent. That earnings per share still rose from $0.23 (2019) to $0.33 (2025, diluted) is mostly due to the smaller share count — net income itself went from $3.0 million to $3.5 million.
Net income is the company's bottom line, not its core business: it includes the share of Harmony's profit and interest on the cash. Income from operations — from the company's own sales — was $3.84 million in 2025, an operating margin of 6.5 percent. Remember: Alpha Pro Tech is a solid, small, fairly slow company — buybacks are the real engine behind its earnings per share.
What the filings say — the uncomfortable truths
Uncomfortable truth No. 1: almost half of the cash increase is not profit
Earnings are an accounting figure; cash in the bank is a fact. At Alpha Pro Tech in 2026 the usual gap ran the other way: far more money came in than was earned. Operating cash flow — the cash the business actually brings in — was $9.34 million in the first nine months, more than twice the $4.45 million of net income. Of the $8.56 million increase in cash, net income therefore covers a little over half; the remaining $4.11 million came, net, from the inventory drawdown and tariff money after higher prepayments and receivables. The bridge shows where it came from:
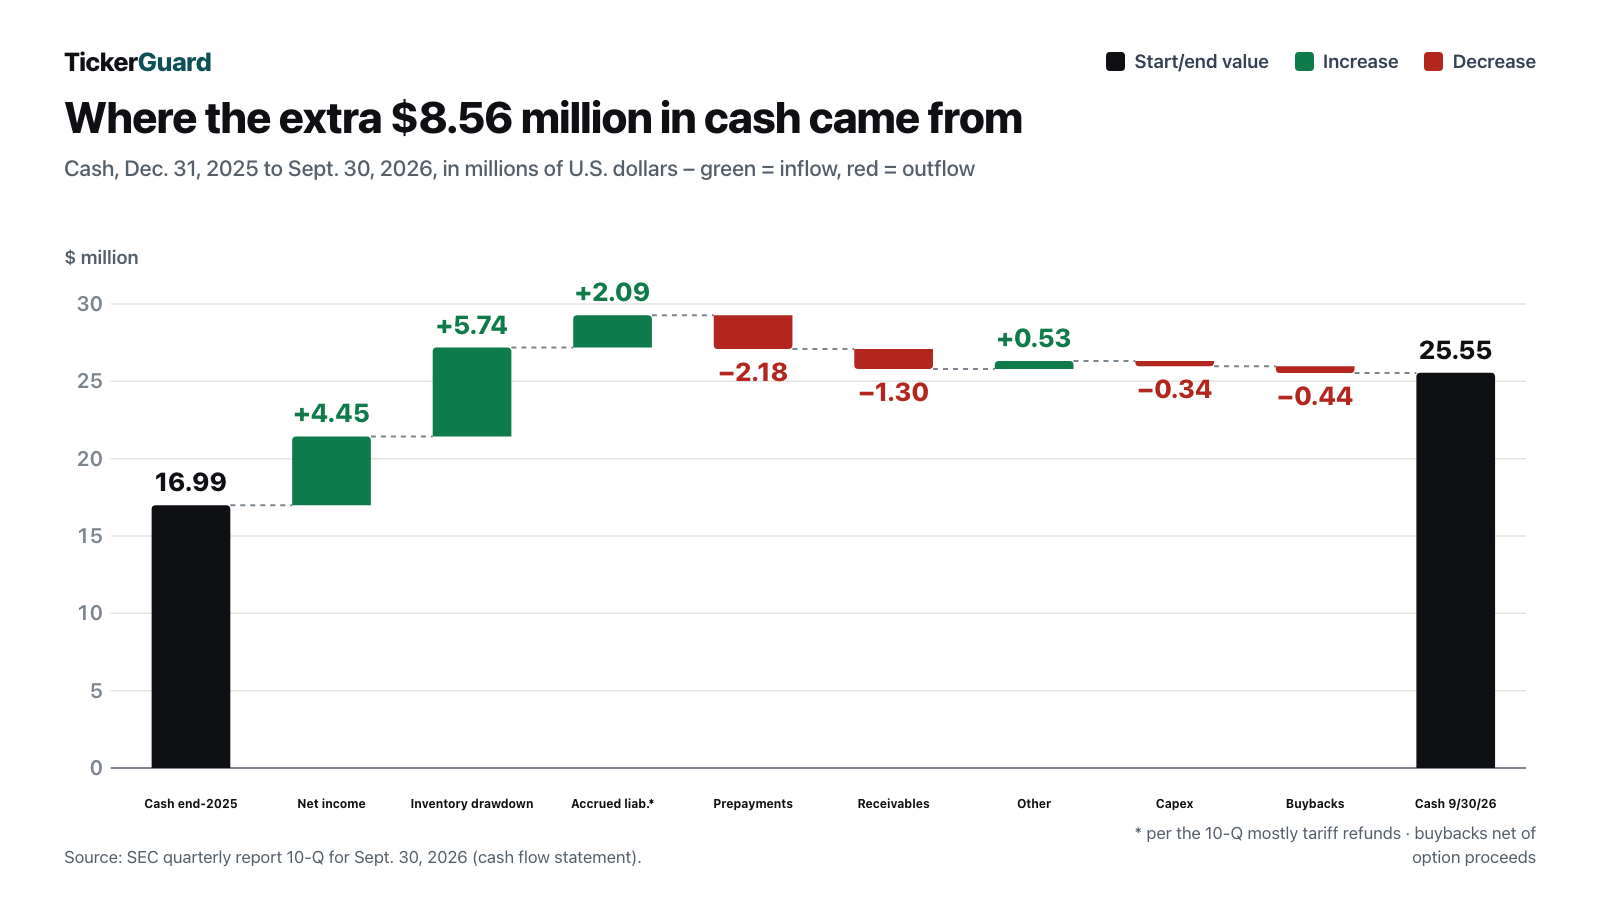
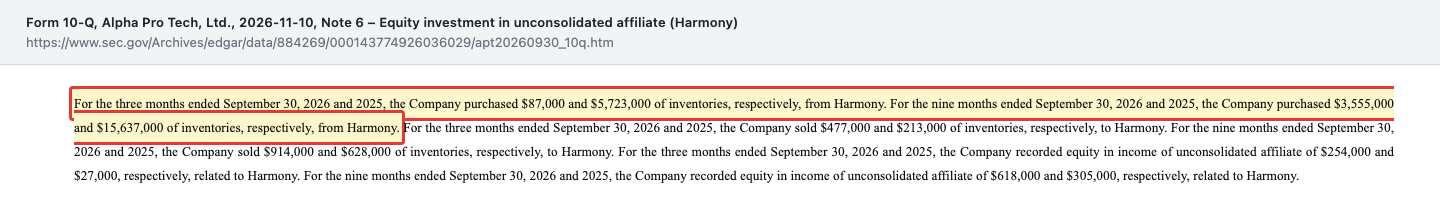
The largest single item is the inventory drawdown: inventories fell from $23.60 million to $17.85 million, down by a quarter. The report gives the reason in one sentence: “We purchased less inventory due to the high tariff rate.” How drastic that was shows up in purchases from the Indian partner:
“For the three months ended September 30, 2026 and 2025, the Company purchased $87,000 and $5,723,000 of inventories, respectively, from Harmony. For the nine months ended September 30, 2026 and 2025, the Company purchased $3,555,000 and $15,637,000 of inventories, respectively, from Harmony.”
— Alpha Pro Tech, quarterly report 10-Q for September 30, 2026, Note 6 (Harmony)
In everyday terms: the company ate its way through the pantry. That brings in cash once, not twice — anyone who wants to keep selling has to restock eventually. Prepayments for inventory have already risen by $2.18 million. And because customers paid more slowly — after 64 days on average versus 40 days at year-end 2025, according to the report because of higher sales — growth tied up another $1.30 million in receivables. Remember: the inventory drawdown was a reaction to tariffs, not a new business model.
Uncomfortable truth No. 2: part of the cash may belong to someone else
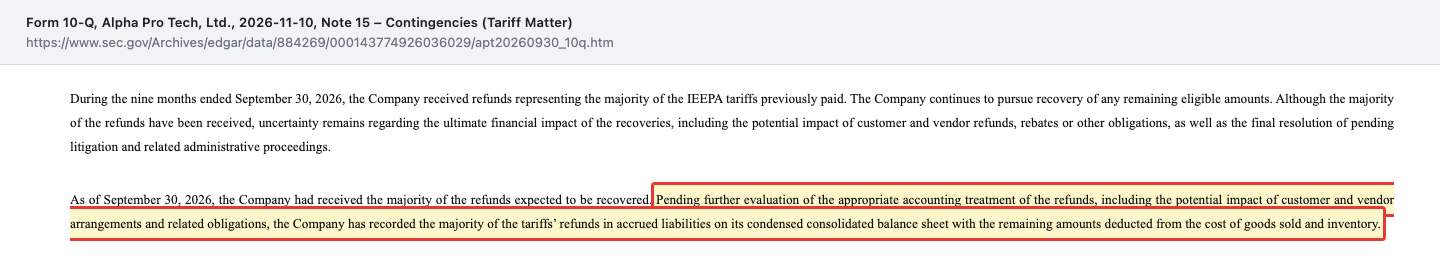
The second large inflow is trickier. Of the roughly $3.5 million in tariff refunds, Alpha Pro Tech took only $461,000 before tax into earnings. It parked the rest because it is still evaluating whether it may keep the money:
“Pending further evaluation of the appropriate accounting treatment of the refunds, including the potential impact of customer and vendor arrangements and related obligations, the Company has recorded the majority of the tariffs’ refunds in accrued liabilities on its condensed consolidated balance sheet with the remaining amounts deducted from the cost of goods sold and inventory.”
— Alpha Pro Tech, quarterly report 10-Q for September 30, 2026, Note 15 “Contingencies” (Tariff Matter)
The report does not give an exact amount. The notes offer a clue: the line “commissions and bonuses payable and general accrued liabilities” rose from $0.82 million at year-end 2025 to $3.12 million at September 30, 2026. The report explains the increase in payables and accrued liabilities overall as “primarily due to advanced deposits of IEEPA tariffs.” That is cautious, clean accounting. But it also means part of the $25.55 million may have a different owner, and the government's appeal hangs over all of it. For you there are two outcomes, both one-time: if Alpha Pro Tech may keep the money, a one-time gain follows later; if it has to pass it on, cash goes down. Remember: to be safe, count the cash without the parked tariff money — roughly $23 million rather than $25.5 million (our own rough estimate based on the $2.30 million rise in general accrued liabilities; the line also contains commissions and bonuses, and the exact tariff portion is not disclosed). For how another company handles possible tariff refunds, see our analysis of The Eastern Company, which has not booked a material amount for refunds so far.
Uncomfortable truth No. 3: few customers, one supplier — and all of them are big
Alpha Pro Tech is small, and small companies often depend on a handful of partners. The annual report for 2025 says so openly:
“For example, sales to one customer represented 24%, and 20% of our total revenue, and sales to another customer represented 15% and 15% of our total revenue for the years ended December 31, 2025 and 2024, respectively.”
— Alpha Pro Tech, annual report 10-K for 2025, Item 1A “Risk Factors”
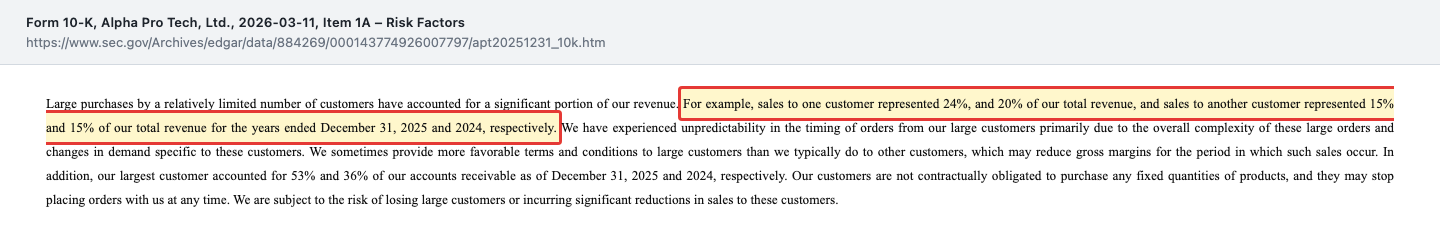
So two customers make up 39 percent of revenue, and the largest accounted for as much as 53 percent of receivables at December 31, 2025 (36 percent a year earlier). According to the report there are no fixed purchase commitments; customers “may stop placing orders with us at any time.” On the purchasing side the same pattern appears with Harmony, in which Alpha Pro Tech holds only a minority stake: $19.4 million of purchases in 2025, about a third of revenue. Add new cost drivers in 2026 that management names itself: higher prices for petroleum-based resin since the start of the U.S.-Iran conflict, and ocean freight rates that have “increased substantially” and are expected to put additional pressure on gross margin in future periods. The company's U.S. patents expired in 2024. Remember: Alpha Pro Tech has a strong balance sheet but little bargaining power.
Uncomfortable truth No. 4: a new auditor, and the share count is rising again
Two smaller findings belong on the table as well. On September 14, 2026, the audit committee dismissed the company's auditor — three months after shareholders had ratified the same firm for fiscal 2026 at the annual meeting on June 10, 2026:
“On September 14, 2026, the Audit Committee (the “Audit Committee”) of the Board of Directors of Alpha Pro Tech, Ltd. (the “Company”) dismissed Tanner LLP (“Tanner”) as the Company’s independent registered public accounting firm, effective immediately.”
— Alpha Pro Tech, current report 8-K of September 16, 2026, Item 4.01
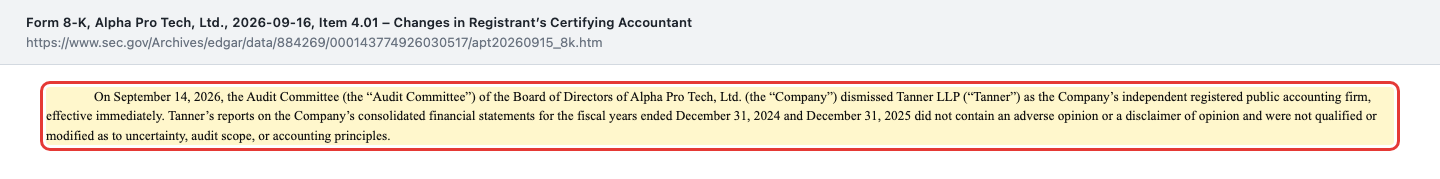
Important for context: according to the filing there were no disagreements and no reportable events, the audit opinions for 2024 and 2025 were unqualified, and Tanner confirmed this in its own letter to the SEC. The new auditor is MNP LLP. The filing gives no reason for the change. That is not a red flag, but it is a date to watch: the first annual audit by the new firm is the one for 2026 — exactly the one in which the parked tariff money is likely to be decided.
The second finding concerns the buyback machine. In 2026 it ran on low power: in nine months Alpha Pro Tech repurchased only 97,982 shares for $483,000 (first nine months of 2025: 532,313 shares for $2.63 million; full year 2025: 685,313 shares for $3.35 million). At the same time it granted 256,865 restricted stock units to employees and directors (same period of 2025: 32,330), and 234,460 vested. The result: the share count rose from 10,131,565 (December 31, 2025) to 10,263,126 (October 29, 2026), up 1.3 percent. Your slice of the pie got slightly smaller in 2026, not larger. Only $914,000 remained under the repurchase authorization as of September 30, 2026. Remember: the lever that drove earnings per share for years barely worked in 2026.
Valuation: what the November 10, 2026 close demands
At the closing price of $6.25 on November 10, 2026, and 10,263,126 shares (cover of the quarterly report), Alpha Pro Tech is worth about $64.1 million. Subtract the cash and the business itself costs about $38.6 million (lease obligations not included); if you exclude the parked part of the tariff refunds from free cash, it is closer to $41 million. That yields these orders of magnitude, each based on the four quarters through September 30, 2026:
- Price-to-earnings ratio (GAAP) of about 13 (about $0.49 diluted EPS). GAAP are the U.S. accounting rules; the P/E tells you how many years of earnings you pay for the stock.
- P/E excluding the tariff refund of about 14 (about $0.46 per share) — the more honest yardstick as long as it is unclear whether the tariff money recurs.
- Enterprise value to operating income of about 7.5 to 8 (operating income excluding the refund about $5.2 million): the market pays little for the operating business.
- Price-to-book ratio just below 1 (equity of $66.0 million, about $6.49 per share as of September 30, 2026) and price-to-sales ratio of about 1.0 ($63.7 million of revenue over four quarters).
- No dividend; shareholder returns run entirely through buybacks, which were small in 2026.
Put simply: the market values Alpha Pro Tech like a company that does not grow — and for 2021 through 2025 that is accurate. The stock is cheap if the third quarter of 2026 was not a one-off: annualizing the quarterly EPS excluding the refund of $0.18 would put the P/E at about 9. It gets expensive if freight and resin costs eat up the higher prices again. There is hardly a “view from the pros”: for a company this size, fundamental data show no usable analyst estimates. A different kind of clue: as of April 13, 2026, directors and officers together held 16.2 percent of the shares, director Donna Millar alone 12.6 percent. CEO Lloyd Hoffman, with the company since 1991, receives a contractual bonus of 5 percent of pre-tax profit, capped at $1 million — an incentive tied to profit, not to revenue.
Opportunities and risks at a glance
What speaks for Alpha Pro Tech:
- No bank debt, $25.55 million in cash and current assets covering current liabilities almost nine times, about 8.7 times (September 30, 2026).
- Genuine earnings growth in the third quarter of 2026: net income excluding the tariff refund up 84.5 percent, protective apparel revenue up 30.2 percent.
- Profitable every year since 2010; about 22 million shares repurchased since 1999.
- Market value just below shareholders' equity; enterprise value at about 7.5 to 8 times operating income.
- Insiders together hold 16.2 percent of the shares (April 13, 2026); the CEO bonus is tied to pre-tax profit.
What speaks against it:
- Almost half of the 2026 cash jump comes from the inventory drawdown ($5.74 million) and tariff refunds; the drawdown does not repeat, and most of the refunds are parked as a liability.
- Over nine months the gross margin excluding the refund was 38.2 percent, slightly below the prior year; management reports rising resin and freight costs.
- Two customers account for 39 percent of revenue (2025), and a minority-owned joint venture in India supplies about a third of the goods.
- Dependence on U.S. tariff policy and the housing cycle: management describes a soft building market for the rest of 2026 and expects only a modest increase in housing starts in 2027.
- Auditor change in September 2026 with no reason given; the share count rose 1.3 percent in 2026 despite buybacks.
A human conclusion
Back to the bank-balance illusion from the start. Its core is not that the $25.55 million is wrong — it is in the bank, and Alpha Pro Tech has no debt. Its core is that a high balance makes you forget where it came from: from a pantry that has been eaten through and must be restocked, and from tariff money the company itself does not yet know how much of it may keep. Set both aside and an honest finding remains: Alpha Pro Tech had a genuinely good third quarter in 2026, carried by protective apparel and higher prices. Over nine months it earns clearly more than a year earlier excluding the tariff money, but with a barely better gross margin, and it depends on a few customers, one supplier and U.S. tariff policy. So the honest question for you is not “Isn't the stock cheap with all that cash?” but: Do you believe Alpha Pro Tech can hold its higher prices once it has to restock at higher freight and resin costs? If yes, you have a thesis that the 2026 annual report will confirm or refute. If no, you have bought a bank balance. What you make of it is your decision. And that is how it should be.
Sources
All original documents used in this analysis — so you can read them yourself:
- Alpha Pro Tech — SEC quarterly report 10-Q for September 30, 2026 (filed November 10, 2026)
- Alpha Pro Tech — earnings release for the third quarter of 2026 (8-K Item 2.02, Exhibit 99.1, filed November 10, 2026)
- Alpha Pro Tech — SEC quarterly reports 10-Q for June 30, 2026 (August 7, 2026), March 31, 2026 (May 7, 2026) and September 30, 2025 (November 6, 2025)
- Alpha Pro Tech — SEC annual reports 10-K for 2025 (filed March 11, 2026) and 2024 (filed March 12, 2025)
- Alpha Pro Tech — current report 8-K of September 16, 2026 (auditor change, Item 4.01) with the letter from Tanner LLP (Exhibit 16.1)
- Alpha Pro Tech — 8-K of June 15, 2026 (annual meeting voting results) and proxy statement DEF 14A (April 30, 2026)
- Annual figures 2017 to 2025 from the structured financial data (XBRL) in the annual reports filed with the SEC; full filing history: EDGAR overview Alpha Pro Tech (sec.gov)
- Fundamental data (prices, 52-week range, market cap cross-check, analyst coverage; as of November 10, 2026), reconciled with the SEC filings.
Transparency & disclaimer: this analysis is journalistic commentary on publicly available information. It is not investment advice, not a regulated investment research product and not a solicitation to buy or sell securities. Equity investments carry substantial risk up to and including total loss. All information is provided without warranty; the as-of date for each figure is stated in the text. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this analysis.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 68.6 | 62.0 | 61.2 | 57.8 | 59.1 |
| Operating Income (EBIT) | 7.9 | 4.7 | 4.1 | 3.4 | 3.8 |
| Net Income | 6.8 | 3.3 | 4.2 | 3.9 | 3.5 |
| Net Margin | 9.8% | 5.3% | 6.8% | 6.8% | 6.0% |
| Earnings Per Share | 0.50 $ | 0.26 $ | 0.35 $ | 0.35 $ | 0.33 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
Our Bottom Line at a Glance
- Balance sheet positive
- No bank debt, cash of $25.55 million, equity of $66.0 million, current assets cover current liabilities almost nine times (09/30/2026). Part of the cash is tied to parked tariff refunds.
- Operating business positive
- Q3 2026: revenue up 12.3% to $16.60 million, net income excluding the tariff refund up 84.5% to $1.80 million; protective apparel up 30.2%, partly on higher prices. Building products up only 1.7%.
- Quality of earnings and cash flow negative
- Net income covers a little over half of the $8.56 million rise in cash (9M 2026); the rest came, net, from an inventory drawdown ($5.74 million) and tariff money that is largely booked as a liability. Adjusted 9M gross margin 38.2% after 38.4%.
- Dependencies negative
- Two customers 39% of 2025 revenue, the largest 53% of receivables (12/31/2025); about a third of goods in 2025 came from the minority-owned joint venture Harmony in India; U.S. tariff policy drives the margin.
- Shareholder returns & governance neutral
- About 22 million shares repurchased since 1999, but only 97,982 in 2026; share count up 1.3% since year-end 2025. Auditor change on 09/14/2026 without disagreements, no reason given.
Alpha Pro Tech is the bank-balance illusion in its purest form: cash grew by half in 2026 to $25.55 million, almost half of it through emptied warehouses and refunded tariffs, the bulk of which sits on the books as a liability. The third quarter was genuinely strong even without the tariff money (net income up 84.5 percent), yet over nine months the adjusted gross margin stayed flat. Debt-free, solid, slow, dependent on a few partners. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
Yellow, because a material operating question is open: whether the higher third-quarter 2026 margin holds once the drawn-down inventory has to be rebuilt at rising freight and resin costs is unproven; on top come heavy customer and supplier concentration and dependence on U.S. tariff policy. Red would need a substantive risk, and there is none: no bank debt, $25.55 million in cash, profitable every year since 2010. Green would need proof that the business grows on its own. At the November 10, 2026, price, the market values the company just below its equity. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- The occasion for this analysis is the quarterly report (10-Q) and earnings release (8-K) of November 10, 2026. Price reference: closing price of $6.25 on 11/10/2026 (prior close $5.55; 52-week range $4.34–$7.50 per fundamental data).
- Data as of: the most recent periodic report is the 10-Q for 09/30/2026; no further filings through 11/11/2026. No earnings call transcripts were available to us for Alpha Pro Tech; management statements come from earnings releases and filings.
- Adjusted figures (“excluding tariff refund”) per the company's reconciliation in the 10-Q; four-quarter figures (EPS of about $0.49 and $0.46) are our own calculation from the 2025 annual report and the quarterly reports.
- Not to be confused with: Alpha Pro Tech (APT) has nothing to do with Alpha Tau Medical, Alpha and Omega Semiconductor or Alphabet.
Stock Watch
This analysis is as of November 11, 2026. Stock Watch will tell you what's changed at APT since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Alpha Pro Tech Ltd (APT), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Alpha Pro Tech (NYSE American: APT) makes two product groups: weatherization products such as house wrap and synthetic roof underlayment ($36.0 million of revenue in 2025) and disposable protective apparel, face masks and face shields for clean rooms, labs and hospitals ($23.1 million). It is headquartered in Aurora, Canada, manufactures in Arizona and Georgia, and owns 41.66 percent of Harmony Plastics in India.
Cash rose from $16.99 million at year-end 2025 to $25.55 million on September 30, 2026. Net income contributed $4.45 million, the inventory drawdown $5.74 million, and higher payables and accrued liabilities, mainly from refunded tariffs, $2.09 million. Prepayments for inventory and higher receivables absorbed $3.48 million.
Not much. In the third quarter of 2026 it added $124,000 after tax, $343,000 over the first nine months. Excluding it, quarterly net income was $1.80 million instead of $1.93 million (up 84.5 percent year over year) and EPS $0.18 instead of $0.19. The company booked most of the roughly $3.5 million refund as a liability.
Alpha Pro Tech has no bank debt. As of September 30, 2026, $25.55 million in cash compared with total liabilities of $13.73 million, of which $7.36 million were lease liabilities. Shareholders' equity was $66.0 million, and current assets covered current liabilities almost nine times. Part of the cash, however, is tied to parked tariff refunds.
At the closing price of $6.25 on November 10, 2026, the price-to-earnings ratio on the last four quarters was about 13, or about 14 excluding the tariff refund. The market value was about $64.1 million, just below shareholders' equity of $66.0 million (as of September 30, 2026).
No. According to its 2025 annual report (10-K), Alpha Pro Tech has never declared or paid a dividend, and its quarterly report says it does not currently expect to. Instead it buys back shares: about 22.0 million since 1999 for $58.6 million. In 2026 the program was small (97,982 shares in nine months), and the share count actually rose slightly because of employee stock awards.
The current report of September 16, 2026, gives no reason. The audit committee dismissed Tanner LLP on September 14, 2026, and engaged MNP LLP for fiscal 2026. According to the filing there were no disagreements, the audit opinions for 2024 and 2025 were unqualified, and Tanner agreed with that account in writing.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.