Tesla Stock: $28 Billion in Revenue, a 2.6 Percent Operating Margin — and $30 Billion in New Credit Lines
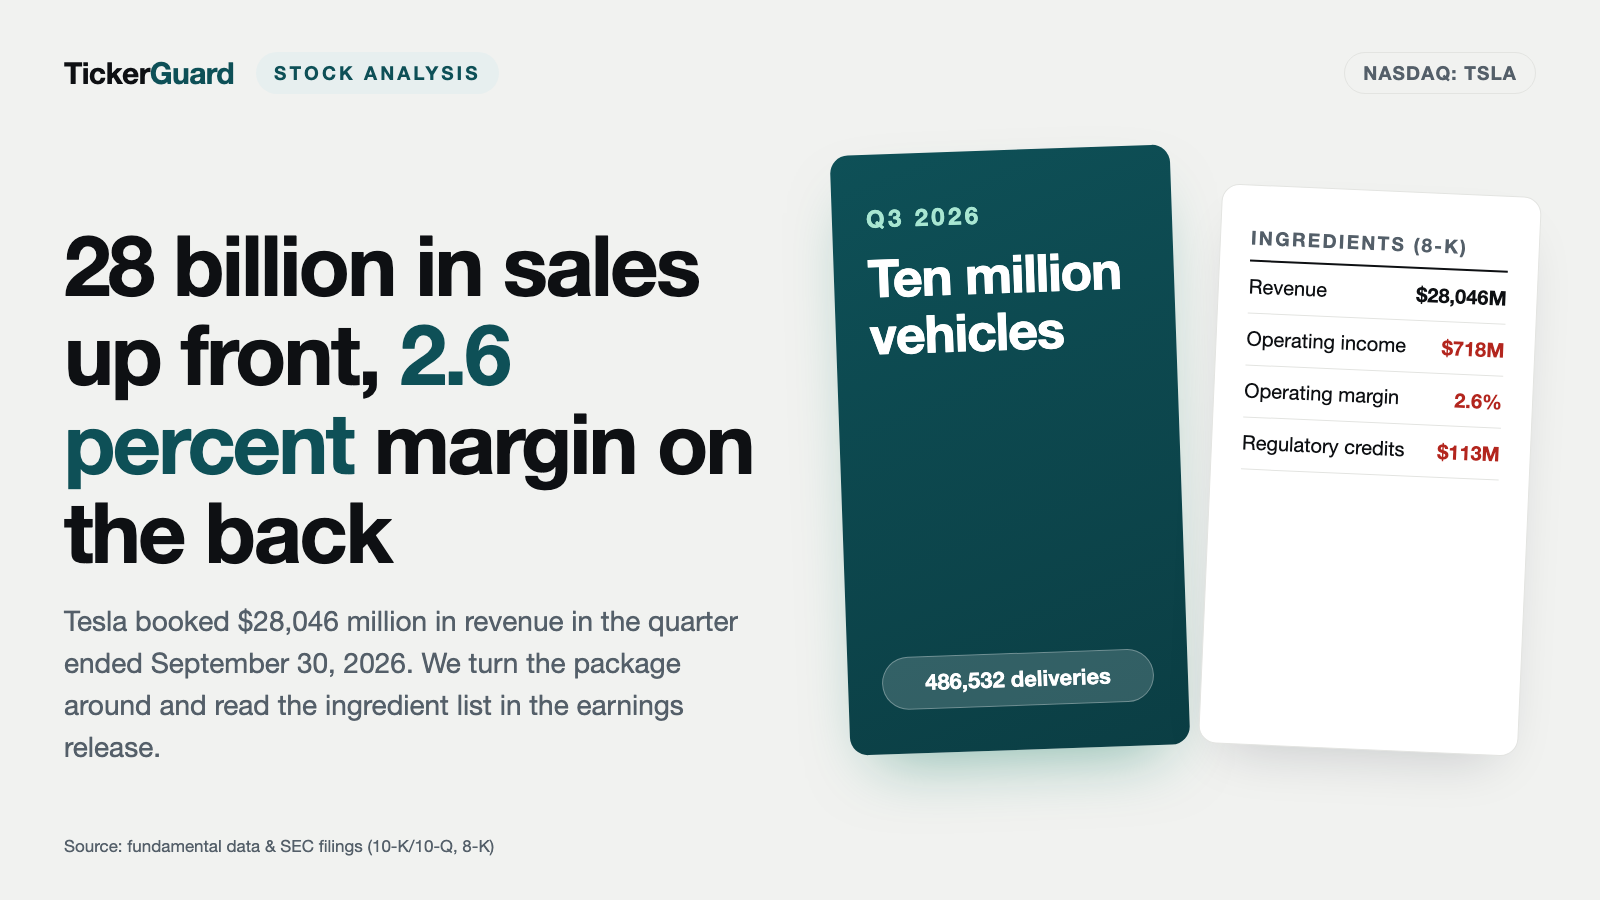
Tesla booked $28,046 million in revenue in the quarter ended September 30, 2026, practically the same as a year earlier. Operating income came to $718 million — 56 percent less. Revenue from emissions credits shrank 73 percent, stock-based compensation exceeded total operating income, and shortly before quarter-end the company lined up $30 billion in credit commitments. We hold the package up to the light a second time.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 30, 2026
- Closing price
- 399.80 $ -0.90%
- Market Capitalisation
- 1,593.8 $B
- P/E
- 346.7
- Growth Score
- 5/10
- AAQS
- 5/10
Price change since August 4, 2026: +24.1%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 298.30 $ to 489.90 $ · Last price: 399.80 $ (As of: October 30, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
The trap is called the front of the package
Let us make a deal. Before we talk about Tesla, let me confess a mental trap both of us fall into at the supermarket every week. The front of the package says, in large letters, whatever sounds good: "made with real fruit." The back, small and grey, carries the ingredient list — and there the fruit shows up seventh, at 2 percent. Both are true. The front just tells a different story than the back.
In the summer of 2026, Tesla's front read: 480,126 vehicles delivered in the quarter ended June 30, 2026, more than in any second quarter before, on $28,236 million of revenue, up 26 percent. All of that is accurate and all of it sits in the quarterly report.
The ingredient list is a few pages further in. It reads: $398 million of operating income, 57 percent less than a year earlier. On every $100 of revenue, $1.41 of operating profit remained.
Hold on to that tension, because it runs through every chapter: Tesla books more than $100 billion a year in revenue and earns less and less from the running business — and the reported quarterly profit in the second quarter of 2026 came from outside the car business. This analysis first appeared on July 29, 2026 with second-quarter figures. The chapter directly below carries it forward to the third quarter; every other chapter states the date of its figures.
Company history for investors
-
2017
Tesla Motors becomes Tesla, Inc.
Until January 27, 2017 the company was named "Tesla Motors Inc". For shareholders this means older filings sit at the SEC under the old name.
-
2024
Move from Delaware to Texas
Texas corporate law has applied since June 13, 2024. Several legacy shareholder cases continue before Delaware courts.
-
2025
Award covering 423.7 million shares
Approved on November 6, 2025. If the milestones are met, the share count grows markedly; as of June 30, 2026 up to $120 billion of expense sat in the footnote.
-
2026
$2.0 billion SpaceX stake
Since March 2026 SpaceX value swings run through Tesla's income statement: plus $1,005 million in the second quarter, minus $142 million in the third.
-
2026
$30 billion of credit commitments
Signed on September 29, 2026, nothing drawn. For shareholders a sign that capital spending may in future be funded partly with debt.
What changed with the third quarter of 2026
As of this update: October 22, 2026. It rests on Tesla's earnings release for the quarter ended September 30, 2026 (Form 8-K dated October 21, 2026, Exhibit 99.1, "Q3 2026 Update"). The quarterly report on Form 10-Q had not been filed at press time. Figures only the 10-Q carries — warranty reserve, sales to SpaceX, bitcoin count, the 2026 capital-expenditure guidance — therefore remain in the text as of June 30, 2026. No verifiable transcript of the October 21, 2026 earnings call was available at press time; we quote nothing from it.
- Revenue practically flat: $28,046 million against $28,095 million in the prior-year quarter. Tesla delivered 486,532 vehicles, 2 percent fewer than in the prior-year quarter (497,099), and produced 464,391, up 4 percent. Cumulative deliveries reached 10.2 million — the ten millionth vehicle came off the line during the quarter.
- Operating income of $718 million: down 56 percent from the prior-year quarter ($1,624 million), but almost double the second quarter of 2026 ($398 million). The operating margin was 2.6 percent, after 5.8 percent a year earlier.
- Regulatory credits of $113 million, down 73 percent from the prior-year quarter ($417 million).
- Net income of $787 million after $1,373 million, down 43 percent. This time the special items nearly cancelled out: bitcoin produced a $288 million pre-tax remeasurement gain, the SpaceX stake a $142 million remeasurement loss.
- Free cash flow positive again: plus $1,531 million after minus $1,092 million in the prior quarter, on capital expenditures of $4,732 million. Cash and short-term investments rose to $45,447 million.
- New credit facilities of $30 billion since September 29, 2026; the previous $5 billion revolver was terminated. Nothing has been drawn.
- Share count: 3,952,730,153 as of October 13, 2026, per the proxy statement for the annual meeting on December 3, 2026 (DEF 14A dated October 19, 2026). Three items are on the ballot: the election of three directors, a non-binding vote on 2025 executive pay and the ratification of the auditor.
Where the recovery against the prior quarter came from. Total gross margin rose to 19.6 percent. Three lines carry that: the energy business recovered from the prior quarter's cell issue to a gross margin of 33.1 percent (second quarter: 20.4 percent), even though its revenue fell 16 percent year over year (8 percent against the prior quarter) to $2,881 million — Tesla cites, among other things, tariff-related customer refunds. Automotive gross margin excluding credits rose from 16.3 percent in the prior quarter (15.4 a year earlier) to 18.1 percent. And services and other reached a record gross profit of $734 million.
Below that line the progress gets eaten up again. Research and development expense rose 69 percent year over year to $2,761 million, selling, general and administrative 29 percent to $2,015 million. One figure in Tesla's own reconciliation table deserves a second look: stock-based compensation for the quarter came to $1,165 million — more than total operating income of $718 million. It costs no cash, but it dilutes every other shareholder.
The positive cash flow needs a footnote. Of operating cash flow of $6,263 million, $2,590 million came from changes in working capital — chiefly higher accounts payable, accrued and other liabilities (plus $3,991 million) and customer deposits recorded as deferred revenue (plus $1,255 million). Without that effect, operating cash flow would have been $3,673 million and would not have covered capital expenditures of $4,732 million. The cross-check against the prior-year quarter: working capital contributed $2,083 million there as well. So part of this is seasonal, not a one-off. It still holds true: the quarter was not paid for by the running business alone.
Capital expenditures from January through September 2026 came to $13,014 million. In its 10-Q for the quarter ended June 30, 2026 Tesla had guided to more than $25 billion for the full year — which would require roughly $12 billion in the fourth quarter alone. The third-quarter earnings release gives no new figure. Whether the guidance stands will only show in the quarterly report.
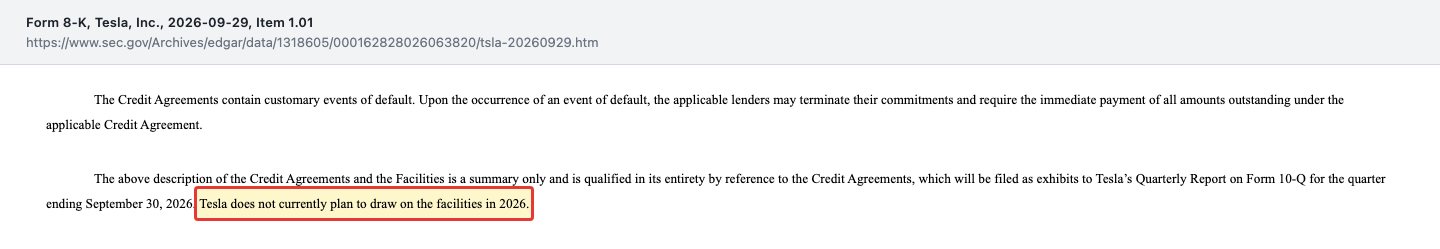
The safety net got bigger. One day before quarter-end Tesla signed three credit agreements with combined commitments of $30 billion, including a $20 billion delayed-draw term loan whose undrawn portion shrinks to $10 billion after twelve months and terminates after 18 months. The company says it does not need the money for now:
"$20.0 billion senior unsecured three-year delayed draw term loan facility … Tesla does not currently plan to draw on the facilities in 2026."
— Tesla, Inc., Form 8-K dated September 29, 2026, Item 1.01
What changed in tone. The second-quarter 2026 earnings release used "AI" twelve times. In the third-quarter release the abbreviation no longer appears; in its place stands "SI", for "Super Intelligence", twelve times. The profit outlook is word for word the same apart from that one term: Tesla expects hardware-related profits over time to be accompanied by an acceleration of "SI, software and fleet-based profits." New are two completion notices — volume production of the Tesla Semi has begun in Nevada and Optimus production in Fremont — and one unchanged bottleneck:
"While battery availability continued to be the limiting factor in increasing auto volumes in the quarter, we have made additional progress in securing future supply, as we work toward our goal of maximum utilization of our factories."
— Tesla, Inc., "Q3 2026 Update" earnings release, Form 8-K dated October 21, 2026, Exhibit 99.1
For the tension in this analysis that means: the third quarter was better than the second, but not better than a year earlier. The front of the package advertises super intelligence and robots; the ingredient list shows a 2.6 percent operating margin.
What Tesla actually does
Tesla builds and sells cars. That is the short answer, and it carries three quarters of the business. Of the $28,046 million of revenue in the quarter ended September 30, 2026, $20,094 million came from automotive sales and another $353 million from automotive leasing. The company runs two reportable segments: automotive and services with $25,165 million of revenue in the quarter, and energy generation and storage with $2,881 million.
The second pillar is bigger than many assume, and it grows differently. Energy covers the large grid batteries (Megapack), the home batteries (Powerwall) and solar products. In the quarter ended September 30, 2026 Tesla deployed 13.7 gigawatt-hours of storage, up 10 percent year over year; across all of 2025 the figure was 46.7 gigawatt-hours. In the same quarter the Megapack factory in Texas started production, with planned capacity of 50 gigawatt-hours.
Then there is a third block that has no revenue line of its own yet drives every headline: services and other, $4,605 million in the quarter, up 33 percent. That covers used-vehicle sales, repair work, collision service and paid Supercharging — not autonomous driving. Where Robotaxi and the FSD driver-assistance system leave their revenue, we will see shortly.
Two points that are easy to get wrong. First: Tesla's fiscal year is the calendar year and ends on December 31. "Fiscal 2025" really does mean January 1 through December 31, 2025 — unlike many technology companies, nothing needs converting.
Second: Tesla has been a Texas corporation since June 13, 2024, previously a Delaware one, with its headquarters in Austin. That sounds like a formality, but it is the reason several legacy cases still run before Delaware courts. And the company was named "Tesla Motors Inc" until January 27, 2017 — anyone hunting older filings will find them under that name.
How the stock landed on our desk
This time it was not a screener hit. Our in-house stock scanners filter on metrics — cheap valuation, high Piotroski score, momentum — and precisely for that reason the best-known heavyweights fall through systematically: they are rarely cheap. When we counted on July 28, 2026 how many of the 100 largest U.S. stocks by market capitalization already had a deep dive here, 88 did not. Tesla was the fifth largest of those, at rank 9 with a market capitalization of about $1,214 billion (as of July 29, 2026).
That is an honest statement about our own method: a scanner that hunts bargains does not find blue chips. So we work the list from the top down. Tesla belongs to the same investment wave as two companies we have already examined: Amazon is building data centers at the same pace for the same reason, and the chips this money buys come in large part from Nvidia. Valuing any of them means valuing one shared question: when does compute turn into earnings?
The numbers over the years — honestly credited
Start with what genuinely impresses. Tesla delivered 480,126 vehicles in the quarter ended June 30, 2026 — 25 percent more than a year earlier and more than in any second quarter in company history. The quarter ended September 30, 2026 followed with 486,532. Since inception the total stands at 10.2 million vehicles. Trailing twelve-month revenue passed $100 billion for the first time as of June 30, 2026, and stayed above it as of September 30, 2026 at $103,570 million. No carmaker manages that by accident.
The balance sheet is remarkable too. As of September 30, 2026 Tesla carried $45,447 million of cash and short-term investments against $9,523 million of debt and finance leases — $9,265 million of it non-recourse to the parent, meaning secured by individual vehicles, receivables and energy assets. The equity ratio was 56.7 percent. On top of that come $30 billion of credit commitments signed on September 29, 2026, none of it drawn.
Now the time series. And here the tension shows up for the first time:
| Fiscal year (calendar year) | Revenue | Operating income | Operating margin | Net income |
|---|---|---|---|---|
| 2023 | $96,773M | $8,891M | 9.2% | $14,997M |
| 2024 | $97,690M | $7,076M | 7.2% | $7,091M |
| 2025 | $94,827M | $4,355M | 4.6% | $3,794M |
Read the third column again. Revenue sat between $95 billion and $98 billion for three straight years — operating income halved over the same span. One note on the second series: net income in 2023, at $14,997 million, exceeded operating income of $8,891 million. The difference came from the tax line, which was a benefit that year. Anyone treating 2023 as a normal year is measuring against a one-off.
And the quarters? They show the same thing in slow motion:
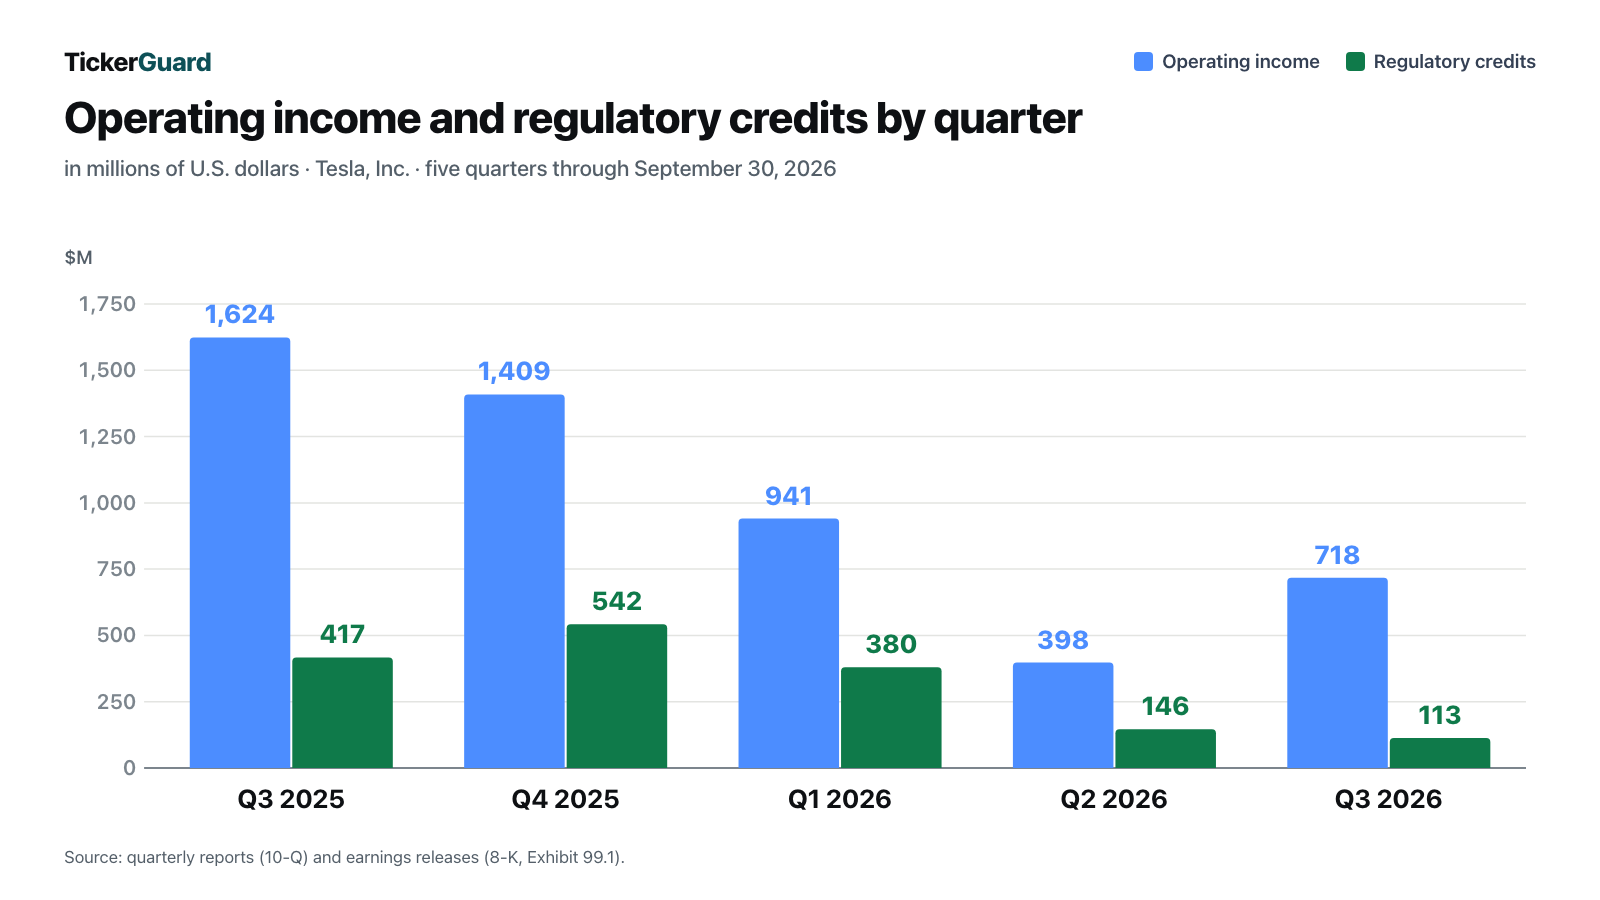
Two series, one pattern. The green bars are no footnote: in the quarter ended June 30, 2026 the $146 million from selling emissions credits equaled roughly 37 percent of total operating income of $398 million. In the quarter ended September 30, 2026 it was $113 million out of $718 million, roughly 16 percent — a year earlier $417 million out of $1,624 million, roughly 26 percent. The share is falling because the credits shrink faster than the profit. What exactly those credits are and why they are disappearing comes next.
So you can check every figure yourself, here are all five quarters in full, in millions of U.S. dollars:
| Quarter | Revenue | Operating income | Regulatory credits | Capital expenditures | Free cash flow |
|---|---|---|---|---|---|
| Q3 2025 (ended 2025-09-30) | 28,095 | 1,624 | 417 | 2,248 | +3,990 |
| Q4 2025 (ended 2025-12-31) | 24,901 | 1,409 | 542 | 2,393 | +1,420 |
| Q1 2026 (ended 2026-03-31) | 22,387 | 941 | 380 | 2,493 | +1,444 |
| Q2 2026 (ended 2026-06-30) | 28,236 | 398 | 146 | 5,789 | −1,092 |
| Q3 2026 (ended 2026-09-30) | 28,046 | 718 | 113 | 4,732 | +1,531 |
Two columns deserve a second look. Fourth-quarter 2025 revenue of $24,901 million came in below the third quarter's $28,095 million — Tesla's volumes swing sharply with the season, which is why quarterly comparisons should always run against the same quarter a year earlier. And the last column crosses into negative territory exactly once: in the second quarter of 2026. In the third quarter it returned to positive — with the footnote set out in the update chapter above.
What the filings say — the uncomfortable truths
Uncomfortable truth no. 1: a quarter more revenue, more than half the operating income gone
In the quarter ended June 30, 2026 Tesla's revenue rose 26 percent to $28,236 million. In the same quarter operating income fell 57 percent to $398 million. The operating margin dropped from 4.1 to 1.4 percent. Tesla states this plainly in its own earnings release, without softening.
Where did the money go? Into three blocks, all of them in the quarterly report:
- Research and development: $2,371 million, up 49 percent. Tesla attributes it to AI programs and an expanded product roadmap.
- Selling, general and administrative: $1,982 million, up 45 percent. Of that, $283 million is stock-based compensation, mostly for the 2025 chief executive award.
- The energy business: segment gross margin fell from 30.3 to 20.4 percent and gross profit from $846 million to $640 million — despite 13 percent more revenue. Tesla names higher warranty-related charges caused by a vendor cell issue.
One figure cuts the other way, and honesty requires naming it: automotive gross margin excluding regulatory credits rose in the same quarter from 15.0 to 16.3 percent. Tesla is not building cars worse; it is building them cheaper. The earnings collapse happens below that line — in spending on things that generate no revenue yet.
The third quarter of 2026 confirms the pattern with different signs: revenue stood still, automotive gross margin excluding credits rose to 18.1 percent, and operating income still came in at less than half the prior-year quarter — because research and development expense rose 69 percent to $2,761 million.
Uncomfortable truth no. 2: the earnings component with no cost of goods is disappearing
Carmakers must meet emissions requirements in many markets. Those who exceed them — and a pure electric manufacturer necessarily does — may sell the surplus credits to other manufacturers. Tesla incurs no cost of revenue for them. The proceeds flow almost entirely into gross profit; Tesla itself strips them out in its earnings release as a clean 2.2 percentage points of automotive margin in the prior-year quarter and 0.6 points in the second quarter of 2026.
That line is shrinking. In the quarter ended June 30, 2026, $146 million remained, down from $439 million a year earlier; in the quarter ended September 30, 2026 it was $113 million. Tesla names the reason itself:
"Automotive regulatory credits revenue decreased $293 million, or 67%, in the three months ended June 30, 2026 as compared to the three months ended June 30, 2025. … Recent governmental and regulatory actions have restricted certain regulatory credit programs tied to our products."
— Tesla, Inc., Form 10-Q for the quarter ended June 30, 2026, Item 2 (MD&A), filed with the U.S. securities regulator, the SEC, on July 23, 2026

How much is still coming sits in Note 1 of the 10-Q for the quarter ended June 30, 2026: as of that date the unsatisfied transaction price on credit contracts with an original term of more than one year was $287 million, $220 million of which Tesla expected to recognize over the following twelve months. For scale: in fiscal 2025 the figure was $1,993 million — 46 percent of total operating income of $4,355 million.
In everyday terms: a contractor whose annual profit is half government subsidy is not badly run. He is simply dependent on a decision he does not make.
Uncomfortable truth no. 3: three quarters of pre-tax income came from an equity stake
In March 2026 Tesla invested $2.00 billion in SpaceX common stock. The position arose from a former preferred-share investment in xAI and represents an ownership interest below one percent. Because the chief executive runs both companies, Tesla presumes significant influence over the investee and carries the position at fair value — so swings run straight through the income statement.
In the quarter ended June 30, 2026 the swing went up:
"The investment is classified as Level 2 within the fair value hierarchy based on observable market inputs used to estimate the $238 million discount for lack of marketability due to regulatory restrictions expiring in September 2026. For the three months ended June 30, 2026, we recorded a $1.00 billion net gain on our SpaceX equity investment."
— Tesla, Inc., Form 10-Q for the quarter ended June 30, 2026, Note 2 (Fair Value of Financial Instruments)

Now the arithmetic. Pre-tax income for the quarter was $1,329 million. The unrealized remeasurement gain of $1,005 million equals 76 percent of it. A second line sits below: after a California tax statute took effect, Tesla released a valuation allowance on deferred tax assets, which added $274 million to earnings and pushed the effective tax rate from 23 to 15 percent.
Tesla lays both out in its own reconciliation: from $1,114 million of quarterly profit it subtracts $763 million of after-tax SpaceX gain and $274 million of tax items. What would be left without those two items — with every other cost, including stock-based compensation, still in place — is $77 million. On $28,236 million of revenue.
In the third quarter of 2026 the same line ran the other way: the SpaceX stake produced an unrealized remeasurement loss of $142 million before tax. That is exactly the point: this line is not earning power but a price ticker, rewritten into the income statement every quarter.
None of this is improper or hidden. It sits in Tesla's own table. The summer headline "$1.1 billion quarterly profit" simply told the front of the package.
Uncomfortable truth no. 4: the compensation award sits in a footnote at up to $120 billion
On September 3, 2025 the board granted the chief executive a compensation award covering 423,743,904 performance-based shares; shareholders approved it on November 6, 2025. It consists of twelve tranches of roughly 35.3 million shares each. Every tranche requires two things: a market-capitalization milestone — from $2.0 trillion for the first to $8.5 trillion for the twelfth — and an increasing number of operational milestones.
Those milestones are specific and disclosed: 20 million vehicles delivered, 10 million active FSD subscriptions, 1 million bots delivered, 1 million Robotaxis in commercial operation, plus adjusted EBITDA tiers from $50 billion to $400 billion. For scale: adjusted EBITDA for the twelve months ended September 30, 2026 was $14,995 million, and active FSD subscriptions as counted under the award stood at 1.74 million.
In accounting terms, expense arises only once an operational milestone is deemed probable. As of June 30, 2026 exactly one was — the 20 million vehicles. The rest sits in a footnote:
"As of June 30, 2026, we had unrecognized stock-based compensation expense of $105.82 billion to $120.37 billion for the operational milestones that were considered not probable of achievement."
— Tesla, Inc., Form 10-Q for the quarter ended June 30, 2026, Note 9 (Equity Incentive Plans)

Two things follow. First: should those milestones become probable, an expense many times the annual profit enters the income statement — stock-based compensation moves no cash, but it dilutes everyone else's stake. Dilution, in everyday terms: your slice of the cake gets smaller while the cake stays the same size.
Second, and this is the part many miss: the share count outstanding and the one in earnings per share no longer match. As of October 13, 2026 the proxy statement lists 3,952,730,153 shares outstanding; the third-quarter 2026 income statement used 3,240 million (3,541 million diluted). The gap of roughly 713 million shares consists chiefly of restricted stock from the chief executive's compensation awards: the shares from exercising about 304.0 million options under the 2018 award in the second quarter of 2026, and the 423,743,904 shares of the 2025 award, which stay out of earnings per share until they are earned. The 2018 award shares carry a service condition through January 19, 2028 and a five-year holding period thereafter.
Uncomfortable truth no. 5: in the second quarter of 2026, more cash went out than came in for the first time in two years
Tesla was for years the rare growth company that paid for its own growth. In the quarter ended June 30, 2026 that streak broke. Capital expenditures jumped to $5,789 million, up 142 percent year over year. Operating cash flow rose sharply too, to $4,697 million — but no longer enough. Free cash flow came in at minus $1,092 million, the first negative quarter since the first quarter of 2024.
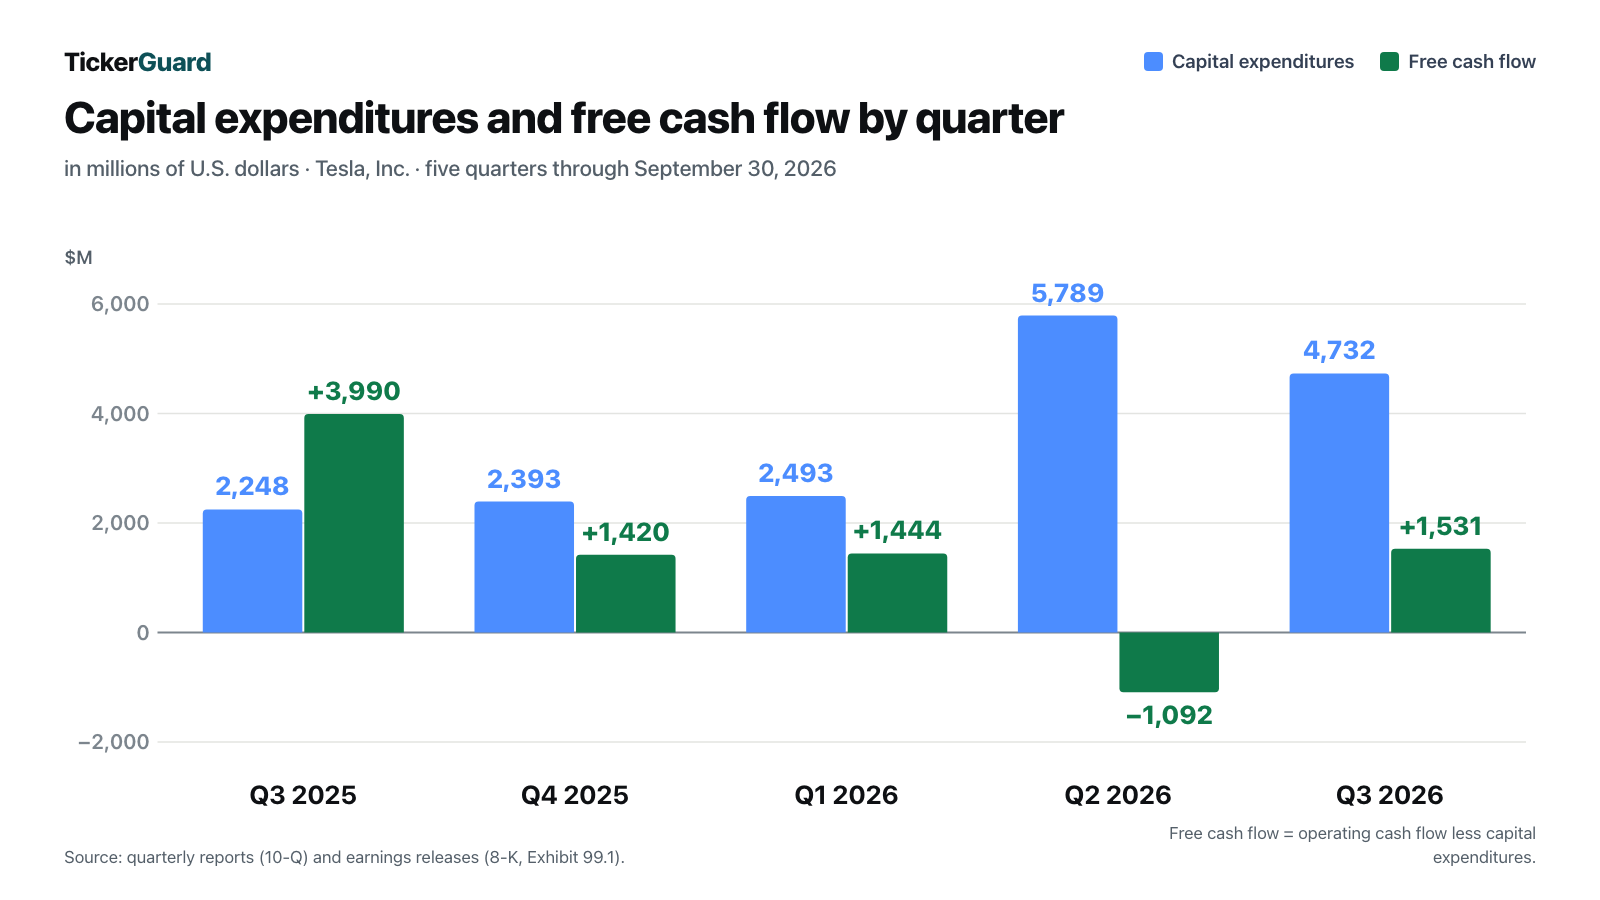
In the third quarter of 2026 free cash flow returned to positive, at $1,531 million — carried by $2,590 million from higher payables, customer deposits and other working capital, as worked out in the update chapter above. The full-year plan sat in the 10-Q for the quarter ended June 30, 2026:
"We currently expect our capital expenditures to be in excess of $25 billion in 2026, driven by our AI initiatives, including investments in compute infrastructure and data centers, the expansion and ramp of our manufacturing and R&D production lines and facilities, and growth in our fleet of company-operated AI-enabled assets and our retail, service and charging footprint."
— Tesla, Inc., Form 10-Q for the quarter ended June 30, 2026, Item 2 (MD&A)

Do the arithmetic: Tesla invested $8.53 billion in 2025 and $11.34 billion in 2024. For 2026 the guidance is more than $25 billion — roughly triple the prior year; the first nine months came to $13.01 billion. The balance sheet shows it: the "AI infrastructure" line within property, plant and equipment rose from $6,816 million at December 31, 2025 to $10,823 million at June 30, 2026, up 59 percent in six months. Total property, plant and equipment reached $50,591 million by September 30, 2026.
It is affordable. $45,447 million of liquidity, $9,523 million of debt and $30 billion of undrawn credit commitments at the end of the third quarter — Tesla can carry this. In its 10-Q for the quarter ended June 30, 2026 the company did write, though, that periods of heightened capital expenditure "will necessitate additional funding beyond our operating cash flow." The new credit facilities are the preparation for that.
What you will not find in the filings
This may be the most important observation in this analysis. Tesla is discussed in the press as an AI, robotics and Robotaxi company. In the filings there is no separate revenue line for any of it. There are exactly two segments: automotive and services, and energy generation and storage. The third-quarter 2026 earnings release changed nothing about that.
Here is what is documented. As of June 30, 2026 Tesla counted 1.48 million active FSD subscriptions; as of September 30, 2026 it was 1.74 million, counted as defined in the compensation award, including upfront purchases. Deferred revenue for connectivity, FSD features and software updates stood at $4.05 billion as of June 30, 2026, of which Tesla expected to recognize $962 million over the following twelve months. Since September 3, 2026 Cybercabs have been giving Robotaxi rides in Austin; by quarter-end the service had logged nearly two million unsupervised miles. In Europe, FSD (Supervised) is now approved in nine countries.
This is not a small business — $962 million is more than the entire operating income of the third quarter of 2026. It is simply a business the filings do not yet allow you to value. Anyone buying Tesla as an AI company is buying an expectation, not a segment line.
Valuation: what you are paying for this company
At the closing price of October 21, 2026 — the day of the earnings release, before its publication after the close — Tesla's market capitalization stood at roughly $1,528 billion (3,952,730,153 shares at $386.47). Set against the twelve months ended September 30, 2026, our own calculation produces the following order of magnitude:
- Trailing price/earnings: about 475. As a rule of thumb, a broad U.S. index has long sat in a range of roughly 15 to 25. The forward multiple for the coming fiscal year is about 159 according to fundamental data.
- Price/sales: about 14.8. For a carmaker that is a level normally seen in software; traditional automakers often trade below 1.
- Price/book: about 17.1 on stockholders' equity of $89,289 million.
- Enterprise value to adjusted EBITDA: about 100.
These figures need a warning in both directions. A price/earnings ratio is a fraction — and Tesla's denominator is very small. Net income for the twelve months ended September 30, 2026 was $3,218 million, against $14,997 million in 2023. A multiple of 475 therefore says less about the price than about collapsed earnings. Conversely: part of that already small profit came, as shown, from equity-stake and bitcoin remeasurements.
Here a rule applies that we use on every cyclical: never extrapolate earnings from the peak — and not from the trough either. Tesla describes the automotive industry as cyclical in its own quarterly report and names interest rates, tariffs and government incentives as drivers. 2023 was an earnings peak with a tax one-off; 2026 so far is a trough with a capital-expenditure spike. Neither end works as a yardstick.
The professional view on Tesla is unusually split. Forty-four estimates produced an average price target of about $398 as of October 22, 2026, spread across 15 "strong buy," 4 "buy," 21 "hold," 2 "sell" and 2 "strong sell" ratings. The average here means all price targets added up and divided by their number — a few very high or very low targets pull it noticeably. Almost half the votes say "hold." Disagreement is not a forecast — but it is a hint that two entirely different companies are being valued: a carmaker with a 2.6 percent operating margin, and a robotics company that does not yet exist in the filings.
Opportunities and risks at a glance
Opportunities
- High volumes. 486,532 vehicles delivered in the quarter ended September 30, 2026; 10.2 million since inception. Trailing twelve-month revenue topped $100 billion for the second quarter in a row.
- A strong balance sheet. $45,447 million of liquidity against $9,523 million of debt, a 56.7 percent equity ratio, $30 billion of undrawn credit commitments (as of September 30, 2026).
- Cars are getting cheaper to build. Automotive gross margin excluding regulatory credits rose from 15.4 to 18.1 percent in the quarter ended September 30, 2026.
- Energy storage is growing. 13.7 gigawatt-hours in the quarter, up 10 percent; segment gross margin 33.1 percent. Tesla explicitly names power demand from AI data centers as a driver.
- Recurring software revenue is forming. 1.74 million active FSD subscriptions as of September 30, 2026; $4.05 billion of deferred revenue on the balance sheet as of June 30, 2026.
Risks
- The running business barely earns. $718 million of operating income on $28,046 million of revenue is 2.6 percent; the annual figure fell from $8,891 million (2023) to $4,355 million (2025).
- Quality of earnings. Equity-stake and bitcoin remeasurements swing through the income statement — plus $1,005 million from SpaceX in the second quarter of 2026, minus $142 million in the third. Stock-based compensation exceeded operating income in the third quarter.
- Regulatory credits are disappearing. Down 73 percent in the quarter ended September 30, 2026. In 2025 they equaled 46 percent of operating income.
- Capital-expenditure spike. More than $25 billion guided for 2026, $13,014 million in the first nine months. Third-quarter free cash flow leaned on payables and customer deposits; $30 billion of credit commitments stand ready.
- Compensation and dilution. 423,743,904 performance-based shares with unrecognized expense of $105.82 billion to $120.37 billion (as of June 30, 2026); roughly 713 million shares are already outstanding without counting toward earnings per share.
- Legal risk around driver assistance. In a product-liability trial a jury awarded $129 million of compensatory damages on August 1, 2025 (33 percent attributed to Tesla) plus $200 million of punitive damages; Tesla filed its opening appellate brief on July 2, 2026 and recorded an accrual it describes as immaterial. Class actions over statements about Autopilot, FSD and Robotaxi are also pending.
- Batteries, tariffs and incentive policy. Per the earnings release, battery availability still limited volumes in the third quarter of 2026; tariffs weighed on the energy business, and Tesla names the removal of electric-vehicle tax credits as a demand risk.
A human conclusion
Back to the package. In the summer, the front of Tesla's read: a record quarter — and that was not marketing, it was the truth. More vehicles delivered than in any second quarter before, trailing twelve-month revenue above $100 billion for the first time, and a balance sheet with $45.4 billion of liquidity against $9.5 billion of debt as of September 30, 2026.
The back carried the ingredient list, and it was just as true: on every $100 of revenue in the quarter ended June 30, 2026, $1.41 of operating profit remained. Three quarters of pre-tax income came from remeasuring a stake that was four months old. An earnings component with no cost of goods, still worth 46 percent of operating income in 2025, has shrunk by two thirds. And the compensation footnote carries a twelve-digit number.
The third quarter of 2026 reprinted the package. The front now reads "Super Intelligence," the ten millionth vehicle and Cybercabs in the Austin Robotaxi service. The back reads $2.56 of operating profit on every $100 of revenue — better than in the summer, weaker than a year earlier —, a compensation line larger than operating income, and $30 billion of credit commitments for an investment wave whose return does not yet appear in any segment line.
None of this is a scandal or an accusation. It is a company in the middle of a rebuild, and in its 10-Q for the quarter ended June 30, 2026 it described that rebuild in its own words: it is "investing heavily in research and development to accelerate our AI, software and fleet-based profits for further revenue growth, which will negatively impact our profitability during this phase." An honest sentence. It just does not say how long the phase lasts — and the third quarter did not say either.
What you make of that is your decision. And that is exactly as it should be. We have shown you both sides of the package — the large print and the small.
Sources
- Tesla, Inc., "Q3 2026 Update" earnings release (Form 8-K, Item 2.02, Exhibit 99.1) dated October 21, 2026 (CIK 0001318605)
- Tesla, Inc., third-quarter 2026 production, deliveries and deployments release (Form 8-K, Item 2.02, Exhibit 99.1) dated October 2, 2026
- Tesla, Inc., current report on the credit agreements (Form 8-K, Items 1.01, 1.02 and 2.03) dated September 29, 2026
- Tesla, Inc., 2026 proxy statement (Form DEF 14A) dated October 19, 2026
- Tesla, Inc., Form 10-Q for the quarter ended June 30, 2026, filed July 23, 2026
- Tesla, Inc., Form 10-K for fiscal year 2025, filed January 29, 2026
- Tesla, Inc., "Q2 2026 Update" earnings release (Form 8-K, Item 2.02, Exhibit 99.1) dated July 22, 2026
- Tesla, Inc., second-quarter 2026 production, deliveries and deployments release (Form 8-K, Item 2.02, Exhibit 99.1) dated July 2, 2026
- SEC EDGAR filing index for Tesla, Inc. (CIK 0001318605) — review of every filing from July 22, 2026 onward, as of October 22, 2026, including the routine Form 144 (September 8, 2026) and Form 4 (September 9, 2026). The Form 10-Q for the quarter ended September 30, 2026 had not been filed as of that date.
- Fundamental data (prices, forward price/earnings ratio, analyst consensus), as of October 22, 2026
This analysis is journalistic commentary on publicly available corporate filings. It is not investment advice, not a buy or sell recommendation and not a solicitation to buy or sell securities. Stocks can lose substantial value, up to a total loss. All figures come from the primary sources named above and carry the as-of date stated there; they may have changed since. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this analysis.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 53,823.0 | 81,462.0 | 96,773.0 | 97,690.0 | 94,827.0 |
| Operating Income (EBIT) | 6,687.0 | 13,656.0 | 8,891.0 | 7,076.0 | 4,355.0 |
| Net Income | 5,644.0 | 12,587.0 | 14,974.0 | 7,130.0 | 3,794.0 |
| Net Margin | 10.5% | 15.5% | 15.5% | 7.3% | 4.0% |
| Earnings Per Share | 1.82 $ | 3.62 $ | 4.30 $ | 2.04 $ | 1.08 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
Our Bottom Line at a Glance
- Volume and market position positive
- In the quarter ended 2026-09-30 Tesla delivered 486,532 vehicles, 2 percent fewer than a year earlier; production rose 4 percent, and 10.2 million vehicles have been delivered since inception. Trailing twelve-month revenue topped $100 billion for the second quarter in a row. Energy storage deployments rose 10 percent to 13.7 GWh (8-K dated 2026-10-21, Exhibit 99.1).
- Balance sheet and liquidity positive
- As of 2026-09-30 Tesla held $45,447M of cash and short-term investments against $9,523M of debt and finance leases, $9,265M of which is non-recourse to the parent. Equity ratio 56.7 percent. Since 2026-09-29 Tesla has $30 billion of credit commitments, none of it drawn (8-Ks dated 2026-09-29 and 2026-10-21).
- Earning power of the running business negative
- Operating income fell 56 percent to $718M in the quarter ended 2026-09-30, and the operating margin from 5.8 to 2.6 percent — on practically flat revenue. Annually: $8,891M (2023), $7,076M (2024), $4,355M (2025). Research and development expense rose 69 percent in the quarter (8-K dated 2026-10-21).
- Quality of earnings negative
- In the quarter ended 2026-06-30, $1,005M of $1,329M pre-tax income came from remeasuring the SpaceX stake; in the quarter ended 2026-09-30 the stake cost $142M while bitcoin added $288M. Stock-based compensation of $1,165M exceeded operating income of $718M (8-K dated 2026-10-21, reconciliation table).
- An earnings component that is disappearing negative
- Automotive regulatory credits fell 73 percent to $113M in the quarter ended 2026-09-30; in 2025 they were still $1,993M and equal to 46 percent of total operating income. In its 10-Q for the quarter ended 2026-06-30 Tesla cited governmental and regulatory actions that have restricted certain programs.
- Investment load and compensation neutral
- Tesla spent $13,014M on capital expenditures from January to September 2026, against guidance above $25,000M for 2026 (10-Q for the quarter ended 2026-06-30). Free cash flow turned to +$1,531M in the third quarter, supported by $2,590M from working capital. In parallel runs a compensation award covering 423,743,904 shares with unrecognized expense of $105.82 billion to $120.37 billion (as of 2026-06-30).
Tesla books more than $100 billion of revenue over twelve months, has built its ten millionth vehicle and held $45,447M of liquidity against $9,523M of debt as of 2026-09-30 — plus $30 billion of undrawn credit commitments. The price sits in the same filings: $718M of operating income on $28,046M of revenue, 73 percent less in regulatory credits, stock-based compensation above operating income, $13,014M of capital expenditures in nine months, and a quarterly profit that in the prior quarter came three quarters from an investment remeasurement. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
Substance is not the problem: $45.4 billion of liquidity against $9.5 billion of debt as of 2026-09-30, a 56.7 percent equity ratio, $30 billion of undrawn credit commitments. As of September 30, 2026, Tesla is far from a going-concern warning, over-indebtedness or interest-coverage trouble. What remains open is the operating question, and the third quarter of 2026 did not answer it: $718 million of operating income on $28,046 million of revenue is 2.6 percent, better than the 1.4 percent of the prior quarter but less than half the prior-year quarter. Earnings halved from 2023 to 2025 while revenue stood still, regulatory credits keep disappearing, and capital expenditures climb before Robotaxi, driver assistance and robotics show up in a segment line of their own. That is why the rating stays yellow — neither green nor red. The stock is expensive on top of that — a trailing multiple around 475 leaves little room for disappointment. That is a price argument and does not set this rating; the operating question does. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- Hook of the first edition (2026-07-29): ranking of the 100 largest U.S. stocks by market capitalization (as of 2026-07-28); Tesla sat at rank 9 without an existing analysis.
- Update of 2026-10-22: figures for the quarter ended 2026-09-30 from the Form 8-K earnings release dated 2026-10-21 (Item 2.02, Exhibit 99.1). The Form 10-Q for the quarter ended 2026-09-30 had not been filed at press time; items only it carries remain dated 2026-06-30. Every filing from 2026-07-22 onward was reviewed, including the routine Form 144 (2026-09-08) and Form 4 (2026-09-09). Valuation metrics as of 2026-10-22.
- Cyclical caveat: Tesla is an automaker and describes its industry as cyclical in its own quarterly report. Neither the 2023 earnings peak nor the 2026 trough works as an extrapolation. Net income in 2023 also contained a tax benefit, which is why it exceeded operating income ($14,997M against $8,891M).
- Not to be confused: Tesla, Inc. was named "Tesla Motors Inc" until 2017-01-27 and has been a Texas corporation since 2024-06-13, no longer a Delaware one. Older lawsuits therefore continue before Delaware courts.
- Analyses are evergreen; a daily share price is not a buy argument.
Stock Watch
This analysis is as of October 22, 2026. Stock Watch will tell you what's changed at TSLA since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Tesla Inc (TSLA), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
By selling vehicles. Of the $28,046 million of revenue in the quarter ended September 30, 2026, automotive sales accounted for $20,094 million, services and other for $4,605 million, energy generation and storage for $2,881 million, automotive leasing for $353 million and regulatory credits for $113 million. Vehicle sales and leasing therefore represent roughly 73 percent of revenue.
Because costs rose. In the quarter ended September 30, 2026 revenue of $28,046 million was practically flat year over year, but research and development expense rose 69 percent to $2,761 million and selling, general and administrative expense rose 29 percent to $2,015 million. On top came $304 million less in regulatory credits. Operating income landed at $718 million, down from $1,624 million in the prior-year quarter.
Carmakers must meet emissions rules in many markets. Those who exceed them may sell the surplus credits to other manufacturers. Tesla incurs no cost of revenue for them, so the proceeds flow almost entirely into gross profit. In 2025 they came to $1,993 million — 46 percent of total operating income. In the quarter ended September 30, 2026 only $113 million was left, a 73 percent decline.
Tesla discloses no separate revenue line for either. What is documented: 1.74 million active FSD subscriptions as of September 30, 2026, up from 1.04 million a year earlier, counted including upfront purchases. As of June 30, 2026 the balance sheet carried $4.05 billion of deferred revenue for connectivity, FSD and software. Since September 3, 2026 Cybercabs have been giving Robotaxi rides in Austin; by quarter-end the service had logged nearly two million unsupervised miles.
From January through September 2026 Tesla spent $13,014 million on capital expenditures. The Form 10-Q for the quarter ended June 30, 2026 guided to more than $25 billion for the full year; the third-quarter earnings release gives no new figure. As of September 30, 2026 Tesla had $45,447 million of cash and short-term investments. Since September 29, 2026 it also has $30 billion of credit commitments, none of which it plans to draw in 2026.
The award granted on September 3, 2025 and approved by shareholders on November 6, 2025 covers 423,743,904 performance-based shares across twelve tranches. Each tranche requires a market-capitalization milestone — from $2.0 trillion to $8.5 trillion — plus operational milestones such as 20 million vehicles delivered or $400 billion of adjusted EBITDA. Unrecognized expense for the milestones deemed not probable of achievement ran from $105.82 billion to $120.37 billion as of June 30, 2026.
Little, measured against the balance sheet. As of September 30, 2026 debt and finance leases totaled $9,523 million, of which $9,265 million was non-recourse to the parent — secured by vehicles, receivables and energy assets. Against that stand $45,447 million of liquidity and $89,289 million of stockholders' equity. The new $30 billion of credit facilities was entirely undrawn as of September 29, 2026.
As of June 30, 2026 Tesla held 11,509 bitcoin at an acquisition cost of $386 million. The carrying value of the whole crypto holding (mostly bitcoin per the 10-Q) rose to $962 million by September 30, 2026, from $674 million at June 30. Under fair-value accounting these swings run straight through the income statement: they reduced earnings by $334 million in the first half of 2026 and produced a $288 million remeasurement gain in the third quarter.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.