POET Technologies: $1.07 Million of Annual Revenue — and $830 Million of Fresh Equity
POET Technologies builds optical chips for AI data centers, and the technology story is a good one: the Optical Interposer is meant to take costly hand assembly out of transceiver manufacturing. The filings with the U.S. securities regulator, the SEC, tell the second half. In 2025, $1,074,865 of revenue faced $43.17 million of operating expenses; shares outstanding grew from 76.5 million to 173.1 million (August 13, 2026); and in April 2026 Marvell cancelled every order from the first production contract in company history — stating that POET had breached confidentiality. The half-year figures of August 13, 2026 barely shift the weights: $569,925 of quarterly revenue, $4.3 million of interest income, $796.3 million in the bank. We do the arithmetic on how much of this valuation rests on contracts and how much on anticipation.
 Thomas Mücke
Founder & Publisher
As of Today
As of: November 3, 2026
- Closing price
- 5.10 $ +6.20%
- Market Capitalisation
- 0.9 $B
- Growth Score
- 5/10
- AAQS
- 4/10
Price change since August 4, 2026: -31.1%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot

Chart
Interactive price chart (TradingView).
52-week range: 4.20 $ to 20.60 $ · Last price: 5.10 $ (As of: November 3, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
There is a trap that catches the technically literate investor in particular — and walking into it feels like diligence. Call it the blueprint trap. It works like this: you read your way into a technology, you genuinely understand it, you see why it beats the state of the art — and your mind quietly adds the next step: “if the technology works, the revenue will follow.” A good blueprint feels like a finished house. It is not. Between blueprint and house lie customers, qualification cycles, yield rates, supply agreements and years.
POET Technologies Inc. (Nasdaq: POET) of Toronto is a case study. The company builds the Optical Interposer — in plain terms, a base plate on which the photonic and electronic parts of an optical transceiver are assembled at wafer level in one pass, rather than aligned one by one by hand. For AI data centers pushing data between servers at 800 gigabits and 1.6 terabits per second, that sounds like exactly the right idea at the right moment. And the market listened: POET has raised $830 million of fresh equity in twelve months.
So let us make a deal. Before you decide whether there is a house here or a blueprint, we read together what the company itself filed with the U.S. securities regulator, the SEC: the annual report on Form 20-F for 2025 of March 31, 2026, the interim statements as of March 31, 2026 from the report on Form 6-K of May 15, 2026, the prospectus supplement (424B5) for the $400 million offering of May 18, 2026, the interim statements as of June 30, 2026 from the report on Form 6-K of August 13, 2026, and every filing through September 26, 2026. Such filings are honest under penalty of law. At the end, you decide — that is the point of the exercise.
Update: the second quarter of 2026 at a glance
As of this update: September 26, 2026 (interim statements as of June 30, 2026 plus MD&A, both filed on August 13, 2026). The first edition of this analysis, of July 29, 2026, rested on the March 31, 2026 figures. POET held no earnings call for the quarter — the results release names none, so no transcript exists. Instead we worked through the statements, management’s discussion and analysis (MD&A), the results release and every filing through September 26, 2026. The key points:
- Revenue: $569,925 in the second quarter of 2026, after $503,389 in the first quarter and $268,469 a year earlier. The first half of 2026 brought $1,073,314 — almost exactly full-year 2025 revenue ($1,074,865). The direction is right, the scale is not: it is still half a million a quarter, mostly engineering services.
- Interest still beats products by a wide margin. $4,299,496 of other income including interest faced $569,925 of revenue in the second quarter — 7.5 times as much.
- The operating loss is growing: $20,190,471 in the second quarter after $17,870,158 in the first; $38.06 million for the half-year — nearly as much as all of 2025 ($42.09 million). Operations consumed $21,079,966 of cash in the half-year, $12.2 million of it in the second quarter. The $11,338,060 net loss looks smaller only because remeasuring warrants produced a $5.53 million book gain.
- The treasury is full: $432,531,904 of bank balances plus $363,809,999 of guaranteed investment certificates, $796.3 million in total as of June 30, 2026. Our estimate in the first edition (“call it $800 million”) has held up.
- The U.S. redomiciliation is off. The board “determined that, at the present time, it is not in the best interests of the Company to move forward with redomiciling to the United States”, the results release of August 13, 2026 says. POET thus remains a Canadian corporation — with the PFIC question left open (see “Uncomfortable truth no. 4”).
- New customer signals — without names. After the quarter POET received a $2.4 million purchase order from an existing customer and signed an agreement with a “Tier 1 laser company” to develop an external light source engine. For the remaining quarters of 2026 the company expects to ship “substantial numbers of production units for qualification” — units for customer testing, not volume revenue.
- Board: since August 1, 2026 Dr. Bardia Pezeshki (founder of Avicena Tech, Kaiam and Santur) and the former general counsel Jean F. Rankin sit on the board; Jean-Louis Malinge stepped down for personal reasons after nine years (report of August 3, 2026).
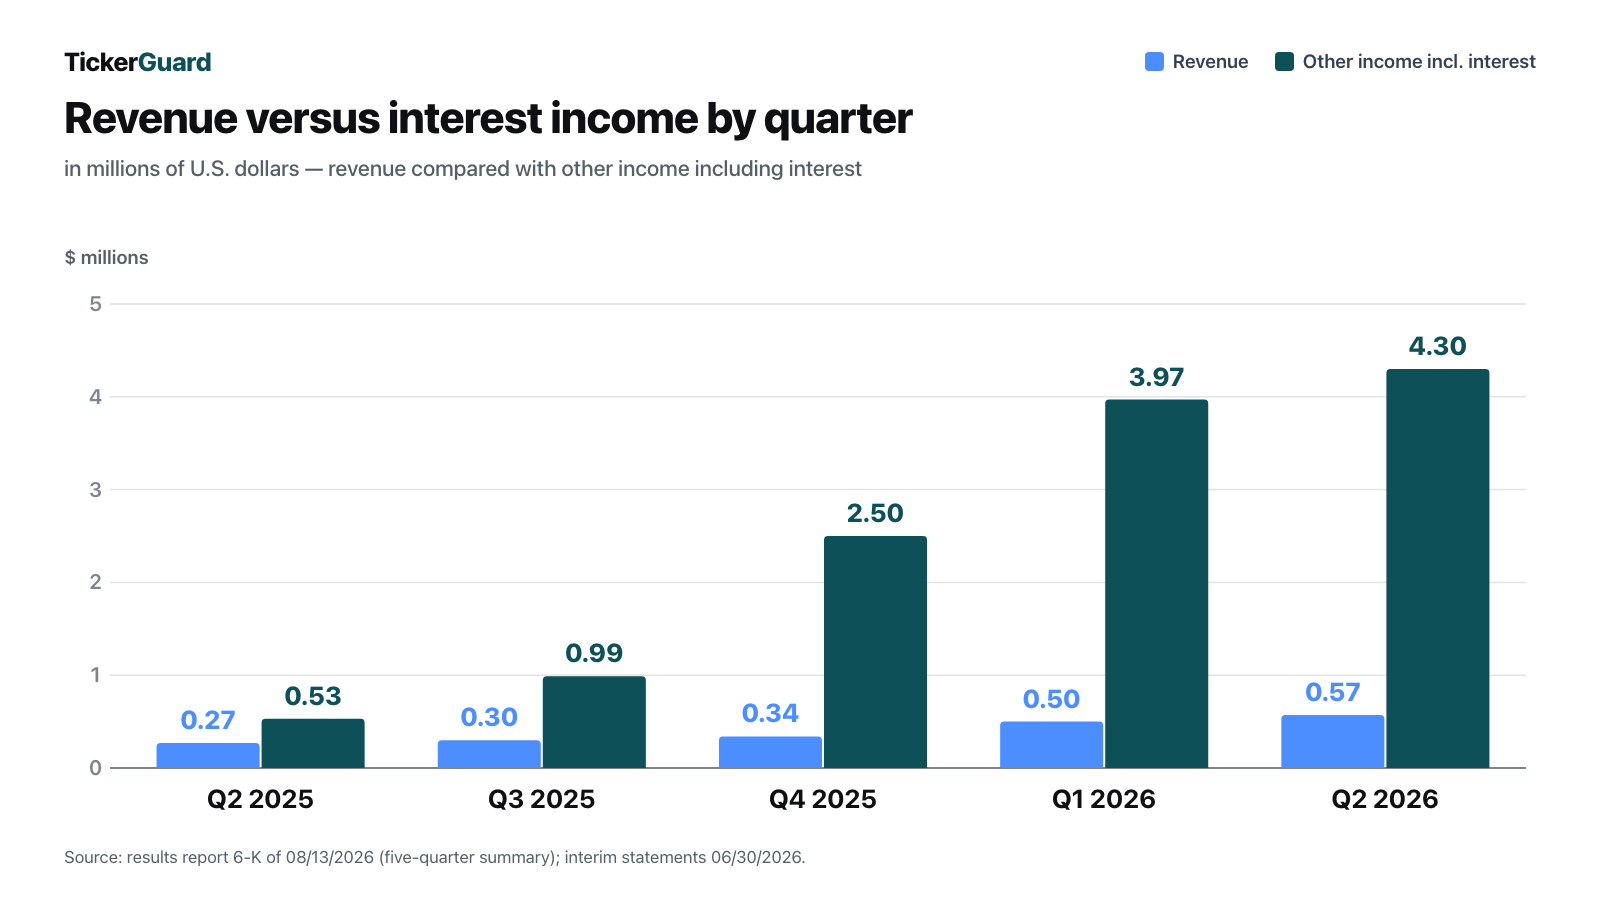
Three findings from the fine print of the interim statements deserve more than a bullet point.
First: the Lumilens warrant is now on the books — as consideration paid to the customer. The asset side carries a new line, “Deferred customer consideration”, of $30,142,069: the fair value of the 2,292,140 immediately exercisable Lumilens warrants. Note 24 says what happens to it:
“The deferred customer consideration will be amortized as the Company begins to recognize product revenue from the customer.”
— POET Technologies Inc., interim statements as of June 30, 2026, note 24 (exhibit 99.1 to the SEC report 6-K of August 13, 2026)
In everyday terms: POET handed the customer a discount voucher before the first dollar of product revenue arrived. Under IFRS 15, consideration paid to a customer generally reduces the revenue reported from that customer — that is our reading; the statements do not name the line explicitly. As of June 30, 2026 the item still stands at its full amount, which suggests POET had booked no product revenue from Lumilens by then. A blemish at the margin: note 24 dates the grant “May 13, 2025” and gives different valuation assumptions than note 21 for the same amount — the release announcing the agreement is dated May 14, 2026. In unaudited interim statements that is no drama, but a sign of how carefully you have to read here.
Second: an unnamed financial adviser costs more than the product business brings in. The line “Finance advisory fees” came to $9,425,000 in the first half of 2026, $6,172,500 of it in the second quarter — 8.8 times half-year revenue. Per the MD&A the fees go to “a firm assisting the Company on financial and strategic matters”, whose guidance contributed to capital raises exceeding $840 million since 2024. Who the firm is, it does not say. On top of that came $2,955,150 in the half-year for 4.99 percent of the preferred shares of Lessengers Inc. — the partner on the 1.6T module, which the MD&A now describes as “one of its key suppliers”.
Third: per its filing, the buyer of the $400 million offering no longer holds common shares. MMCAP International Inc. SPC reported exactly the 19,047,620 shares it bought (11.0 percent) on May 20, 2026. The ownership filing of August 14, 2026 instead shows 19,155,361 shares, 9.99 percent as of June 30, 2026 — consisting “entirely of Common Shares underlying warrants that can be exercised within 60 days”. That fits how POET itself splits the price of that offering: of the $400,000,020, note 11 allocates $275,031,848 to the accompanying warrant, leaving roughly $6.56 per share. On the day of the announcement, May 15, 2026, the stock closed at $15.97. The chief executive describes the raise in the results release as “priced at a premium to market” — by POET’s own accounting, that premium sits almost entirely in the warrant, not in the share.
Bottom line, the second quarter confirms the thread of this analysis: more money, more shares, more announcements — and still no volume revenue. The chapters below have been brought forward to June 30 or August 13, 2026; where a figure is older, its date stands beside it.
Company history for investors
-
1972
Incorporated as Tandem Resources Ltd.
The corporate shell began in 1972 in British Columbia as a mining company — decades before it became a photonics developer.
-
2006
Renamed OPEL International Inc.
The mining shell became OPEL International in 2006 — the first step away from its original business.
-
2010
Renamed OPEL Solar International Inc.
In 2010 the company briefly operated in the solar business before pivoting again.
-
2011
Renamed OPEL Technologies Inc.
2011 brought another renaming — the photonics focus had not yet arrived.
What POET Technologies actually does
An optical transceiver is the plug through which a data center pushes data into a fiber-optic cable. It turns electricity into light and light back into electricity. Inside that plug sits an optical module in which lasers, modulators, photodiodes, lenses and driver chips have to be aligned to within microns. Today that is largely done part by part — expensive, slow, hard to scale. In everyday terms: every watch is assembled by hand instead of stamping movements in series.
This is where POET comes in. The annual report puts it plainly: the platform “eliminates costly components and labor-intensive assembly, alignment, and testing methods employed in conventional photonics.” On that base plate the company builds optical engines — the working core of a module — at the industry speeds of 800G and 1.6T, plus the POET Blazar light source line, a hybrid laser meant to link servers and chips directly. In the company's own words:
“We believe that chip-scale integration is essential to developing hardware that can meet such demands and that POET is on the forefront of providing scalable solutions for current and future AI systems.”
— POET Technologies Inc., SEC annual report 20-F for 2025, introduction, section “Business of POET Technologies Inc.”
None of the building happens in Canada: POET keeps its head office in Toronto, develops in Singapore, assembles in Penang, Malaysia, and runs an additional unit in Shenzhen. As of December 31, 2025 the annual report counted 80 full-time employees, 52 of them in Singapore; by the report of May 18, 2026 it was “more than 115 globally”, and at the end of June 2026 the company said it would add roughly 50 more within a few months. A firm the size of a mid-sized workshop, then — carrying a market value in the billions.
A word on where the shell came from, because it explains how this ticker has existed for decades without ever selling much. The prospectus supplement of May 18, 2026 traces the chain: incorporated in British Columbia on February 9, 1972 as Tandem Resources Ltd., a mining shell; renamed OPEL International Inc. in 2006, OPEL Solar International Inc. in 2010, OPEL Technologies Inc. in 2011, and only on July 23, 2013 POET Technologies Inc. From mining shell to solar to photonics. That is not an accusation, but it is a reminder that the corporate shell is older than any product inside it. Readers who like special situations will know the pattern from our analysis of Laser Photonics — a big story wrapped around a small revenue line there too.
Which names the central tension of this analysis, and it runs through every chapter: the technology is real and the treasury is full — but proof that anyone buys this technology in meaningful volume is still outstanding.
How the stock reached our desk
Honesty first: POET is not a scanner hit. As of July 29, 2026 the stock appears in no list of our in-house stock scanner — not in the momentum filters, not in the quality or value screens. That is no mystery: almost every quality filter needs earnings and almost every value filter needs revenue, and POET has too little of both. (Our lists are recomputed daily; the statement holds for that date.)
What put the stock on the desk was the SEC filing stream — the place where companies must publish things they would rather not discuss. Two filings three weeks apart stood out: on April 27, 2026 the cancellation of every purchase order from a major customer, and on May 15, 2026 a capital raise of $400 million from a single institutional investor — MMCAP International Inc. SPC, a Cayman Islands fund managed by MM Asset Management Inc. of Toronto, which subsequently reported holding 19,047,620 shares, or 11.0 percent of the company. This was no stranger writing the cheque: in an ownership filing of May 15, 2026, MMCAP already reported 14,516,820 shares as of March 31, 2026 — 13,022,782 of them underlying warrants — or 9.99 percent. Whoever put up the $400 million was already the largest single holder. A company that loses its flagship order and then raises 372 times its annual revenue in equity within three weeks deserves a second look.
One more data point for context: according to the fundamental data available to us (as of July 29, 2026), two analysts cover the stock — and that had not changed by September 26, 2026. Two. For a business valued in the billions that is remarkably thin — it means almost nobody stands between you and this stock doing the arithmetic professionally. Remember that: where few people look, you have to look harder yourself.
The numbers over the years — given their due
First the things that genuinely impress, and there are more of them than the revenue line suggests.
The balance sheet is exceptional. As of June 30, 2026 the interim statements show $432,531,904 in cash and a further $363,809,999 in short-term investments — per note 2, exclusively guaranteed investment certificates held with Canadian banks. Together that is $796.3 million of immediately or near-immediately available funds; as of March 31, 2026, before the May raise, it was $429.1 million, only $16.5 million of it as cash. Watch that distinction, it is a classic trip wire: read only the line marked “cash” and the account looks tight or lavish depending on the date. What counts is the total — the money often sits one line lower, in term deposits.
Against that stand, as of June 30, 2026, $34.3 million of total liabilities — $22.0 million of it the carrying value of warrants POET must book as a liability, plus $5.8 million of convertible debt from the purchase of a minority stake. Shareholders' equity is $847.5 million against total assets of $881.8 million — an equity ratio of roughly 96 percent. The company holds no credit lines, and the interim statements say so as drily as the annual report: “The Company currently does not maintain credit facilities.” A business without debt does not need any.
One balance sheet item does deserve its own look, because it does not belong on a chip developer: $30,644,384 of “Loan receivable” as of June 30, 2026. POET has been lending money. Per note 22, $10 million went out on January 7, 2026, $5 million on January 21 and a further $15 million on April 23, 2026 to an entity the report identifies only as “the Borrower” — $30 million in total, 28 times 2025 revenue. It carries 6 percent interest, falls due after five years or earlier on a “Liquidity Event” of the borrower, and under certain conditions POET may convert it into equity of the borrower. That is the architecture of a venture investment. The loan is now measured at fair value on unobservable (“Level 3”) inputs, including, per note 18, “strategic transaction probabilities”. Who the borrower is, the half-year statements do not say either.
Revenue is growing — off a minuscule base. 2025 brought in $1,074,865, after $41,427 in 2024. That is a gain of roughly 2,495 percent, and it shows you exactly how little percentages are worth when the denominator is tiny. The first quarter of 2026 delivered $503,389, the second $569,925 — the sixth consecutive quarter of sequential growth, as the results release stresses, and a little over double the prior-year quarter ($268,469). But still a little over half a million dollars in three months.

Something commercial is moving. On May 14, 2026 POET announced a supply agreement with Lumilens Inc., including an initial purchase order of $50 million for engines based on the Electrical-Optical Interposer; the release says the relationship could scale to more than $500 million cumulatively over five years. One detail of the same release stays invisible in the order figure and belongs here anyway: in return, POET granted Lumilens a warrant on up to 22,921,408 of its own shares at $8.25 with a nine-year term — immediately exercisable for 2,292,140 shares, with the remainder vesting in tranches according to how much Lumilens actually orders and pays. The customer pays with orders and becomes a shareholder for it; for existing holders that is dilution which shows up in no price-to-sales calculation. Development partnerships with LITEON Technology and Lessengers (a 1.6T transceiver module) were announced as well. And at the annual meeting on June 26, 2026 the chief executive cited “more than 10 active customer engagements” expected to exceed $100 million of future annual revenue combined. After June 30, 2026 the results release added a $2.4 million order from an existing customer and a development agreement with a major laser maker — both unnamed.
Internal control has been repaired. Fairness demands this be said: for 2024 the auditors had identified a material weakness — a substantive gap in accounting controls, because too few people could properly review the financial close. POET hired staff, and as of December 31, 2025 the audit firm Davidson & Company LLP declared internal control over financial reporting effective, with an unqualified opinion on the statements as well. Shareholders confirmed the auditors on June 26, 2026 with 97 percent of votes cast. And one more legacy item is gone: for 2023 the previous auditor, Marcum LLP, had still noted “substantial doubt about the Company's ability to continue as a going concern.” That paragraph is absent from the 2025 opinion; in the annual report for 2025 it survives only where the old 2023 report is reprinted. With $796 million on hand (June 30, 2026) it would be hard to justify; the half-year statements expressly consider the funds sufficient “beyond one year”.
One item does remain open, in the fine print of the interim statements. Among events after the reporting date, the March 31, 2026 statements (note 23(b)) said POET was “threatened with and named as defendants to a pending legal action” in the ordinary course of business; the company does not believe the outcome will be material and is assessing its response. The half-year statements repeat that almost word for word in note 25, and the MD&A adds that POET incurred professional fees “in defense of a claim” in the second quarter and “does not have an update on the status of claim at this point”. Who is suing and over what still does not appear there. We mention it because it is the only legal matter in the filings reviewed — not because any link to the April 2026 cancellation is documented. No filing asserts such a link.
The takeaway for this chapter: POET has solved its funding problem. It has not yet solved its selling problem.
What the filings say — the uncomfortable truths
Uncomfortable truth no. 1: annual revenue does not cover nine days of operating costs
Let us do the arithmetic, because the order of magnitude does not land otherwise. In 2025 POET took in $1,074,865. In the same year it spent $43,166,260 running the business — $25.08 million on selling, marketing and administration, $18.08 million on research and development. The operating loss came to $42,091,395. Full-year revenue therefore covers roughly nine days of operations.
Nor is this an accounting artifact: operations consumed a real $31,086,629 of cash in 2025 and another $21,079,966 in the first half of 2026 — $8.8 million in the first quarter and $12.2 million in the second. The pace is rising. The good news there is arithmetic: at roughly $10.5 million of quarterly cash burn (the first-half 2026 average) and $796.3 million of liquid assets as of June 30, 2026, the money lasts for many years on paper. The bad news: it has to last for many years, because almost nothing is coming in from sales.
The annual report frames the risk with rare clarity — not marketing copy, but the risk factors section:
“We have limited experience in selling products in this market. We may not be successful in developing a product for this market and even if we do, it may never gain widespread acceptance by large data center operators.”
— POET Technologies Inc., SEC annual report 20-F for 2025, Item 3.D “Risk Factors”
One more detail from the notes: revenue comes, per note 21, from “non-recurring engineering services and product sales” — NRE for short. Translated: a customer pays once for a piece of development work. That is not recurring revenue, it is paid preparation. At $1.07 million a year the distinction is academic — but when you read future quarters it is the single most important one: volume shipments repeat, engineering projects do not.
Uncomfortable truth no. 2: the first production order in company history was cancelled
On April 25, 2023 POET announced its first purchase orders for production units — for a company that had been developing for decades, a milestone, and for years the shareholders' strongest argument. The customer was Celestial AI. Three years later came the counter-announcement. On April 23, 2026 Marvell Semiconductor Inc., which had acquired Celestial AI, cancelled every order in writing. The decisive sentence from the report of April 27, 2026 sits in the SEC archive:
“Marvell indicated that the Company had made disclosures of information related to the Purchase Order and shipping information in contravention of its confidentiality obligations.”
— POET Technologies Inc., SEC report 6-K of April 27, 2026, exhibit 99.1

Read the reason again. The order was not lost because the product failed, because the price was wrong, or because the customer switched technologies. It was lost because the customer accuses POET of talking too much about him. For a company whose share price fed on order announcements for years, that is a striking finding — it touches not the engineering but the way the business communicates. The same report points to an order “with another technology company with a value of approximately $5 million” — one it calls recently disclosed, so it is not a replacement for the cancelled volume. Three weeks later the $50 million Lumilens order followed. Both are announcements, not booked revenue — and that distinction is the lesson of this chapter. The second quarter of 2026 changed nothing about that: $569,925 of revenue, and the item for the Lumilens customer consideration still sits on the balance sheet at its full amount as of June 30, 2026.
Uncomfortable truth no. 3: 76.5 million shares became 173.1 — and could become 261
Dilution sounds harmless and is not. The everyday picture: the cake stays the same size, but more and more people sit down at the table. Your slice shrinks without your having done anything wrong. At POET the table was still manageable in January 2025.

The figures come from the filings themselves: 76,507,157 shares on January 1, 2025 and 132,021,526 on December 31, 2025 (note 11(b) of the interim statements), 152,893,604 on March 31, 2026 and 153,547,786 on May 15, 2026 (prospectus supplement of May 18, 2026), 172,595,406 immediately after the May offering, 172,590,000 for the annual meeting of June 26, 2026, 173,035,169 as of June 30, 2026 (note 11(b) of the half-year statements) and 173,058,088 on August 13, 2026 (MD&A).
The annual report does the rest of the math itself — as of March 20, 2026, so before the May offering:
“If all of these securities were exercised, an additional 43,157,406 common shares would become issued and outstanding. This represents an increase of 28.35% in the number of shares issued and outstanding and would result in significant dilution to current shareholders.”
— POET Technologies Inc., SEC annual report 20-F for 2025, Item 3.D “Risk Factors”

Since the May offering the sum has grown. The prospectus supplement of May 18, 2026 arrived at 238.1 million shares — and left out the warrant POET had granted its customer Lumilens four days earlier; its warrant count matched the March 31, 2026 position exactly. The half-year statements close that gap. Per the MD&A, alongside the 173,058,088 shares outstanding on August 13, 2026 there were 78,734,968 warrants with exercise prices between $1.09 and $26.25 — including the 19,047,620 from the May offering at $26.25 and the Lumilens warrant on up to 22,921,408 shares at $8.25, of which only 2,292,140 are exercisable —, plus 5,369,393 options and 4,252,504 share units.
Together that is 261.4 million shares: 88.4 million potential shares on top of the 173.1 million outstanding, roughly 51 percent more. And the list keeps growing: on August 11, 2026 the board approved a further 2,453,271 restricted share units for officers, sized off the $8.56 closing price of August 10, 2026, per the results release. They cannot be fully included in the MD&A figure for August 13 — it sits only 366,551 units above the June 30 level. Counting them, the total would be up to 263.9 million. The warrants alone could bring in “up to an additional $661 million”, as POET itself calculates in the report of June 30, 2026; how that sum splits across the individual warrants it does not say.
And now the figure that makes dilution tangible. The prospectus supplement for the May offering states the tangible substance behind each share:

$2.94. Note the word historical in the original: that is the substance per share before the May offering, calculated on the 152.9 million shares outstanding at March 31, 2026. The investor in the May offering paid $21.00 per share plus warrant, and the prospectus computes the gap itself as an “immediate dilution of $16.08 per common share” to that investor. The same table also states the figure after the offering: $4.92 per share (“pro forma as adjusted net tangible book value per share after giving effect to this offering”). Those $4.92 are almost entirely cash as well. The half-year statements confirm the order of magnitude: $847.5 million of equity over 173.0 million shares gives roughly $4.90 of book value per share as of June 30, 2026 (our calculation). Anyone buying POET today buys an expectation at a multiple of that substance — normal for a growth company, but you should know the ratio between the two.
And one postscript to that offering, visible only with hindsight: the investor paid $21.00 per share plus warrant on May 18, 2026. On July 28, 2026 the stock stood at $6.76 — roughly 68 percent below the issue price; on September 25, 2026 it closed at $7.77, still 63 percent below. The accompanying warrant, exercisable at $26.25, is a long way out of the money. As the half-year statements show, POET itself assigned the larger part of the price to the warrant anyway: $275.0 million of the $400 million, leaving roughly $6.56 per share (see the “Update” chapter). For POET none of that matters: the $400 million was paid and sits in the bank. For you as a shareholder it is still a lesson in the difference between a sum raised and a price held — and in how little an issue price says about the worth of a business.
Uncomfortable truth no. 4: U.S. tax law treats POET as a pot of money, not a business
This finding is the quietest and the most revealing. On April 14, 2026 POET disclosed that it will be treated as a Passive Foreign Investment Company (PFIC) for fiscal 2025.
“Based on our income and assets for the year ended December 31, 2025, we currently believe that we will be treated as a PFIC for the year ended December 31, 2025.”
— POET Technologies Inc., SEC report 6-K of April 15, 2026, exhibit 99.1

What that means is spelled out in the annual report: a foreign corporation is a PFIC if either 75 percent or more of its gross income is passive — interest, dividends, rents — or 50 percent or more of its assets produce such income. At POET the ratio is unambiguous: $4,553,061 of other income including interest in 2025 against $1,074,865 of revenue. Under that heading POET booked roughly four times what the product business brought in. On the asset side it is starker still: 96 percent of total assets as of December 31, 2025 were current assets, almost entirely cash and term deposits.
For a U.S. holder the classification carries real tax consequences, which is why the company committed to providing the information needed for a “QEF” election. But as a diagnosis it is worth more than that: an independent, formula-driven test under U.S. tax law concludes that in 2025 this business was economically closer to a pot of money with a development department attached than to a manufacturer. That is the blueprint trap in one sentence. The board announced on April 14, 2026 that it would redomicile in the United States — which would have settled the PFIC question going forward but changed nothing about the cause.
In fairness, the second half of that disclosure belongs here too: for fiscal 2026 POET said in April that it did not expect PFIC status — “we believe that we will not qualify as a PFIC”, per the chief financial officer — while conceding in the same text that the answer depends on income and assets for the full year. Four months later it sounds different, and that change in tone is the most revealing sentence in the half-year report. On August 13, 2026 the board dropped the redomiciliation “at the present time”, and the MD&A now reads:
“[The Company] may continue to be classified as a PFIC for the current and possibly future taxable years.”
— POET Technologies Inc., MD&A as of June 30, 2026, exhibit 99.2 to the SEC report 6-K of August 13, 2026
A few sentences later the same text says POET expects “that it may not be classified as a PFIC for the current the taxable year” — but April’s “we believe we will not” has become a “may not”. The numbers explain why: the first half of 2026 brought $8,269,787 of other income including interest against $1,073,314 of revenue, and 91 percent of total assets as of June 30, 2026 were current assets, essentially cash and term deposits.
Dropping the redomiciliation also removed an automatic trigger for losing foreign private issuer status. The annual report carries that loss as a risk factor of its own (“The Company will likely lose its foreign private issuer status”) and names June 30, 2026 as the annual test date. Through September 26, 2026 POET has disclosed nothing on the outcome; the half-year report of August 13, 2026 was filed as usual as a 6-K by an annual-report filer on Form 20-F. If the status does go, the company will have to file U.S. quarterly reports (10-Q) under U.S. GAAP — more work for POET, more numbers for you.
Uncomfortable truth no. 5: the quarterly profit that never was
Finally, a number many investors misread in the spring of 2025. In the first quarter of 2025 POET reported net income of $6,341,558, or $0.08 per share. A profitable quarter! Except that revenue in that quarter was $166,760 and the operating loss $9.54 million. The profit came from a line further down: a fair value adjustment to the derivative warrant liability of $15,382,971.
Here is the mechanism. Because part of the warrants are denominated in Canadian dollars, accounting rules force POET to carry them as a liability and remeasure them each period. When the share price falls, that liability shrinks — and the company books a gain. When the price rises, the reverse. Translated: on paper, the company profits from its own stock going down. For the full year 2025 the same calculation ran the other way and cost $25,280,833; in the fourth quarter of 2025 alone, $30.7 million. That is how the 2025 net loss of $62,963,213 arose even though the operating loss was “only” $42.09 million. In the first quarter of 2026 the effect was a small $1.6 million gain, because the number of warrants carried this way fell from 29.27 million to 493,505. The topic is not closed, though: the 2,292,140 exercisable Lumilens warrants can be exercised cashless, so since May 2026 POET carries them as a liability too. As of June 30, 2026 that put 2,389,836 warrants on the books at $22.0 million, and in the second quarter remeasuring the warrants carried this way produced a $5.53 million book gain — without it, the net loss would have been roughly $16.9 million. Remember: at POET the “net income” line says little about the business. Look at the operating loss and at cash used in operations.
Valuation: what the market is actually paying for
A note on diligence first, because two data sources meet here. We cross-checked the market value in our fundamental data set against the filings, and it passes: 173,058,088 shares per the MD&A of August 13, 2026 at the $7.77 closing price of September 25, 2026 give $1,344.7 million; the fundamental data value of $1.348 billion sits 0.3 percent above that. So we work with roughly $1.34 billion, data as of September 25, 2026. (In the first edition of July 29, 2026 it was $1.17 billion at $6.76 on July 28, 2026.)
Hold that number next to the others in this article:
- 2025 revenue: $1.07 million. The price-to-sales ratio therefore sits at roughly 1,250. Take the last four reported quarters (third quarter of 2025 through second quarter of 2026, $1,712,950 combined) and it is still roughly 785. For comparison: a richly valued software growth stock trades at 15 to 25.
- Book value: roughly $4.90 per share as of June 30, 2026 ($847.5 million of equity over 173.0 million shares, our calculation) — close to the $4.92 at which the prospectus supplement of May 18, 2026 put net tangible book value after the offering. The September 25, 2026 price is therefore roughly 1.6 times book — measured against everything else here, the tamest number in this article, because what stands behind the share is almost entirely cash.
- Hoped-for future annual revenue: more than $100 million from “more than 10 active customer engagements” (statement by the chief executive, June 26, 2026). Even if that arrives in full, it would still imply a price-to-sales ratio around 13 — measured against the September 25, 2026 market value and before any further dilution.
And now the price chain, because it captures the nature of this stock. On January 21, 2026 the prospectus cites $8.37. On March 20, 2026 POET closed at $5.93 according to the annual report. On May 14, 2026 the offering release cites $20.57. On May 15, 2026 — the day the $400 million raise at $21.00 was announced — it was $15.97. At the half-year date, June 30, 2026, the statements themselves use $10.28 (note 21); on July 28, 2026 the stock stood at $6.76, on August 10, 2026 at $8.56 per the results release, and on September 25, 2026 at $7.77. More than tripled in eight weeks, down a fifth in a single day, back to a third of the peak ten weeks later, and swinging between a little over six and just under ten dollars since. That is not a valuation, it is a mood ring. Which is why no price appears in this article without a date beside it: without one, every single figure here would be wrong by tomorrow.
Anyone thinking about valuation should not miss one thing, and it is the strongest sentence in this chapter: most of the market value is the company's own bank balance. In the first edition we still had to estimate it from individual line items; now it is in the statements: $796.3 million of cash and term deposits as of June 30, 2026. Of the roughly $1.34 billion of market value (September 25, 2026), that leaves something like $550 million as the price of the blueprint — for patents, platform, factory plans, the $30 million loan and every hope combined. In July it was roughly $360 million. So the market is paying considerably more for the expectation today than two months ago, even though reported quarterly revenue rose by only $66,536 in between.
Opportunities and risks at a glance
What speaks for POET:
- Funding is secured for years. $796.3 million of cash and term deposits as of June 30, 2026, against $21.1 million of operating cash burn in the first half of 2026. No bank debt, no need for credit lines; the statements consider the funds sufficient for more than a year ahead.
- The market is real and growing. The shift from 400G to 800G and 1.6T in AI data centers is not a forecast but underway; the annual report cites market estimates of $7 billion to $12 billion for high-speed datacom pluggables.
- The technology is patented and externally validated more than once. 81 issued patents per the MD&A as of June 30, 2026, development partnerships with LITEON and Lessengers, the Lumilens supply agreement with an initial $50 million purchase order (May 2026) and, after the quarter, an agreement with a major laser maker.
- Revenue is rising steadily — six quarters in a row, most recently $569,925 in the second quarter of 2026, a little over double the prior-year quarter.
- The accounting has been put in order. The material weakness identified for 2024 is deemed remediated as of December 31, 2025, with an unqualified auditor opinion on internal control.
What speaks against POET:
- Commercial proof is missing. $1.07 million of revenue for all of 2025 and almost as much in the first half of 2026, mostly one-off engineering services; for the rest of 2026 POET promises units for customer qualification, not volume revenue.
- The flagship order is gone — cancelled by Marvell on April 23, 2026, and specifically over an alleged breach of confidentiality by POET itself. The replacement candidate, Lumilens, pays with orders and receives a warrant in return that is likely to weigh on the revenue reported from it.
- Heavy, ongoing dilution. From 76.5 million to 173.1 million shares in a little over nineteen months, potentially 261.4 million counting every warrant and share unit (August 13, 2026) — plus 2.45 million further share units from August 11, 2026.
- The valuation is extreme. Roughly $1.34 billion of market value (September 25, 2026) against $1.71 million of revenue over the last four quarters. Strip out the company's own bank balance of $796.3 million and roughly $550 million remains for platform and patents.
- High side costs, little transparency. $9.43 million of fees to an unnamed financial adviser in the first half of 2026, a $30 million loan to an unnamed borrower, a pending legal action with neither plaintiff nor subject disclosed.
- There are no binding commitments. The MD&A itself states that customers “are typically not contractually committed to buy any quantity of products beyond firm purchase orders” and may cut, delay or cancel existing orders without significant penalty. The April 2026 cancellation demonstrated exactly that.
- Concentration in manufacturing and geography. Assembly in Malaysia, a unit in Shenzhen, development in Singapore — an exposed footprint for a U.S.-listed company serving AI customers.
A human conclusion
Back to the blueprint trap. It does not spring shut because the blueprint is bad — at POET it plainly is not. It springs shut because our minds skip the intermediate step that is in truth the hardest: from working prototype to paid volume product. POET has been working on this base plate under this name since 2013. The balance sheet says the company has now bought itself more time than ever before. The income statement says it still needs that time — the second quarter of 2026 included.
What this analysis does not claim: that the technology does not work. What it documents: that in the second quarter of 2026, too, more than seven times as much money came from interest as from products, that the most important order in company history was cancelled in April 2026 for reasons unrelated to engineering, that the announced redomiciliation was called off again in August 2026, and that roughly $4.90 of book value stands behind each share as of June 30, 2026, almost all of it cash.
If you own POET or want to, there is a handful of numbers to look for in the next interim report (6-K) as of September 30, 2026, and all of them appear in this article. Does the $50 million Lumilens order turn into booked revenue — and does the amortization of the $30.1 million customer consideration begin with it? Does the quarterly figure climb past a little over half a million into the millions? Do the fees to the unnamed financial adviser come down? And does the share count stay at 173.1 million — or climb toward the 261.4 million already embedded in options, warrants and share units?
An expectation is not a lie. It is simply not yet arithmetic. What you make of that is your decision. And that is exactly as it should be.
If you want to see the same examination applied to a company whose technology also convinces while the numbers lag behind, read our analysis of Ouster — the revenue base there is far larger, but the question about earning power is the same.
Sources
- Interim statements as of June 30, 2026 (exhibit 99.1 to the SEC report on Form 6-K of August 13, 2026, accession 0001493152-26-037615) — balance sheet, statement of operations, cash flow statement, notes 2, 3, 11, 12, 13, 18, 20, 21, 22, 23, 24 and 25
- Management’s discussion and analysis (MD&A) as of June 30, 2026 (exhibit 99.2 to the same report) — quarterly summary, financial adviser fees, liquidity, PFIC disclosure, share data as of August 13, 2026
- SEC report 6-K of August 13, 2026 — second quarter 2026 results release, five-quarter summary, share units of August 11, 2026, outlook, redomiciliation dropped
- SEC report 6-K of August 3, 2026 — new directors Dr. Bardia Pezeshki and Jean F. Rankin, resignation of Jean-Louis Malinge
- SEC report 6-K of September 4, 2026 — exhibition at CIOE in Shenzhen (September 9–11, 2026)
- Ownership filing (SCHEDULE 13G/A) by MMCAP International Inc. SPC of August 14, 2026 — 19,155,361 shares, 9.99 percent as of June 30, 2026, entirely underlying warrants; further filings after the half-year statements: Jane Street (August 13, 2026), Group One Trading (August 13 and September 8, 2026), Susquehanna group (August 14, 2026)
- SEC annual report 20-F for 2025, POET Technologies Inc. (CIK 0001437424), filed March 31, 2026 — Item 3.D risk factors, Item 4.B business, Item 5.B liquidity, Item 6.D employees, Item 15 internal control, notes 11, 20, 21, 22
- SEC annual report 20-F for 2024, filed April 1, 2025
- Interim statements as of March 31, 2026 (exhibit 99.1 to the SEC report on Form 6-K of May 15, 2026) — balance sheet, statement of operations, notes 3, 11(b), 14, 21, 22 and 23
- SEC prospectus supplement 424B5 of May 18, 2026 — share count, dilution, net tangible book value, corporate history, foreign private issuer status
- SEC prospectus supplement 424B5 of January 23, 2026 — $150 million offering at $7.25 per share
- SEC report 6-K of April 15, 2026 — PFIC status for 2025 and announced U.S. redomiciliation
- SEC report 6-K of April 27, 2026 — cancellation of all purchase orders by Marvell Semiconductor
- SEC report 6-K of May 14, 2026 — supply agreement with Lumilens Inc., including the warrant on up to 22,921,408 shares at $8.25
- SEC report 6-K of May 15, 2026 — first quarter 2026 results
- SEC free writing prospectus of May 15, 2026 and closing report 6-K of May 18, 2026 — the $400 million offering
- SEC report 6-K of May 18, 2026 (agreement report) — the securities purchase agreement names MMCAP International Inc. SPC as the purchaser in the $400 million offering
- SEC report 6-K of June 30, 2026 — results of the June 26, 2026 annual meeting, share count, capital plans, “up to an additional $661 million” from warrants
- Ownership filings (SCHEDULE 13G) between the interim statements — MMCAP International Inc. SPC of May 20, 2026 (19,047,620 shares, 11.0 percent) and of May 15, 2026 (14,516,820 shares including 13,022,782 underlying warrants, 9.99 percent as of March 31, 2026), plus Marex (May 19, 2026), Jane Street (June 22, 2026) and Citadel Securities (July 8, 2026)
- Fundamental data, company profile and price data of our in-house stock scanner, data as of September 25, 2026 (first edition: July 29, 2026)
Source: fundamental data & SEC filings (annual reports 20-F, interim reports 6-K). POET Technologies reports as a foreign private issuer under U.S. law, on annual Form 20-F and interim Form 6-K; a U.S. quarterly report (Form 10-Q) does not exist for this company — although POET itself considers it likely that it will lose that status; the test is annual, was last due on June 30, 2026, and POET had disclosed no outcome through September 26, 2026. The financial statements are prepared under IFRS Accounting Standards and expressed in U.S. dollars; the fiscal year ends December 31; the interim statements are unaudited. The shares trade only on Nasdaq; the former TSX Venture Exchange listing ended in 2024. POET holds no earnings calls on its quarterly figures, so no transcripts were available.
Important notice
This article is a journalistic assessment of publicly available company disclosures. It is not investment advice, not a research report within the meaning of any securities regulation, and not a solicitation to buy or sell securities. Shares of companies without meaningful revenue can lose their entire value; a total loss is possible. All figures come from the sources named and refer to the dates stated; they may be out of date by the time you read this. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this analysis.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 0.2 | 0.6 | 0.5 | 0.0 | 1.1 |
| Operating Income (EBIT) | -15.7 | -19.7 | -20.4 | -30.1 | -33.9 |
| Net Income | -15.7 | -21.0 | -20.3 | -56.7 | -63.0 |
| Net Margin | -7,493.6% | -3,805.8% | -4,351.3% | -136,857.2% | -5,857.8% |
| Earnings Per Share | -0.45 $ | -0.57 $ | -0.51 $ | -0.94 $ | -0.68 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
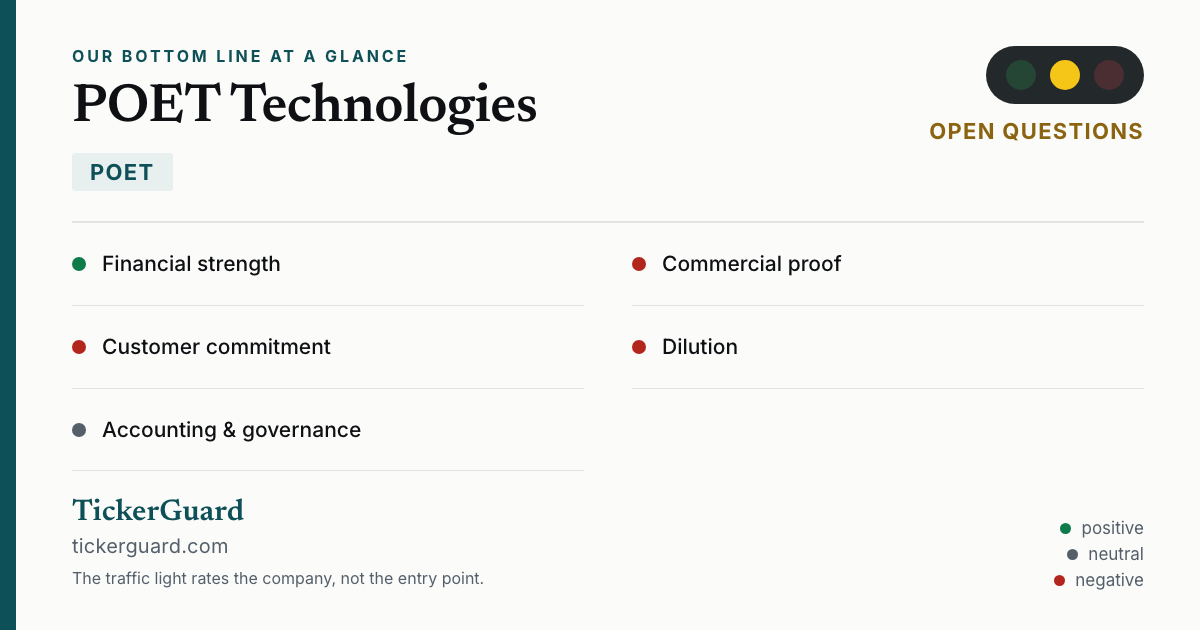
Our Bottom Line at a Glance
- Financial strength positive
- As of June 30, 2026 the company held $796.3 million of liquid assets ($432.5 million of cash plus $363.8 million of guaranteed investment certificates) against $34.3 million of total liabilities, $22.0 million of it the carrying value of warrants. At $21.1 million of operating cash burn in the first half of 2026, funding is secured for years without any bank debt.
- Commercial proof negative
- Revenue came to $569,925 in the second quarter of 2026 and $1,073,314 for the half-year — against a $38.06 million operating loss. It comes mostly from one-off engineering services. For the rest of 2026 POET promises units for customer qualification; the annual report concedes the product “may never gain widespread acceptance by large data center operators”.
- Customer commitment negative
- Marvell Semiconductor cancelled every order from the first production contract, announced in 2023, on April 23, 2026 — alleging that POET had breached its confidentiality obligations. Customers are not committed beyond firm purchase orders. The Lumilens order of $50 million (May 14, 2026) was not discernible as revenue through June 30, 2026, and the warrant granted for it sits on the balance sheet as $30.1 million of customer consideration.
- Dilution negative
- From 76,507,157 shares (January 1, 2025) to 173,058,088 (August 13, 2026), and 261.4 million fully exercised including the Lumilens warrant, plus 2,453,271 share units granted on August 11, 2026. The buyer of the May offering paid $21.00 per share plus warrant; POET itself allocates roughly $14.44 of that to the warrant, and per the filing of August 14, 2026 the buyer held only warrants as of June 30, 2026.
- Accounting & governance neutral
- The material weakness identified for 2024 is deemed remediated as of December 31, 2025, the auditors issued an unqualified opinion and were confirmed with 97 percent of votes on June 26, 2026. Still open: the PFIC status after the redomiciliation was dropped on August 13, 2026, $30 million lent to an unnamed borrower, $9.43 million of fees to an unnamed financial adviser in the first half of 2026, and a pending legal action without party or subject disclosed.
POET Technologies is the blueprint trap in its purest form: a plausible, patented technology for a genuinely growing market — and next to it an income statement in which $569,925 of quarterly revenue (second quarter of 2026) meets a $20.19 million operating loss. The balance sheet is exceptional, with $796.3 million of liquid assets (June 30, 2026), and it was paid for by more than doubling the share count to 173.1 million. The most important order in company history was cancelled in April 2026 because the customer accuses POET of breaching confidentiality; the redomiciliation meant to end the PFIC classification has been off the table since August 2026. Anyone buying in buys time and an expectation — both available in abundance, just not yet sold. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
Yellow here marks an open operating question, not a substance risk — and the second quarter of 2026 did not change that: the balance sheet is sound — $796.3 million of liquid assets against $34.3 million of liabilities (June 30, 2026), no need for credit lines, no going-concern paragraph in the statements, and the 2024 control weakness remediated and attested. What is still missing is proof that anyone buys this technology in volume: $569,925 of quarterly revenue, mostly one-off engineering work, the first production order in company history cancelled in April 2026, the Lumilens order without discernible revenue so far. That the stock trades at roughly 785 times revenue over the last four quarters (market value $1.34 billion, data as of September 25, 2026) is a price argument and does not move the light — it only changes how little room for disappointment remains. This turns green once two or three consecutive quarters show announcements becoming shipments. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- This analysis did not start from a scanner hit — POET appeared in none of our scanner lists as of July 29, 2026 — but from the SEC filing stream: the report of April 27, 2026 on the cancellation of all Marvell purchase orders on April 23, 2026 and the $400 million offering of May 15/18, 2026. Updated on September 26, 2026 to the half-year figures of August 13, 2026.
- Data basis: annual figures from the 20-F for 2025 (December 31, 2025), interim figures from the half-year statements as of June 30, 2026, share count from the MD&A as of August 13, 2026. Prices and market value: closing level of September 25, 2026 from our price database.
- The market value was checked against the filings and passed: 173,058,088 shares (MD&A, 08/13/2026) × $7.77 closing price of 09/25/2026 give $1,344.7 million; the fundamental data value of $1.348 billion is 0.3 percent higher. Prices from our price database match two filing dates to the cent: $10.28 on 06/30/2026 (note 21 of the half-year statements) and $8.56 on 08/10/2026 (results release).
- POET held no earnings call on the quarterly figures; the results release of 08/13/2026 names none and no transcript exists. We worked through the statements, the MD&A and the results release instead.
- Easy to confuse: POET Technologies is a Canadian corporation reporting as a foreign private issuer (20-F, 6-K). No U.S. quarterly report (10-Q) exists; anyone searching for one finds nothing and wrongly concludes the company is opaque. Its former SEC name is OPEL International Inc. Second trap: older press releases still carry “TSX Venture: PTK” in the header — per the 20-F for 2025 the Canadian listing already ended in 2024, and the shares trade only on Nasdaq.
- Pitfall on book value: the $2.94 per share in the prospectus supplement of 05/18/2026 is expressly the “historical” figure as of 03/31/2026, before the $400 million offering. After the offering the prospectus gives $4.92; the half-year statements work out to roughly $4.90 of equity per share as of 06/30/2026 (our calculation). The article therefore works with roughly $4.90.
- Dilution pitfall: the prospectus supplement of 05/18/2026 did not include the Lumilens warrant on up to 22,921,408 shares; the half-year statements list it in note 12. The MD&A as of 08/13/2026 shows 4,252,504 share units — the 2,453,271 units approved on 08/11/2026 cannot be fully included in that figure. The article therefore gives 261.4 million fully diluted and up to 263.9 million including those units.
- The whole price chain — $8.37 (January 21, 2026), $5.93 (March 20, 2026), $20.57 (May 14, 2026), $15.97 (May 15, 2026), $10.28 (June 30, 2026), $6.76 (July 28, 2026), $8.56 (August 10, 2026), $7.77 (September 25, 2026) — is dated and documented; it appears in the article as evidence of how the price forms, not as a price forecast.
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of October 3, 2026. Stock Watch will tell you what's changed at POET since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for POET Technologies Inc (POET), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
POET Technologies Inc. (Nasdaq: POET) of Toronto develops the “Optical Interposer” — a base plate on which the photonic and electronic parts of optical transceivers are assembled at wafer level instead of one by one by hand. On top of it sit optical engines for 800G and 1.6T plus the POET Blazar light source line, both aimed at AI data centers. Development happens in Singapore and assembly in Malaysia; the company had 80 full-time employees as of December 31, 2025.
Very little. The annual report on Form 20-F shows revenue of $1,074,865 for 2025, after $41,427 in 2024 and $465,777 in 2023. The second quarter of 2026 brought $569,925, after $503,389 in the first quarter; the first half of 2026 came to $1,073,314 combined. Against that stood a $38.06 million operating loss for the half-year, and other income including interest, at $8.27 million, was almost eight times revenue. Revenue comes mostly from one-off engineering services, not from volume shipments.
Because POET Technologies is a Canadian corporation and is treated by the U.S. securities regulator, the SEC, as a foreign private issuer. Such companies file an annual report on Form 20-F and ongoing interim reports on Form 6-K instead of U.S. quarterly reports on Form 10-Q — the half-year figures as of June 30, 2026 arrived that way on August 13, 2026. The financial statements follow IFRS Accounting Standards and are expressed in U.S. dollars; the fiscal year ends December 31. The 2025 annual report carries the loss of this status as a risk factor of its own (“The Company will likely lose its foreign private issuer status”), and the annual test date was June 30, 2026; nothing had been disclosed on the outcome through September 26, 2026. The planned U.S. redomiciliation, which would also have ended the status, was dropped on August 13, 2026.
It was cancelled. Marvell Semiconductor, which had acquired Celestial AI, gave written notice on April 23, 2026 cancelling every purchase order — including the first production units POET announced on April 25, 2023. Per the SEC report of April 27, 2026, Marvell stated that POET had disclosed information about the order and shipments in contravention of its confidentiality obligations. The same report points to a previously disclosed order of roughly $5 million with another company; it is not a replacement for the cancelled volume. The $50 million Lumilens order of May 2026 was not yet discernible as revenue through June 30, 2026.
Heavily. Shares outstanding rose from 76,507,157 (January 1, 2025) to 132,021,526 (December 31, 2025), 152,893,604 (March 31, 2026) and 173,058,088 on August 13, 2026. Adding the 78,734,968 warrants — including the Lumilens warrant on up to 22,921,408 shares —, 5,369,393 options and 4,252,504 share units gives 261.4 million shares, roughly 51 percent more. On August 11, 2026 a further 2,453,271 share units for officers were added. That funded $830 million of equity raised in twelve months.
As of June 30, 2026 the half-year statements show $432,531,904 in cash plus $363,809,999 in short-term investments (Canadian guaranteed investment certificates) — $796.3 million together. On top come a $30 million loan to an unnamed borrower (carrying value $30.6 million) and a 4.99 percent stake in Lessengers Inc. Total liabilities were only $34.3 million, $22.0 million of it the carrying value of warrants; the company states it maintains no credit facilities.
PFIC stands for Passive Foreign Investment Company — a U.S. tax classification for foreign corporations whose income or assets are predominantly passive. POET disclosed on April 14, 2026 that it will be treated as a PFIC for 2025: $4.55 million of other income including interest against $1.07 million of revenue. U.S. holders can mitigate the consequences with a timely QEF election, for which the company has committed to provide the required statements. The U.S. redomiciliation announced in April to end the issue was dropped by the board on August 13, 2026; since then POET says it may continue to be classified as a PFIC for 2026 and possibly beyond. The first half of 2026 brought $8.27 million of interest and other income against $1.07 million of revenue.
As of September 25, 2026 the market value stood at roughly $1.34 billion — 173.06 million shares at a closing price of $7.77. Against $1.07 million of 2025 revenue that implies a price-to-sales ratio of about 1,250, against the last four quarters ($1.71 million) about 785. Book value was roughly $4.90 per share as of June 30, 2026 (our calculation). Strip out the company's own liquid assets of $796.3 million and the market is paying about $550 million for the platform, the patents and the prospects.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.