Opendoor Is Buying Homes Again — and Its Own Shares With Borrowed Money
First Opendoor paid its people in stock, now it is buying stock back on credit: $158 million in August at $3.49 a share, paid for with a note due in 2030. Six weeks later the stock stood at $2.44. Updated October 3, 2026 with the second-quarter numbers. Not investment advice — just the question of who ends up owning this house.
 Thomas Mücke
Founder & Publisher
As of Today
As of: October 30, 2026
- Closing price
- 1.80 $ -5.30%
- Market Capitalisation
- 1.7 $B
- Growth Score
- 3/10
- AAQS
- 5/10
Price change since October 2, 2026: -26.2%
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
52-week range: 1.90 $ to 9.40 $ · Last price: 1.80 $ (As of: October 30, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
There is a mental trap almost every investor falls into, and it has an innocent name: the “it doesn’t cost anything” trap. It springs shut whenever a company pays its people in shares rather than in cash. No dollar leaves the bank account, no cent is missing from the till — so, the feeling goes, it costs nothing. Picture instead a homeowner who pays the contractors not in money but in rooms. The house still stands exactly as it did. He simply no longer owns all of it. That is precisely the arithmetic at Opendoor Technologies (NASDAQ: OPEN) — a company whose entire business happens to consist of houses. So let us make a deal: we will read together what Opendoor itself told the U.S. securities regulator, the SEC — the annual report (10-K) for 2025, the quarterly reports (10-Q) as of March 31 and June 30, 2026, and everything filed since. Those documents are filed under penalty of law — anyone who puts false statements in them is liable for it — and they answer the question of who ends up owning this house.
Update October 2026: What the Second Quarter Shows
Status of this update: October 3, 2026. The chapters on the uncomfortable truths further down carry the first-quarter status; where a figure has changed since, the new value is given alongside. Valuation, opportunities and risks, conclusion and fact sheet have been brought up to date.
Buying is back, selling is not yet — and the share count is falling, at least by arithmetic. Since our first edition of July 27, 2026, Opendoor has filed its quarterly report (10-Q) as of June 30, 2026; on the same day, August 4, 2026, an earnings press release with guidance as an exhibit to a current report (8-K, Items 2.02, 7.01 and 9.01); and in August two more current reports (8-Ks of August 13 and 19, 2026) on a refinancing that goes straight to the central tension of this analysis. Over the same period the stock fell from $3.84 (close July 24, 2026) to $2.44 (close October 2, 2026), or roughly 36 percent.
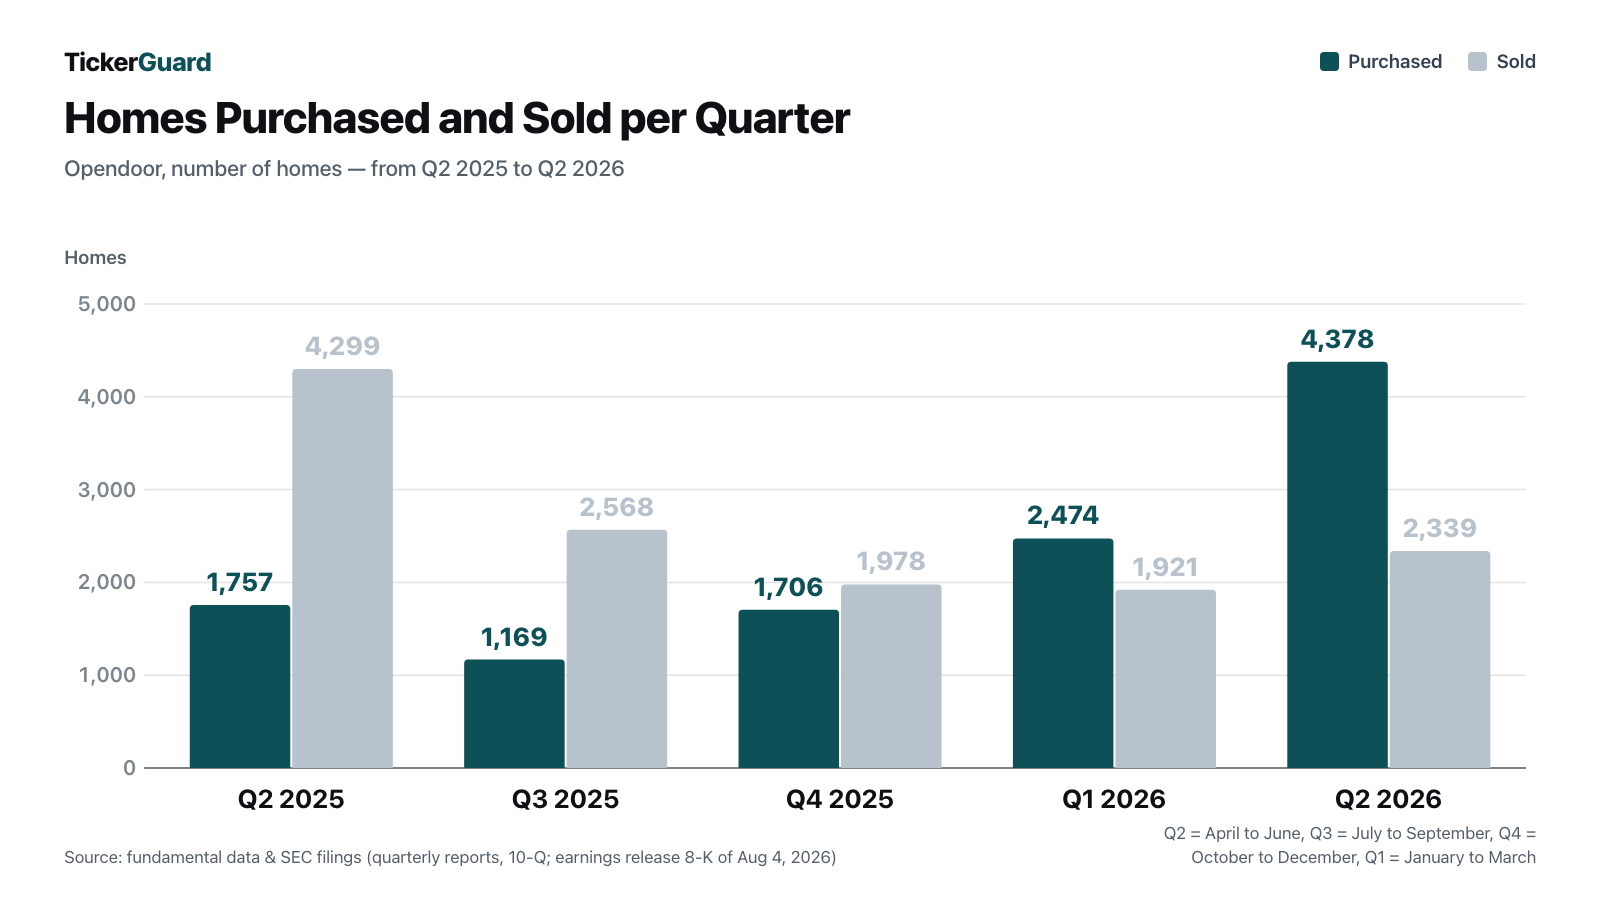
The numbers: in the second quarter of 2026 Opendoor bought 4,378 homes — 77 percent more than in the first quarter and 149 percent more than a year earlier (1,757). As of June 30 another 2,310 homes were under contract to purchase, against 393 a year earlier. Sales, by contrast, came to just 2,339 homes after 4,299 in the prior-year quarter. Because Opendoor buys first and sells months later, revenue lags purchasing: $883 million, up 23 percent on the first quarter but down 44 percent on the prior-year quarter ($1,567 million). Inventory grew from 3,420 to 5,459 homes carried at $1,845 million. The inventory stayed healthy: only 9 percent of listed homes had been on the market longer than 120 days, and gross margin was 9.7 percent after 8.2 percent a year earlier.
The loss: net loss for the second quarter was $162 million after $29 million a year earlier; the first half came to $335 million (prior year: $114 million). The largest single item is again stock-based compensation: $119 million in the quarter, $100 million of it for the price-linked awards. The company’s adjusted measure (adjusted EBITDA) was minus $4 million after plus $23 million a year earlier, and contribution profit was $51 million, or 5.8 percent of revenue. And the sentence at the heart of Uncomfortable Truth No. 1 appears in the new report too — with a new date:
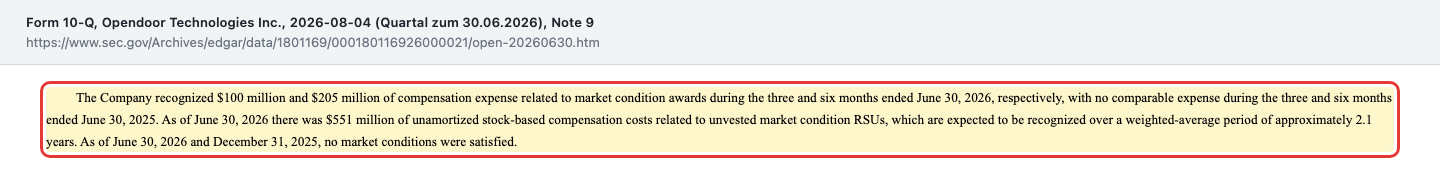
“As of June 30, 2026 there was $551 million of unamortized stock-based compensation costs related to unvested market condition RSUs, which are expected to be recognized over a weighted-average period of approximately 2.1 years. As of June 30, 2026 and December 31, 2025, no market conditions were satisfied.”
— Opendoor Technologies Inc., SEC quarterly report on Form 10-Q as of June 30, 2026, Note 9 “Share-Based Awards”
The CEO’s promise: in the earnings press release of August 4, 2026, chief executive Kaz Nejatian commits himself: by the end of 2026 Opendoor will reach break-even on adjusted net income, measured on a twelve-month go-forward basis. In his words: “You no longer have to take my word for it. Run Q2 forward.” For the third quarter of 2026 the company guides to revenue at least 20 percent above the prior-year quarter (then $915 million), contribution profit more than doubling at a 4 to 4.5 percent margin, noticeably below the 5.8 percent of the second quarter — and roughly $110 million of stock-based compensation. That is the catch you should know about: adjusted net income excludes stock-based compensation. If it sits at zero while stock compensation runs at $110 million, U.S. GAAP still shows, by arithmetic, a quarterly loss in the order of $110 million. The earnings call took place as a webcast on August 4, 2026; a complete transcript was not available to us verbatim, so we rely on the press release and cannot judge whether the tone shifted from the May call.
The August refinancing: on August 12, 2026 Opendoor agreed a new convertible note of $650 million — no coupon, due August 15, 2030, closed on August 19, 2026. From the proceeds the company bought back its own stock on August 17, 2026 for roughly $158 million — about 45.3 million shares at $3.49 according to the company. Per the press release of August 13, 2026 it is the “first share repurchase in the Company's history as a public company.” At the October 2, 2026 close of $2.44, the repurchased shares are worth only about $110 million on paper. A further $52.5 million went into a hedge against dilution, a so-called capped call. Per the company, roughly $440 million remains, before transaction expenses, to expand home inventory.
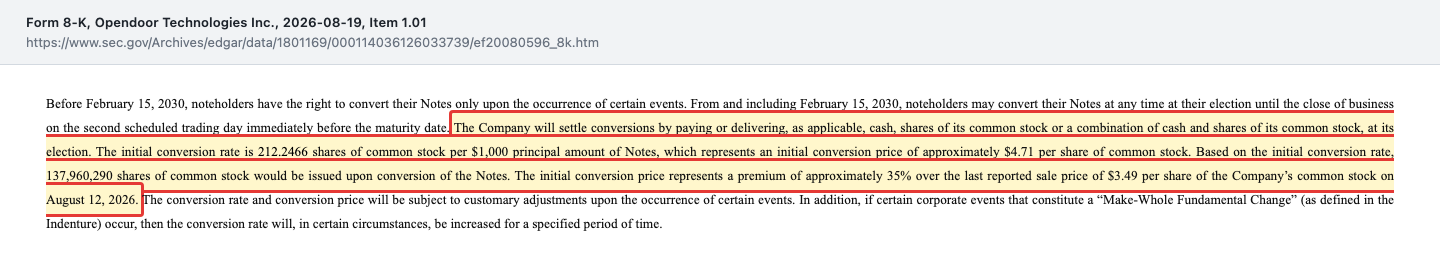
“The Company will settle conversions by paying or delivering, as applicable, cash, shares of its common stock or a combination of cash and shares of its common stock, at its election. The initial conversion rate is 212.2466 shares of common stock per $1,000 principal amount of Notes, which represents an initial conversion price of approximately $4.71 per share of common stock. Based on the initial conversion rate, 137,960,290 shares of common stock would be issued upon conversion of the Notes. The initial conversion price represents a premium of approximately 35% over the last reported sale price of $3.49 per share of the Company’s common stock on August 12, 2026.”
— Opendoor Technologies Inc., SEC current report on Form 8-K of August 19, 2026, Item 1.01
What does that mean for the question of who owns the house? Subtracting the roughly 45.3 million repurchased shares from the 971,091,050 outstanding on July 28, 2026 per the quarterly report cover page gives about 926 million shares by arithmetic — roughly 4.7 percent fewer. The exact post-buyback figure will only appear in the next quarterly report. At the same time the queue has grown: 261.5 million potential shares stood in the dilution table as of June 30, 2026, and up to 137.96 million from the new note now come on top. If all of it became stock, that would be just under 400 million by arithmetic. Roughly a quarter of that has an expiry date, though: the 99.3 million warrants lapse on November 20, 2026, and their lowest exercise price of $9 is 3.7 times the October 2, 2026 close. Unless the stock rises accordingly by then, they expire worthless and leave the queue. The 137.96 million shares from the note, however, hinge on a condition Opendoor itself sets differently: the company intends to pay the principal in cash on conversion and deliver shares only for the value above $4.71; per the company, the capped call covers dilution up to $6.98, and above that the repurchased shares are meant to offset it up to about $10.38. The flip side of that arithmetic: the $650 million principal then falls due in cash in 2030.
The cash: the inventory build costs money. Operating activities consumed $964 million in the first half of 2026, after generating $544 million a year earlier. Unrestricted cash fell to $896 million by June 30, while inventory financing rose to roughly $1.8 billion. And the report contains a subordinate clause that matters more than it sounds:
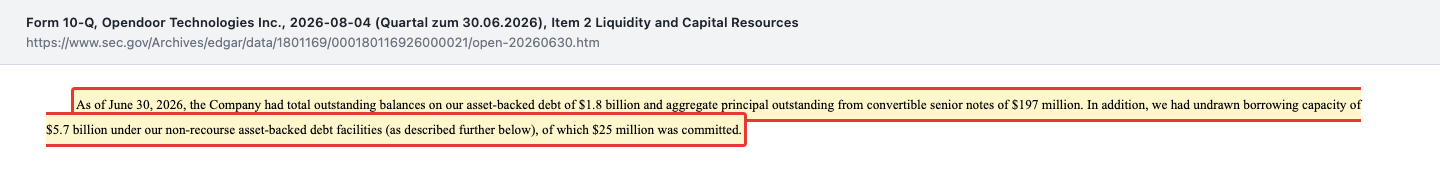
That is not a sign of crisis — all financial covenants were met per the filing, and management considers its resources sufficient for at least twelve months. But it explains why the new note came: a company that wants to buy twice as many homes needs its own money for the part the banks will not finance. Also open is the old $135 million convertible note that matured on August 15, 2026; whether it was repaid in cash will only show in the quarterly report as of September 30, 2026 — there is no current report on an extension or conversion. A small signal on the side: on August 14, 2026 Nejatian bought 27,625 shares at an average of $3.62, about $100,000 worth, per his insider filing (Form 4). Bottom line: the tension of “the business shrinks, the share count grows” flipped in the summer of 2026 — buying is growing and the share count is falling. Both are paid for with new debt and a promise of profitability that leaves stock-based compensation out.
Company history for investors
-
2013
Opendoor incorporated
Opendoor is incorporated in Delaware on December 30, 2013 as a middleman for residential homes (iBuying).
-
2020
IPO via SPAC merger
On December 18, 2020 Opendoor reaches Nasdaq through special purpose vehicle Social Capital Hedosophia Holdings Corp. II.
-
2026
In-house mortgage license
Since February 2026 subsidiary Opendoor Home Loans LLC holds its own mortgage license, expanding adjacent services.
-
2026
First share buyback, new convertible
In August 2026 Opendoor issues a $650 million zero-coupon convertible note and uses part of it to repurchase about 45.3 million of its own shares — per the company its first since going public.
What Opendoor Actually Does
Opendoor is a middleman for residential homes. A seller enters an address online and receives a binding offer within a short time — not from an agent looking for a buyer, but from Opendoor itself. The company buys the home on its own balance sheet, has repairs carried out, presents it empty and tidy, and resells it. The industry term is iBuying. In everyday terms: Opendoor is to a house what a used-car dealer is to a car — except that a single home in inventory tied up roughly $333,000 on average as of March 31, 2026 ($1,139 million of carrying value across 3,420 homes).
Money is made in three places: a service fee, the spread between purchase and resale price, and increasingly adjacent services. Those adjacent services have included title insurance, escrow and a brokerage license for years; in the first quarter of 2026 the company added its own mortgage product through subsidiary Opendoor Home Loans LLC, licensed since February 2026. At the end of 2025 Opendoor widened its buying footprint from 50 individual markets to effectively the entire contiguous United States. Since inception — the entity was incorporated in Delaware on December 30, 2013 — it reports more than 305,000 transactions (as of the quarterly report for June 30, 2026). On July 20, 2026 Opendoor acquired parts of a closing and escrow business for $10 million. As of December 31, 2025 it employed 1,042 people, 858 of them in the United States.
One detail from the company history matters because it still shapes the numbers: Opendoor did not reach Nasdaq through a conventional initial public offering but on December 18, 2020 through a special purpose acquisition company — a listed shell named Social Capital Hedosophia Holdings Corp. II, which renamed itself Opendoor Technologies Inc. on completion. Structures like that typically leave warrants and generous equity plans behind; both are still on Opendoor’s balance sheet today.
Which brings the central tension of this analysis into the open, and it runs through every chapter: the business is shrinking while the share count grows. In the first half of 2026 Opendoor sold markedly fewer homes than a year earlier — and markedly more shares divided up the result. In the summer of 2026 both lines flipped, paid for with new debt; how is set out in the update chapter above.
How the Stock Reached Our Desk
Opendoor did not come to us through a quality filter but through attention: the ticker landed on our research list on July 27, 2026 via our screen of Reddit mentions. That is an attention signal, not a quality verdict — it says a lot of people are talking about the stock, and nothing else. Where the stock stands in the lists of our in-house stock scanner changes daily, because those lists are recomputed every night; a snapshot would already be stale tomorrow.
Why so many people talk about Opendoor can be read off a single dated range: between the 52-week low of $1.70 and the 52-week high of $10.87 lies a factor of six (data as of July 24, 2026). On the same date the closing price was $3.84 — roughly 65 percent below the high and more than double the low. A second figure from the same source fits the picture: short interest stood at roughly 19.6 percent of the float, and the volatility measure beta at 3.56, meaning the stock moves on average more than three times as much as the broad market. Translated: two very determined camps face each other here, and the price is correspondingly jumpy.
Note the finding up front: at TickerGuard, Opendoor is not a fundamental find but an attention find. Which makes what the filings say all the more important.
The Numbers Over the Years — Given Their Due
First the part that genuinely impresses, and it is not small. Over the past three years Opendoor has managed something many capital-intensive dealers fail at: it brought its inventory under control without running into a liquidity squeeze. The share of homes listed for more than 120 days fell from 27 percent to 10 percent within a year (March 31 in each case). Gross margin rose over the same period from 8.6 percent to 10.0 percent. As of March 31, 2026 the company held $999 million in unrestricted cash, $37 million more than at year-end 2025, and shareholders’ equity was positive at $954 million. All lender covenants were met, per the filing. For a dealer that ties up virtually all of its capital in inventory, that is a real achievement.
On the revenue and earnings side, however, the picture is different.

The chart covers three fiscal years, each ending December 31. 2023: revenue of $6,946 million, a net loss of $275 million. 2024: revenue of $5,153 million, a loss of $392 million. 2025: revenue of $4,371 million and a loss of $1,300 million. Revenue has fallen 37 percent in two years. There is a comprehensible external reason, and the company names it: the U.S. housing market is on the floor. Existing home sales are running at an annualized rate of roughly four million units — per the filing a 30-year low and about 20 percent below the pre-pandemic decade average. Mortgage rates fell to about 6.2 percent in November, briefly dipped below 6 percent in late February 2026 and were back in the mid-6 percent range by quarter-end.
The decline continued in the first quarter of 2026: $720 million in revenue against $1,153 million a year earlier, down $433 million or 38 percent. The company sold 1,921 homes instead of 2,946 and bought 2,474 instead of 3,609. Inventory fell from 7,080 to 3,420 homes and from $2,362 million to $1,139 million in carrying value. One thing matters for the reading: part of this is deliberate. Opendoor kept its purchase spreads wide through 2025 to keep poor risks out of inventory — and a company that offers less buys less, and a company that buys less later sells less. In the second quarter of 2026 buying reversed (4,378 homes purchased), but revenue of $883 million was still 44 percent below the prior-year quarter — the details are in the update chapter above.
What the Filings Say — The Uncomfortable Truths
Uncomfortable Truth No. 1: The Loss Doubled in the First Quarter — The Business Barely Moved
Net loss rose from $85 million to $173 million in the first quarter of 2026. That sounds like a dramatic deterioration. Alongside it the company reports its own adjusted measure, adjusted EBITDA — loosely, “operating result before interest, taxes, depreciation and everything management considers one-off”. That figure came in at minus $31 million, against minus $30 million a year earlier. Practically unchanged.
Between minus $173 million and minus $31 million lies a gap of $142 million. Its largest component sits one line higher in the income statement: general and administrative expenses jumped from $33 million to $137 million. And the notes explain why: stock-based compensation rose from $14 million to $120 million, $110 million of it inside general and administrative.
“The Company recognized $105 million of compensation expense related to market condition awards during the three months ended March 31, 2026, with no comparable expense during the three months ended March 31, 2025. As of March 31, 2026 there was $654 million of unamortized stock-based compensation costs related to unvested market condition RSUs, which are expected to be recognized over a weighted-average period of approximately 2.3 years. As of March 31, 2026 and December 31, 2025, no market conditions were satisfied.”
— Opendoor Technologies Inc., SEC quarterly report on Form 10-Q as of March 31, 2026, Note 9 “Share-Based Awards”

Read the last sentence again: “no market conditions were satisfied”. These are share awards that only vest once the stock price clears defined hurdles. Those hurdles had not been cleared as of the reporting date. Expense arises anyway, and a great deal of it: under U.S. accounting rules the grant-date value of such awards is spread over the expected service period regardless of whether the price ever reaches the hurdle. That is technically correct and, for a reader, thoroughly confusing.
So the decisive question is not “is that real money?” but “whose money is it?”. And there is a clear answer: it is the money of existing shareholders, paid not out of the till but out of their stake in the company. Rule of thumb: stock-based compensation costs no cash — it costs percentage points of the house.
Uncomfortable Truth No. 2: The Queue Behind the Share Is Almost Five Times Longer Than a Year Ago
Every quarterly report contains an unremarkable table titled “anti-dilutive securities”. It lists everything that could one day become a new share but is not yet counted in loss per share — because including it would arithmetically improve rather than worsen the result. At Opendoor this may be the single most important page in the whole filing.

The total rose within a year from 54.7 million to 267.4 million shares — almost five times. Measured against the 963,283,777 shares outstanding on March 31, 2026, that is 27.8 percent. Put differently: if everything in that table one day becomes stock, today’s shareholder owns a little over three quarters of what he owns today. As of June 30, 2026 the total stood at 261.5 million shares (56.5 million a year earlier), 27.0 percent of the 968,626,958 shares then outstanding — and since August up to 137.96 million from the new convertible note come on top (see the update chapter).

And that is on top of what has already happened. Shares outstanding rose from 726,835,454 on March 31, 2025 to 963,283,777 on March 31, 2026 — up 32.5 percent in twelve months. By June 30, 2026 the count had risen to 968,626,958, and per the quarterly report cover page to roughly 971,091,050 as of July 28, 2026. Only the share repurchase of August 17, 2026 pushed it down, by arithmetic, to about 926 million. The charter authorizes three billion shares. The runway is far from used up.
Picture it once more as a house: the rent this house earns — revenue — was 38 percent below the prior-year quarter in the first quarter of 2026. The number of co-owners had risen by a third in the twelve months to March 31, 2026, and another 27.8 percent were waiting at the door (in the second quarter: revenue down 44 percent, queue at 27.0 percent). How another digital middleman with a similar business model fared is shown in our analysis of Vroom, the online car dealer.
Uncomfortable Truth No. 3: The Billion-Dollar Loss of 2025 Was the Price of One Convertible Bond
Reading the $1.3 billion loss for 2025 as an operating disaster gets it wrong — and so does waving it away. It arose differently than one might expect. Loss from operations in 2025 was $287 million, in fact slightly better than the $320 million of 2024. The billion came from a single transaction in November 2025.
“In November 2025, the Company entered into share purchase agreements with a limited number of purchasers (together, the “Purchasers”), providing for the issuance and sale by the Company of an aggregate of 180,580,200 shares of common stock at a price of $6.56 per share (the “Registered Direct Offering”). Concurrent with the Registered Direct Offering, the Company entered into separate, privately negotiated transactions with the Purchasers, pursuant to which the Company agreed to repurchase an aggregate of approximately $264 million principal amount of the 2030 Notes for an aggregate repurchase price of approximately $1.2 billion […] and (iv) recorded $933 million of loss on debt extinguishment.”
— Opendoor Technologies Inc., SEC annual report on Form 10-K for 2025, Note 8 “Convertible Senior Notes”

What had happened? In May 2025 Opendoor had issued new convertible notes carrying 7.00 percent interest and maturing in 2030. Their conversion price was $1.57 — a figure that says on its own how low the stock stood in May 2025. Then the price rose. $264 million of that note’s principal thereby turned into a claim on a very large number of shares, suddenly worth roughly $1.2 billion to its holders. Opendoor resolved it by selling shares to those same investors and using the proceeds to buy their notes back. On a net basis the company received nothing from either leg — the filing says so explicitly: “On a net basis, the Company did not receive any proceeds from these transactions.”
The fair counterpoint: the swap served a real purpose. Left alone, the convertible would have produced even greater dilution over the years and cost 7 percent interest along the way. Only $62 million of the original principal was still outstanding as of June 30, 2026; because the stock traded above 130 percent of the conversion price, holders could convert that remainder at any time through September 30, 2026, per the quarterly report. But the $933 million is not an accounting artifact to be subtracted and forgotten: it is the price existing shareholders paid because the noteholders had come in very cheaply. Rule of thumb: a convertible issued at the bottom is never cheap money — the bill arrives later and is settled in shares.
Uncomfortable Truth No. 4: 99.3 Million Free Warrants Are Running Toward a Fixed Date
In November 2025 Opendoor did something rarely seen on Nasdaq: on November 6 the board declared a dividend in the form of warrants. Every holder of record on November 18, 2025 received three warrants for each 30 shares held: Series K at an exercise price of $9.00, Series A at $13.00 and Series Z at $17.00. On November 21, 2025, 99,295,146 were issued, and since November 24 they have traded under OPENW, OPENL and OPENZ. Shareholders paid nothing for them.

A warrant is a bet on a given price by a given day. Here the day is November 20, 2026, 5:00 p.m. New York City time. As of March 31, 2026, 99,288,814 warrants were outstanding: 33,093,428 of Series K, 33,097,679 of Series A and 33,097,707 of Series Z; by June 30, 2026 the figure was 99,288,090. The closing price of the stock was $3.84 on July 24, 2026 and $2.44 on October 2, 2026 — well below all three exercise prices. There is an early expiration clause, but it only works to the upside: if the volume-weighted average price reaches at least 120 percent of an exercise price on 20 out of 30 consecutive trading days — roughly $10.80 for Series K — the term ends immediately.
For investors that is an uncomfortable but clean piece of arithmetic. If the price rises sharply, the warrants turn into up to 99.3 million new shares and the rise is spread across more heads. If it does not, the warrants expire on a fixed date. At the October 2, 2026 close of $2.44, the stock would have to almost quadruple by November 20, 2026 for even the $9 Series K to be in the money. Either outcome is clear — just not neutral.
Valuation — What the Market Is Charging for This House
Let us work it through in orders of magnitude and with explicit dates. As of October 2, 2026 the market capitalization stood at roughly $2.26 billion — calculated on about 926 million shares (971,091,050 per the quarterly report cover page of July 28, 2026, less the roughly 45.3 million shares repurchased in August) at a closing price of $2.44. At our first edition, as of July 24, 2026, it was about $3.70 billion. Against that:
- Trailing twelve-month revenue (Q3 2025 through Q2 2026): $3,254 million. That puts the price-to-sales ratio near 0.69 — low at first glance. But Opendoor is not a software house, it is a dealer: just under 10 cents of gross profit remain from each revenue dollar. Measured against trailing gross profit of $281 million, the market is paying about eight times.
- Shareholders’ equity as of June 30, 2026: $914 million, or $0.94 per share. The market capitalization equals roughly 2.5 times book value. The August buyback and capped call are not yet reflected in that figure.
- Net current asset value (current assets less all liabilities): $803 million as of June 30, 2026, down from $847 million a quarter earlier. The market capitalization is about 2.8 times that asset backing.
- No price-to-earnings ratio, because there are no earnings. The accumulated deficit stood at $5,368 million as of June 30, 2026 — almost six times equity.
The professionals remain reserved: of nine analysts tracked, 2 rate the stock a buy, 5 a hold and 2 a sell, with an average price target of about $4.27 (data as of October 3, 2026). Short interest rose to roughly 24.7 percent of the float, and the 52-week range runs from $2.25 to $9.69. For a sense of how hard the environment is for anything tied to home finance, see our analysis of Rocket Companies, by its own account the largest mortgage originator in the United States.
Opportunities and Risks at a Glance
What speaks for Opendoor
- Buying is back. 4,378 homes purchased in the second quarter of 2026 after 1,757 a year earlier, plus 2,310 homes under contract as of June 30. For the third quarter the company guides to revenue at least 20 percent above the prior-year quarter.
- Inventory is markedly healthier than a year ago. Only 9 percent of homes had been listed longer than 120 days as of June 30, 2026 (36 percent a year earlier), and gross margin in the second quarter was 9.7 percent after 8.2 percent.
- The home financing is non-recourse. The roughly $1.8 billion of inventory financing sits in dedicated special purpose entities whose creditors generally have no claim on the rest of the group. All financial covenants were met per the filing.
- Fresh money with no coupon. Of the $650 million August 2026 convertible, roughly $440 million remains net before expenses after the buyback ($158 million) and the capped call ($52.5 million), per the company; the note carries no interest through 2030, and dilution is hedged up to $6.98.
- The market is on the floor — not the company alone. Roughly four million existing home sales a year is, per the annual report, a 30-year low. If rates turn, volumes turn. The in-house mortgage product is meant to lift the margin per home along the way.
What speaks against it
- Revenue still lags. $883 million in the second quarter of 2026, 44 percent below a year earlier. Over three years annual revenue fell from $6,946 million to $4,371 million.
- The inventory build burns cash. $964 million of operating cash outflow in the first half of 2026; only $25 million of committed inventory credit lines remained undrawn as of June 30.
- Stock-based compensation remains the largest cost block. $119 million in the second quarter, roughly $110 million guided for the third, $551 million not yet recognized — for awards whose price conditions were entirely unmet as of June 30, 2026.
- The queue behind the stock stays long. 261.5 million potential shares as of June 30, 2026, plus up to 137.96 million from the new note — and $650 million of principal due in cash in 2030 if Opendoor settles conversions in cash as announced.
- Expensive debt on the balance sheet. The $350 million of mezzanine inventory financing carries 12.50 percent interest. Group interest expense in the second quarter of 2026 was $29 million.
- One business, one market — and split shareholders. Opendoor is fully exposed to U.S. residential real estate. At the annual meeting on June 11, 2026 roughly 41 percent voted against executive compensation; short interest stood at about 24.7 percent of the float on October 3, 2026.
A Human Conclusion
Remember the “it doesn’t cost anything” trap from the opening? The homeowner paying his contractors in rooms? In the summer of 2026 Opendoor did something that at first glance looks like the opposite: the company bought rooms back — roughly 45.3 million shares. But look closely at what with: borrowed money that has to be repaid in 2030. And in the first half of 2026, $239 million of stock-based compensation went out without a cent leaving the till. The “it doesn’t cost anything” trap now has a sibling: the bill that only arrives in 2030.
At the same time it would be unfair to turn this into a pure story of decline. This company cleaned up its inventory, held its margin, met its covenants and is buying at scale again — in a market sitting at a 30-year low. Management has committed to a date: by the end of 2026 it wants to reach break-even on adjusted earnings.
What follows is not a recommendation but a question only you can answer: do you trust a dealer that is buying homes and its own stock with borrowed money — and whose profit promise leaves out its largest cost line? Saying yes is a bet that the 4,378 homes bought will be sold at a margin, rates fall and the stock rises well above the conversion thresholds by 2030. Saying no points to $964 million of cash outflow in a half-year, $551 million of compensation not yet recognized and a note that has to be paid either way — in cash or in shares.
If you want to watch just three numbers in the coming filings, watch these: the number of homes sold (last reported 2,339 in the second quarter of 2026, after 4,299 a year earlier), the share count on the cover page of the quarterly report (last reported 971,091,050 as of July 28, 2026, before the buyback) and the committed, undrawn credit capacity (last reported $25 million as of June 30, 2026). If those three move in the right direction, the whole story changes. What you make of it is your decision. And that is exactly as it should be.
Sources
- Opendoor Technologies Inc. — annual report on Form 10-K for fiscal year 2025, filed February 19, 2026
- Opendoor Technologies Inc. — quarterly report on Form 10-Q as of March 31, 2026, filed May 7, 2026
- Opendoor Technologies Inc. — quarterly report on Form 10-Q as of June 30, 2026, filed August 4, 2026
- Current report on Form 8-K of August 4, 2026, Items 2.02, 7.01 and 9.01, Exhibit 99.1 — second-quarter 2026 earnings press release with third-quarter outlook
- Current report on Form 8-K of August 13, 2026, Items 1.01, 3.02, 7.01 and 9.01 — subscription for the 2030 convertible notes, repurchase intent and capped call
- Current report on Form 8-K of August 19, 2026, Items 1.01, 2.03, 3.02, 8.01 and 9.01 — closing of the convertible notes and the share repurchase of August 17, 2026
- Current report on Form 8-K of May 7, 2026, Items 2.02, 7.01 and 9.01 — first-quarter results and supporting materials
- Additional proxy soliciting material (DEFA14A) of June 2, 2026 — the chief executive’s appeal to shareholders
- Current report on Form 8-K of June 12, 2026, Item 5.07 — results of the annual meeting held June 11, 2026
- Insider filings (Form 4) for Opendoor Technologies on SEC EDGAR, including the chief executive’s purchase of August 14, 2026
- All annual and quarterly reports of Opendoor Technologies on SEC EDGAR (CIK 0001801169)
- Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q); closing prices of July 24 and October 2, 2026, analyst coverage, short interest and the 52-week range as of October 3, 2026.
Disclosure: this article is journalistic analysis of publicly available documents. It is not investment advice, not a solicitation to buy or sell securities and not an individual recommendation. Shares of companies carrying large inventories and substantial debt are especially volatile; a total loss of invested capital is possible. All figures come from the SEC filings named above and carry their respective as-of dates. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this analysis.
Key figures at a glance
All monetary figures in millions of $; earnings per share as reported.
| Metric | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 8,021.0 | 15,567.0 | 6,946.0 | 5,153.0 | 4,371.0 |
| Operating Income (EBIT) | -568.0 | -931.0 | -386.0 | -320.0 | -287.0 |
| Net Income | -662.0 | -1,353.0 | -275.0 | -392.0 | -1,300.0 |
| Net Margin | -8.3% | -8.7% | -4.0% | -7.6% | -29.7% |
| Earnings Per Share | -1.12 $ | -2.16 $ | -0.42 $ | -0.56 $ | -1.70 $ |
Source: fundamental data & SEC filings (annual and quarterly reports, 10-K/10-Q)
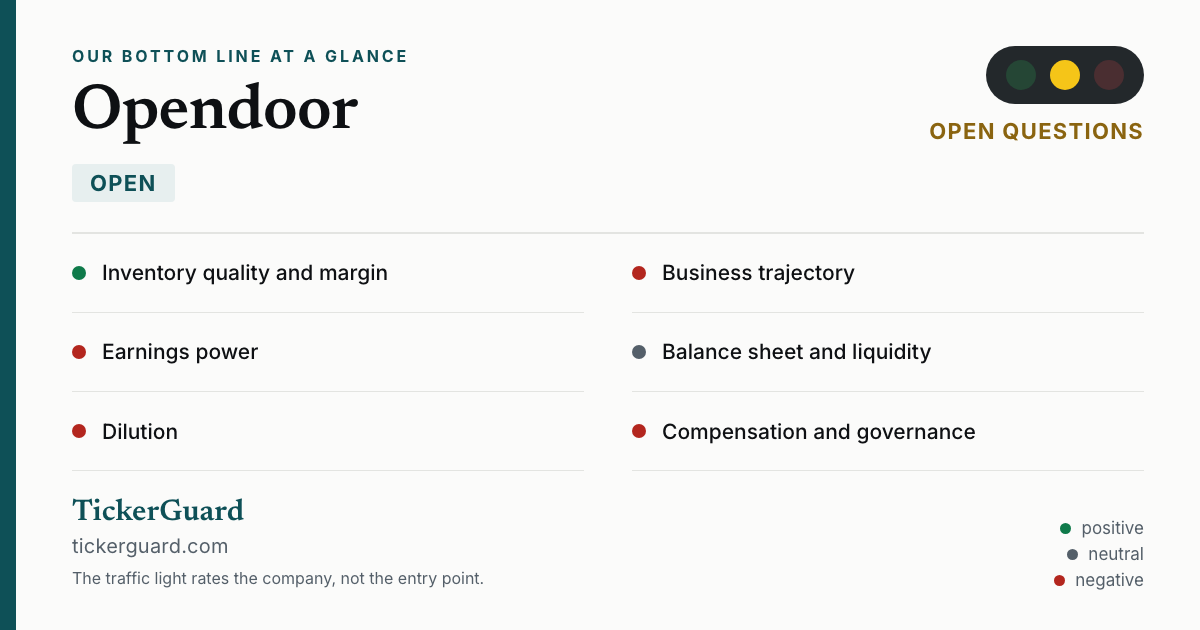
Our Bottom Line at a Glance
- Inventory quality and buying positive
- The share of homes listed for more than 120 days stood at 9 percent as of June 30, 2026, after 36 percent a year earlier; gross margin rose to 9.7 percent in the second quarter after 8.2 percent. At the same time Opendoor bought 4,378 homes after 1,757 in the prior-year quarter, and inventory grew to 5,459 homes.
- Business trajectory negative
- Revenue was $883 million in the second quarter of 2026, 44 percent below the prior-year quarter ($1,567 million), on 2,339 homes sold instead of 4,299. Across the years: $6,946 million (2023), $5,153 million (2024), $4,371 million (2025). For the third quarter the company guides to revenue growth of at least 20 percent on the prior-year quarter.
- Earnings power negative
- Loss from operations was negative in each of the three years: minus $386 million (2023), minus $320 million (2024), minus $287 million (2025), plus minus $303 million in the first half of 2026 after minus $69 million a year earlier. Management's target — break-even on adjusted net income by the end of 2026 — excludes stock-based compensation, which last ran at $119 million a quarter. The accumulated deficit stood at $5,368 million as of June 30, 2026.
- Balance sheet and liquidity neutral
- As of June 30, 2026 unrestricted cash stood at $896 million and equity at $914 million; in August roughly $440 million net came in from a zero-coupon convertible, per the company. The roughly $1.8 billion of inventory financing sits without recourse in special purpose entities, and all financial covenants were met. Against that stand $964 million of cash outflow in the first half, only $25 million of undrawn committed credit lines and a $650 million note due in 2030.
- Dilution negative
- Shares outstanding rose from 733,592,980 (June 30, 2025) to 968,626,958 (June 30, 2026), up 32 percent. The August 17, 2026 buyback cut that to about 926 million by arithmetic. The overhang of potential shares stood at 261.5 million as of June 30, plus up to 137.96 million from the new convertible note — although Opendoor intends to settle its principal in cash.
- Compensation and governance negative
- Stock-based compensation reached $239 million in the first half of 2026, including $205 million for price-linked awards whose market conditions were entirely unmet as of June 30, 2026; $551 million of expense is still to come. At the annual meeting on June 11, 2026 roughly 41 percent voted against executive compensation, after the chief executive publicly campaigned against the proxy advisers' recommendations.
Opendoor is buying again: 4,378 homes in the second quarter of 2026 after 1,757 a year earlier, with healthy inventory (9 percent listed longer than 120 days) and a 9.7 percent gross margin. Revenue, at $883 million, still lags the prior year by 44 percent, and the net loss was $162 million, $119 million of it stock-based compensation. In August the company used a zero-coupon $650 million convertible to fund its first share buyback (about 45.3 million shares) and further growth; the queue of potential shares remains long at 261.5 million plus up to 137.96 million from the note. Not investment advice.
What Our Rating Means
Open questions
The business works in principle, but one material question is open. As long as it stays open, our findings do not carry a quality verdict.
Re-examined against the quarterly report as of June 30, 2026: no solvency problem ($896 million of unrestricted cash, all financial covenants met), but no earnings turnaround either — buying has turned, earnings have not, hence still amber.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- Opendoor reached our research list through the Reddit mention screen of July 27, 2026 — an attention signal, not a quality verdict. The lists of our in-house stock scanner are recomputed nightly, so a snapshot would already be stale the following day.
- Recency status (update of October 3, 2026): the basis is the annual report (10-K) for 2025 filed February 19, 2026 and the quarterly report (10-Q) as of June 30, 2026 filed August 4, 2026. Every document filed from that day on was reviewed — the Form 8-K of August 4, 2026 with the earnings press release, the Forms 8-K of August 13 and 19, 2026 on the convertible note and the share repurchase, the Schedule 13G/A by Morgan Stanley of August 13, 2026 and the insider filings (Form 4) of August 14 and September 16, 2026; plus the Schedule 13G by BlackRock of July 29, 2026. A complete transcript of the August 4, 2026 earnings call was not available.
- On valuation: no filing states the share count after the buyback yet. The calculation uses 971,091,050 shares per the quarterly report cover page (as of July 28, 2026) less the roughly 45.3 million repurchased, about 926 million, times the $2.44 closing price of October 2, 2026 — roughly $2.26 billion. The figure from the fundamental data ($2.354 billion) still uses the older share count and sits about 4 percent higher.
Download the verdict card (traffic light and rating of this analysis as an image, PNG)
Stock Watch
This analysis is as of October 3, 2026. Stock Watch will tell you what's changed at OPEN since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Opendoor Technologies Inc (OPEN), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Opendoor buys residential homes in the United States on its own balance sheet, has them repaired and resells them. It earns a service fee, the spread between purchase and resale, and revenue from adjacent services such as title, escrow, brokerage and, since the first quarter of 2026, an in-house mortgage product. It employed 1,042 people as of December 31, 2025.
Opendoor bought 4,378 homes, 149 percent more than a year earlier, but sold only 2,339 after 4,299. Revenue was $883 million, 44 percent below the prior-year quarter and 23 percent above the first quarter. The net loss was $162 million after $29 million, and adjusted EBITDA was minus $4 million. The source is the quarterly report (10-Q) filed August 4, 2026.
They are share packages for employees that vest only once the stock price clears defined hurdles. Under U.S. accounting rules the grant-date value is spread as expense over the expected service period — even if the hurdle is never reached. In the first half of 2026 that came to $205 million; as of June 30, 2026 the filing states that no market condition was satisfied, with $551 million still to be recognized.
In August 2026 Opendoor issued a $650 million convertible note with no coupon, due August 15, 2030, at a conversion price of $4.71. Of the proceeds, roughly $158 million funded a share repurchase, per the company the first since going public (about 45.3 million shares at $3.49) and $52.5 million a capped call against dilution up to $6.98. Per the company, roughly $440 million remains net, before expenses.
Shares outstanding rose from 733,592,980 on June 30, 2025 to 968,626,958 on June 30, 2026, up 32 percent. On top of that sat 261.5 million potential shares from awards, warrants and convertible notes, plus, since August, up to 137.96 million from the new note. The August buyback cut the share count to about 926 million by arithmetic.
Loss from operations in 2025 was $287 million. The remainder came from a financing transaction in November 2025: Opendoor issued 180,580,200 shares at $6.56 and used the proceeds to repurchase $264 million principal amount of convertible notes for roughly $1.2 billion. That produced a book loss of $933 million.
On November 6, 2025 the board declared a special dividend in the form of warrants. Every holder of record on November 18, 2025 received three warrants per 30 shares, with exercise prices of $9, $13 and $17. A total of 99,295,146 were issued and 99,288,090 were outstanding on June 30, 2026; they expire at 5:00 p.m. New York City time on November 20, 2026 unless exercised earlier.
As of June 30, 2026 the company held $896 million of unrestricted cash, shareholders' equity of $914 million and total assets of $2,961 million. The roughly $1.8 billion of inventory financing sits in special purpose entities without recourse to the group; only $25 million of the committed lines remained undrawn. All covenants were met. In August roughly $440 million net came in from the new convertible note.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.