Ohmyhome Stock: The Core Business Sold for One Dollar — and Warrants That Count Nine Times
Singapore-based Ohmyhome gave away its property platform in May 2026 for $1, has been called Ohmyswift since November 3, 2026, and, according to its interim report, lives off two customers. The share count rose from 0.46 million at the end of 2025 to at least 5.13 million in mid-October 2026, and warrants issued in October can be swapped for nine times as many shares. Then the stock went up almost ninefold in four trading days. Not investment advice — just the question of whether anything other than new shares sits under the new name.
 Thomas Mücke
Founder & Publisher
As of Today
As of: November 11, 2026
- Closing price
- 25.84 $ +251.09%
- Market Capitalisation
- 55.0 $M
This analysis has a cut-off date. The Stock Guard tells you when something material changes in the numbers. Reserve your free spot
Chart
Interactive price chart (TradingView).
Last price: 25.84 $ (As of: November 11, 2026)
Note: pure fact-based analysis, not investment advice and not a solicitation to buy or sell. All figures without guarantee.
From November 3 to November 9, 2026, shares of Ohmyhome (Nasdaq: OMH) rose from $2.92 to $25.84 (closing prices per fundamental data), and on November 9 they even traded as high as $85.97. On November 4 alone, 93.4 million shares changed hands — eighteen times the most recently reported share count. On Reddit, the stock jumped from rank 613 to rank 43 on ApeWisdom within 24 hours, with 13 mentions (retrieved November 10, 2026). Behind this sits an investor trap as old as the market itself: the phoenix trap. A company has had hard years, gives itself a new name, a new business, a new domicile — and the rising price looks like proof that something new is rising from the ashes. That is exactly what happened at Ohmyhome: since November 3, 2026, the company has been called Ohmyswift Limited, it is legally no longer domiciled in the Cayman Islands but in the British Virgin Islands, and instead of real estate it now does online marketing. Let's make a deal: before you watch the phoenix fly, let's look through the ashes together — in the filings the company submitted to the U.S. securities regulator, the SEC: the annual report (20-F) for 2025, the interim financial statements as of June 30, 2026, and the current reports (6-K) and prospectus supplements (424B5) through November 9, 2026. Anyone who files false statements with the SEC risks penalties, which is why these reports are among the most reliable sources there are. In the end, you decide.
What Ohmyhome Is Today — From Property App to Marketing Agency
Ohmyhome traces back to 2015, when Rhonda Wong and Race Wong founded a property platform in Singapore: for buying, selling and renting homes, both government-built HDB flats and private property. Think of it as a real estate agent in your phone that also offered property management, renovation, moving and referrals for mortgages and insurance. The company listed on Nasdaq in March 2023. In fiscal 2025 — which matches the calendar year — it generated revenue of S$12.24 million, or about $9.5 million, according to its annual report (20-F), and employed 150 people. One Singapore dollar was worth about $0.77 as of June 30, 2026; the reports are presented in Singapore dollars.
That business no longer exists at Ohmyhome. Under an agreement dated June 17, 2026, the company sold its subsidiary Ohmyhome (BVI) Limited — and with it every property company in Singapore, Malaysia and the Philippines — to a company called Sterling Oat Ltd., closed as of May 31, 2026, according to the 6-K. What remains is a subsidiary founded in July 2025, Ohswiftwing Pte. Ltd., which runs online marketing for advertisers: strategy, content, campaigns and traffic bought from large online platforms. Since January 2026, the company has been led by Agus Prasetyo, who according to the filings has been regional general manager of the Indonesian digital firm PT Smartit Mantap Digital Indonesia since 2021. The founders are gone: Rhonda Wong resigned in October 2025, and Anthill, the company that the 2024 annual report says was owned half each by the two founders and that holds the shares with 100 votes each, is now wholly owned by a person named Lee Tsin Hau, according to the 2025 annual report. That defines the central tension of this analysis, and it runs through every chapter: the stock price is celebrating a fresh start — the filings describe a company that gave away its business for one dollar, lives off two customers and fills its cash box with ever more new shares.
Company history for investors
-
2023
IPO at $4.00
In March 2023, Ohmyhome sells 2.8 million shares at $4.00. After the 1-for-10 and 1-for-50 reverse splits, that equals $2,000 per share today.
-
2025
Reverse split, offerings, marketing subsidiary
A 1-for-10 reverse split in March, new shares at $0.45 and $0.18 in May and June, the Ohswiftwing subsidiary founded in July. For shareholders: the start of the dilution.
-
2026
Property platform sold for $1
First a S$19.0 million receivables waiver, then the sale to Sterling Oat Ltd. for $1 (agreement of June 17). For shareholders: only the two-customer marketing business remains.
-
2026
1-for-50 reverse split and new shares
Nasdaq notice in July, 1-for-50 reverse split in August, placements in July and October, an equity line of up to $40 million. For shareholders: at least 5.13 million shares instead of 0.46 million.
-
2026
Ohmyhome becomes Ohmyswift
Renamed and moved to the British Virgin Islands on November 3; the stock then rises almost ninefold in four trading days. For shareholders: a new name, the same numbers.
How the Stock Landed on Our Desk
Ohmyhome made our research list through our in-house Reddit hype scanner: according to ApeWisdom, the stock ranked 43rd among the most-discussed stocks on November 10, 2026, with 13 mentions in 24 hours — a day earlier it had been at rank 613. The price set it off. From November 3 to November 9, 2026, it rose almost ninefold, without any SEC filing in those days citing a business reason; the only filing of the week, dated November 9, concerns the new name and the new domicile. Classic metrics from our scanners help little with Ohmyhome: there is no price-to-earnings ratio because there are no earnings, and the annual figures through 2025 describe a business the company no longer owns. How often a new name covers an old story we have already seen at Chaince Digital, whose ticker CD is now on its fourth name. So keep this in mind from the start: with Ohmyhome, what counts is not what the stock price promises, but what is left after the sale — and how many shares split that remainder.
The Numbers Over the Years — An Honest Look
First, what deserves credit. The old property business grew: revenue rose from S$4.38 million in 2021 to S$5.00 million in 2023 and S$12.24 million in 2025, mainly through acquired property management firms. And the new marketing business generated revenue quickly: S$323,525 in its founding half-year of 2025, then S$2.48 million in the first half of 2026 ($1.92 million). In continuing operations, a little cash even came in from operating activities in the first half of 2026, S$96,064 — but mainly because unpaid supplier bills grew by S$491,516. The balance sheet as of June 30, 2026, is small but carries little debt: S$4.01 million of cash ($3.10 million), S$0.85 million of liabilities, S$3.28 million of shareholders' equity ($2.53 million).
Now the other side. Ohmyhome has never made money: it posted a loss in every year from 2021 through 2025, most recently S$4.34 million (2024) and S$9.20 million (2025), including a S$4.70 million goodwill impairment on acquired subsidiaries. By June 30, 2026, the accumulated deficit had reached S$33.9 million — almost as much as the additional paid-in capital from shareholder contributions on the balance sheet (S$36.3 million). And what was left of the new business in the first half of 2026 is shown in this chart:
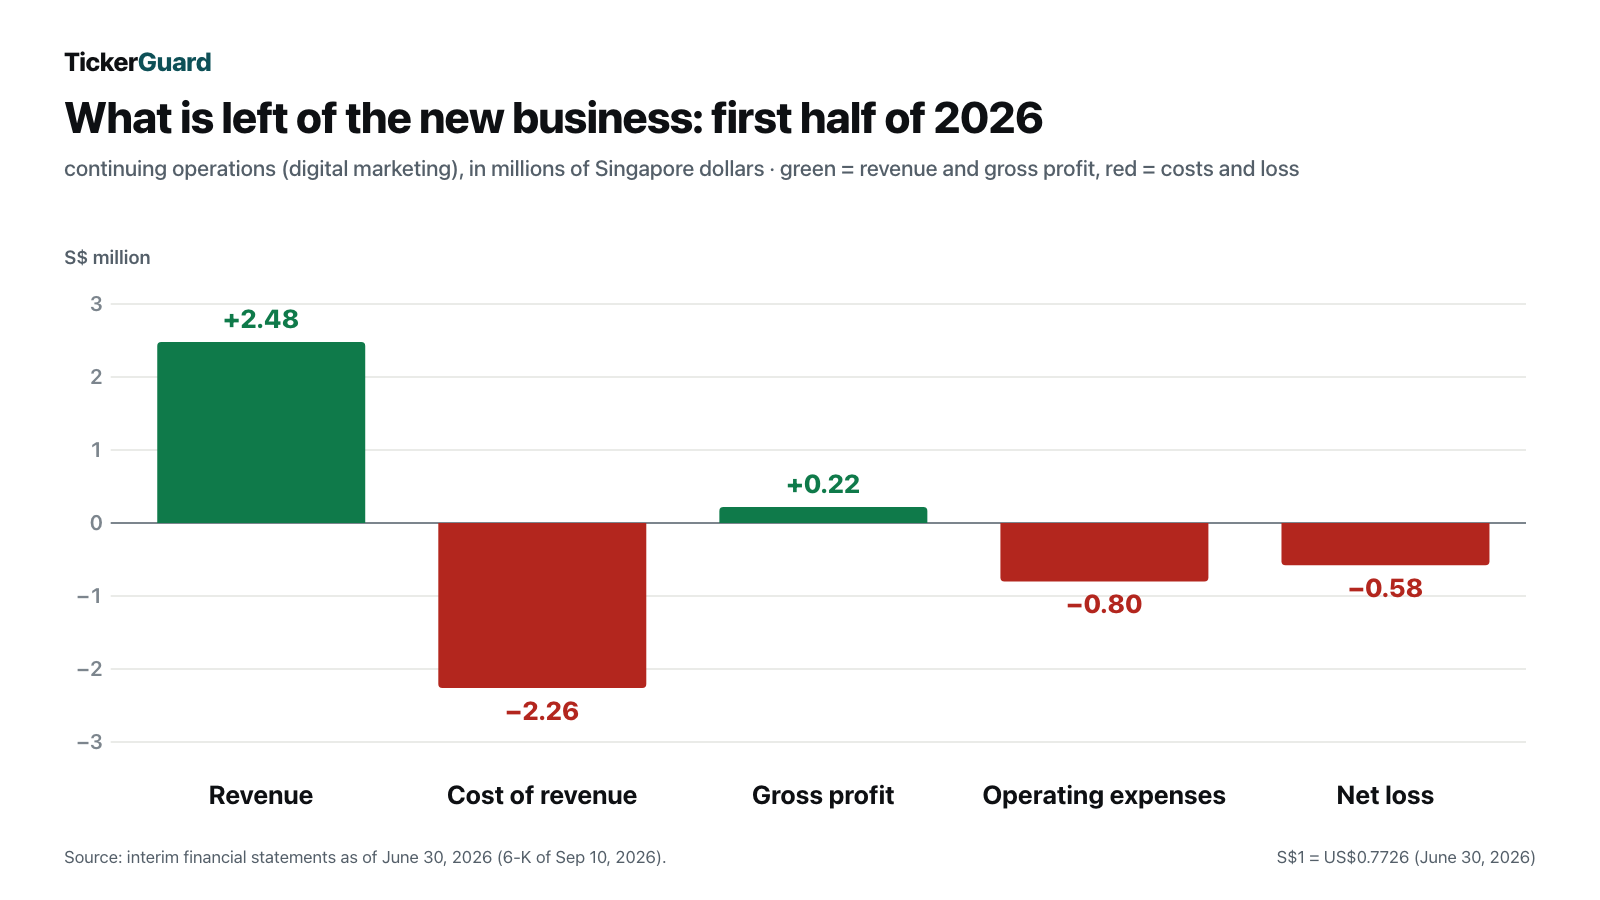
So of every revenue dollar, just under 9 cents remains as gross profit after personnel and subcontracted services (8.7 percent). For comparison: the group with its old property business kept about 32 percent in 2025. Remember the picture: the new business is a pass-through — most of what customers pay flows on to vendors. Which brings us to the uncomfortable truths.
What the Filings Say — The Uncomfortable Truths
Uncomfortable Truth No. 1: The Core Business Went for One Dollar
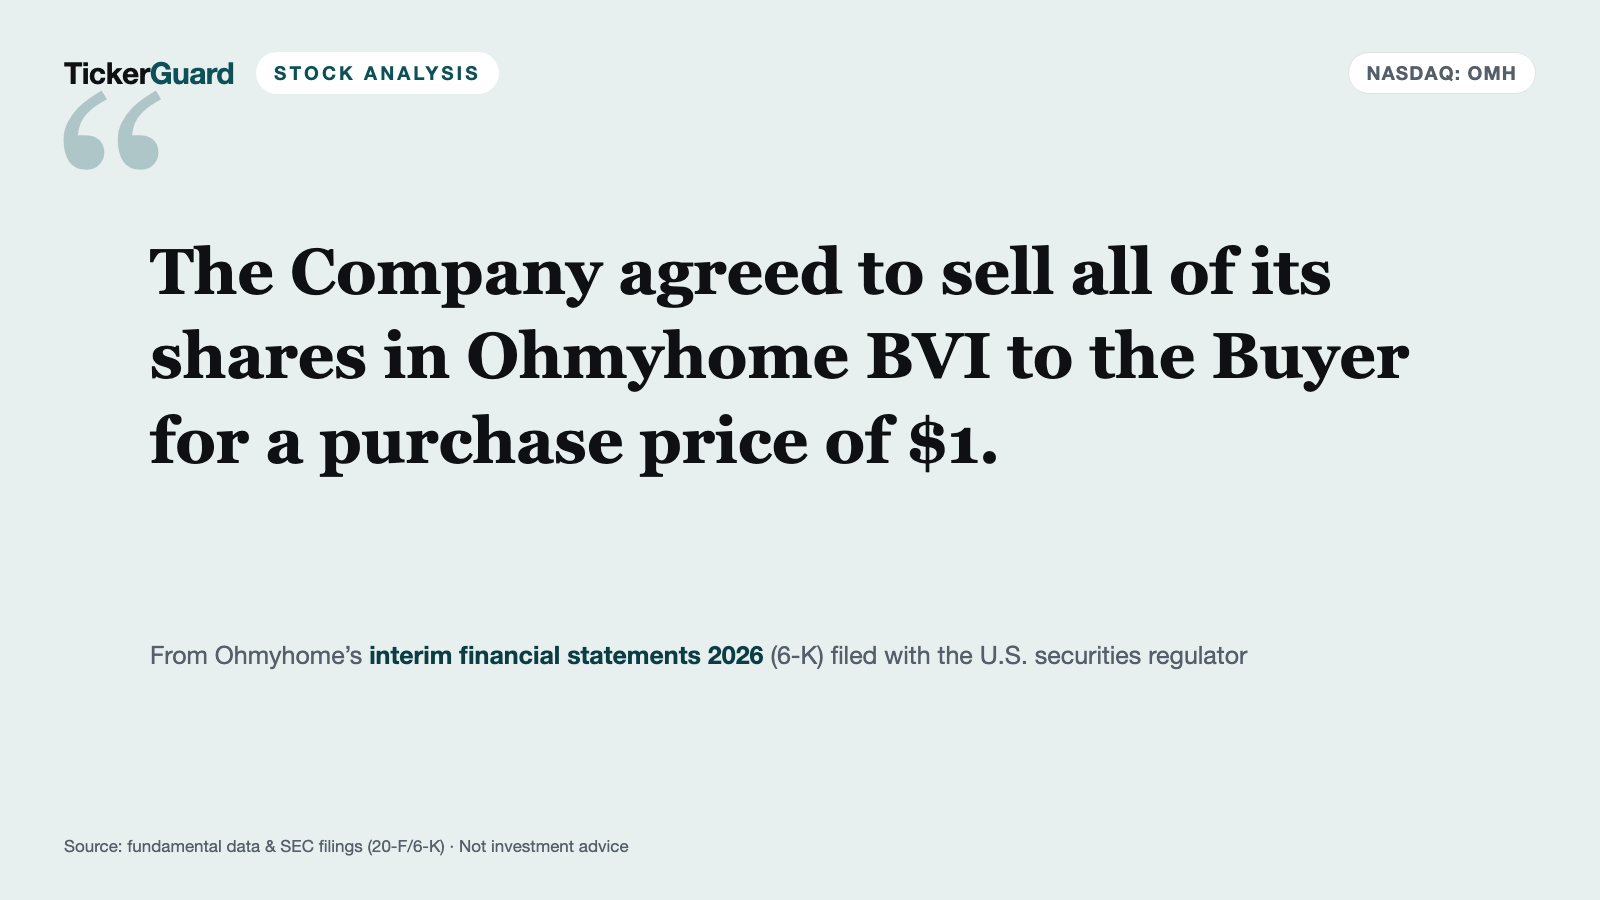
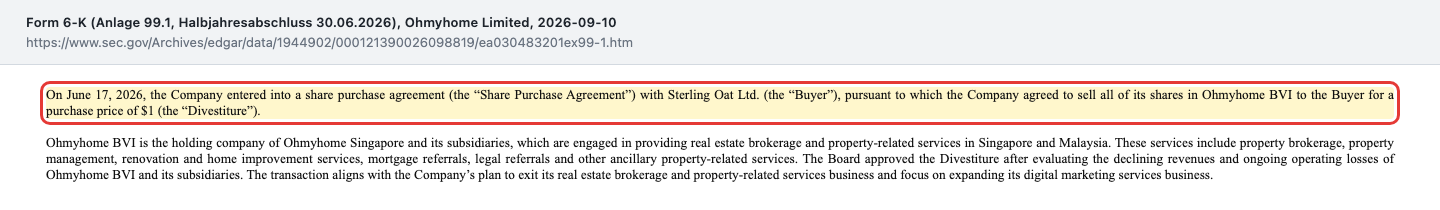
The sentence appears in the interim financial statements and in the 6-K of June 18, 2026, and it is so short you have to read it twice:
"On June 17, 2026, the Company entered into a share purchase agreement (the “Share Purchase Agreement”) with Sterling Oat Ltd. (the “Buyer”), pursuant to which the Company agreed to sell all of its shares in Ohmyhome BVI to the Buyer for a purchase price of $1 (the “Divestiture”)."
— Ohmyhome Limited, interim financial statements as of June 30, 2026 (6-K of September 10, 2026, Exhibit 99.1), Note 3
To be fair, here is the rationale: according to the 6-K, the unit had negative net assets of $14.77 million as of March 31, 2026, revenue was declining and losses continued. One dollar for a company with more liabilities than assets is not a scandal in itself. But most of those liabilities were owed to its own parent: on May 31, 2026, according to the same filing, Ohmyhome "irrevocably and unconditionally" waived S$19.0 million (about $14.7 million) of receivables from the unit — loans and assigned receivables with which the parent had financed its subsidiary over the years. Only then did the unit go for one dollar, and the accounts show a loss on disposal of S$517,968. Who stands behind Sterling Oat Ltd., a British Virgin Islands company with an office address in Singapore, none of the filings says. Think of it this way: you sell your house for one dollar after first forgiving the buyer the mortgage he owed you. Remember the picture: what shareholders put into the platform over the years no longer appears on any balance sheet.
Uncomfortable Truth No. 2: The New Business Hangs on Two Customers and One Vendor
Customer concentration is like a restaurant with only two regulars: as long as both come every day, it works — if one stays away, half the business is gone. At Ohmyhome it is even tighter:
"For the six months ended June 30, 2026, two customers each accounted for more than 10% of the Company’s total revenue, representing 67.08% and 32.92% of total revenue, respectively. For the six months ended June 30, 2025, no customer accounted for more than 10% of the Company’s total revenue."
— Ohmyhome Limited, interim financial statements as of June 30, 2026, Note 2 "Concentration of customers"
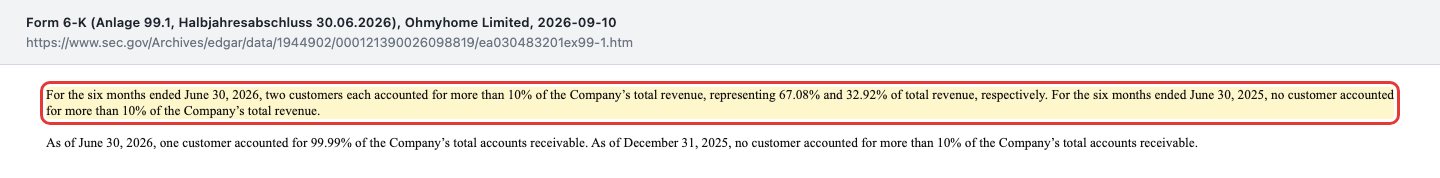
67.08 plus 32.92 makes exactly 100 percent: all revenue came from two customers. The other side is no broader. Two vendors accounted for 34.87 and 65.13 percent of costs, a single vendor for 100 percent of accounts payable, and a single customer for 99.99 percent of accounts receivable. The report names none of them. Together with a gross margin of 8.7 percent, that adds up to a business that essentially collects money from two clients and passes it on to two service providers. That can grow. But it has nothing a competitor could not copy, and the annual report itself says the services are provided "on a non-exclusive basis" and clients may engage other agencies.
Uncomfortable Truth No. 3: The Share Count Grows Faster Than Any Business
Dilution means your slice of the cake gets smaller when new slices keep being cut. At Ohmyhome the slices do not just get smaller — every so often they are glued back together so the stock trades above one dollar again. Nasdaq requires at least $1 per share; on July 13, 2026, it sent Ohmyhome a deficiency notice. The company has reverse-split its shares twice, 1-for-10 in March 2025 and — after the notice — 1-for-50 in August 2026; on September 15, 2026, Nasdaq confirmed that the minimum bid price requirement was met again. Restated to today's basis, the development looks like this:
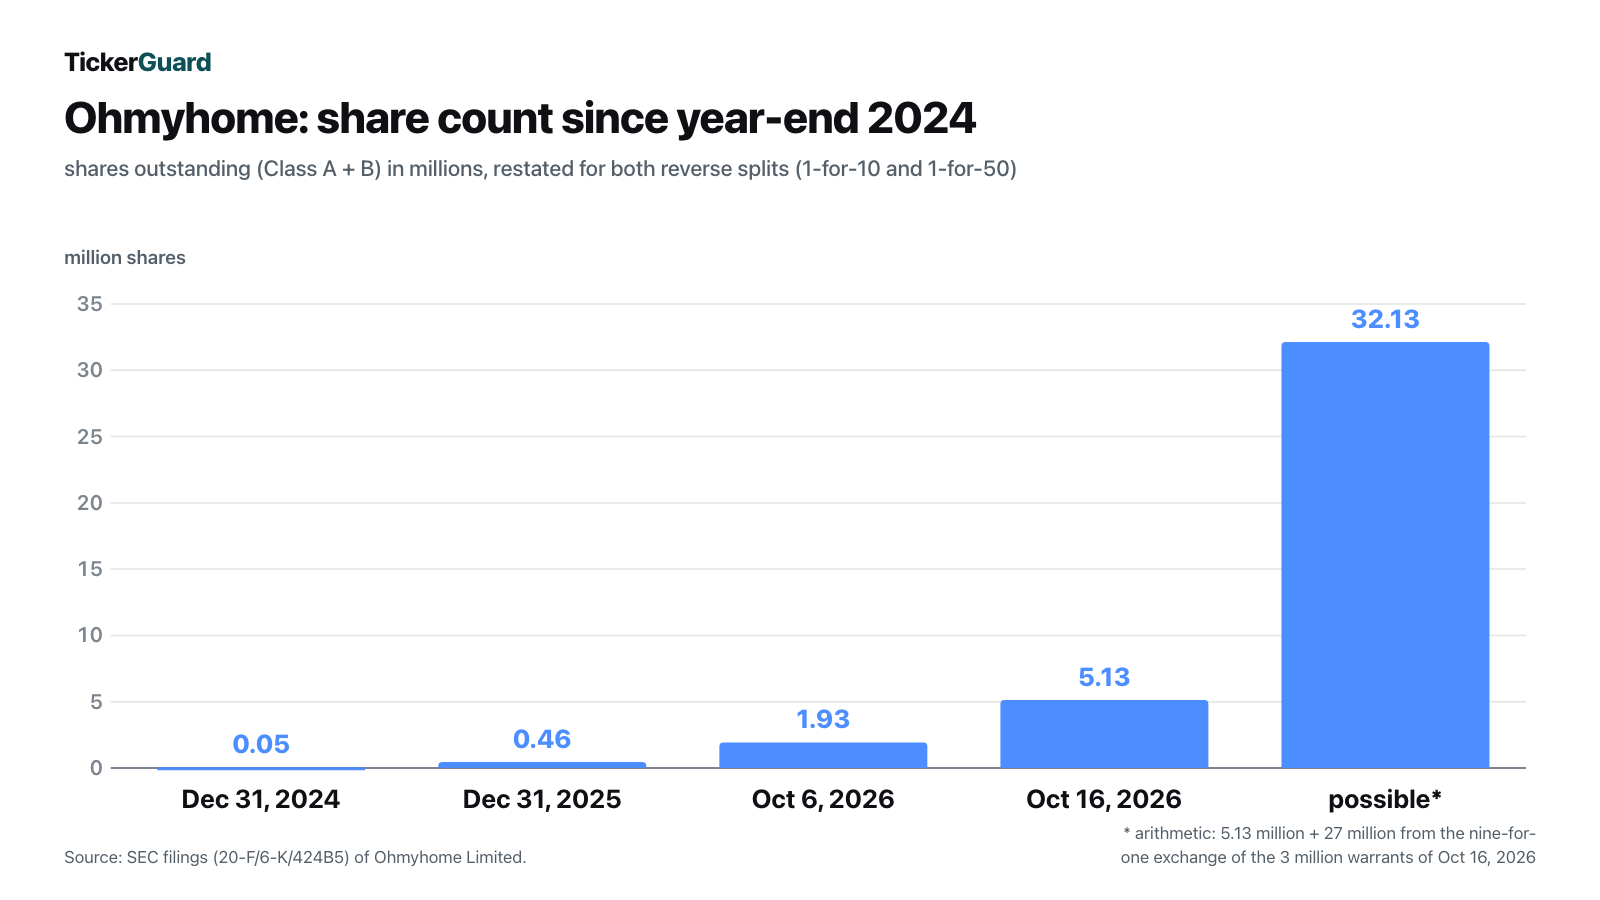
The individual steps are in the filings: 47,212 shares at the end of 2024, 462,054 at the end of 2025, and — after two placements in July 2026 and, by our arithmetic, the exchange of warrants — 1,928,724 on October 6 (1,911,893 Class A and 16,831 Class B, per the prospectus supplement), plus 200,000 commitment fee shares and 3,000,000 from the October 16 placement — at least 5,128,724 in total. The crux is a clause in the warrants that buyers in that placement received:
"Notwithstanding the foregoing, if at any time starting on the 7th calendar day (the “Alternate Cashless Exercise Date”) following the Initial Exercise Date, in lieu of the Class A Ordinary Shares to be issued in a cashless exercise pursuant to the formula set forth in the Warrants, the holder may, by delivery of a notice of exercise to the Company, alternatively exchange all, or any part, of the Warrants into such aggregate number of Class A Ordinary Shares equal to the product of (x) nine (9), multiplied by (y) such aggregate number of Class A Ordinary Shares underlying such portion of the Warrants to be exercised as specified in such applicable notice of exercise (each, an “Alternate Cashless Exercise”, and such aggregate number of Class A Ordinary Shares to be issued in such applicable Alternate Cashless Exercise, the “Alternate Cashless Exercise Amount”)."
— Ohmyhome Limited, current report 6-K of October 16, 2026
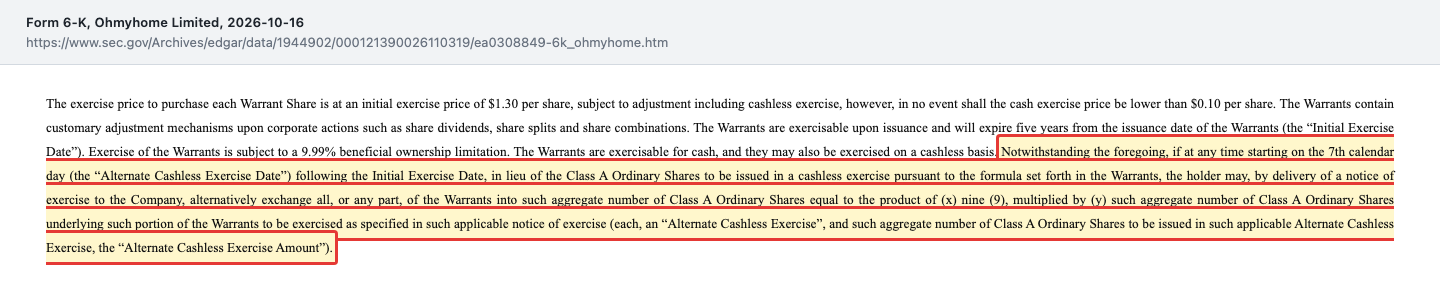
Three million warrants times nine are 27 million shares — more than five times the shares outstanding after the placement. The summer shows the clause gets used: the warrants of July 17, 2026, had the same nine-for-one rule, and by our arithmetic the October 6 share count adds up exactly if all 106,667 July warrants were exchanged for 960,003 shares. The October buyers are subject to a twelve-month lock-up under the 6-K, which also covers shares acquired later. But the exchange shrinks your slice of the cake immediately. And there is a second tap: since October 7, 2026, Ohmyhome may sell an investor shares worth up to $40 million over 24 months, at the lower of $1.26 and half of the lowest closing price of the preceding 180 trading days, with a floor of $0.10. Measured against the market value before the agreement, about $4.9 million on October 6, that is a facility eight times the size of the company. The annual meeting of July 21, 2026, had prepared for this and raised the authorized capital to 90 trillion Class A shares — a 90 followed by twelve zeros. Remember the line: growth paid for with fresh shares is never free — and here the shares grow faster than the business.
Uncomfortable Truth No. 4: The Company Doubts Its Own Survival — and the Board May Now Reverse-Split on Its Own
A going-concern warning is the admission that the cash will not last without fresh money. Ohmyhome wrote it down itself in the prospectus supplement of October 7, 2026, in a section headed by a bold sentence stating that its losses, negative operating cash flows and accumulated deficit raise substantial doubt about its ability to continue as a going concern:
"These factors, individually and collectively, raise substantial doubt about our ability to continue as a going concern, and therefore, could materially limit our ability to raise additional funds through an issuance of debt or equity securities or otherwise."
— Ohmyhome Limited, prospectus supplement 424B5 of October 7, 2026, "Risk Factors"
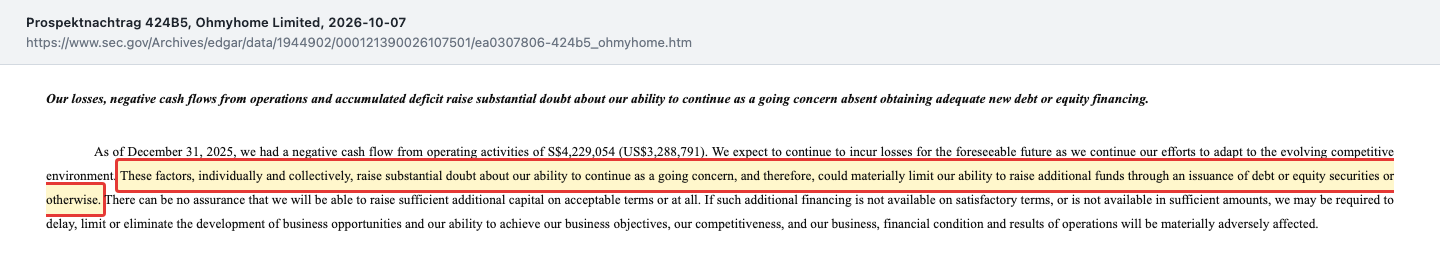
The reference point is the operating cash outflow for 2025: S$4.23 million ($3.29 million). Since then the picture has been mixed: the new business burns less cash than the old one, and the placements in July ($1.6 million gross and $3.63 million net) and October ($3.9 million gross) brought in fresh money; the agreed $5 million pre-paid advance under the equity line was to come on top. That does not cure the doubt — it is merely paid for with new shares.
Then there is a detail from the move to the British Virgin Islands that shareholders approved on October 26, 2026. The meeting notice explains the difference itself: in the Cayman Islands, a share consolidation requires shareholder approval; under British Virgin Islands law it is "a board-level decision by default". The new memorandum, Exhibit 3.1 to the November 9, 2026, filing, makes use of that:
"14.1. The Company may by a Resolution of Shareholders or by a Resolution of Directors amend the Memorandum to increase or reduce the number of Shares the Company is authorised to issue."
— Ohmyswift Limited, Memorandum and Articles of Association, Exhibit 3.1 to the 6-K of November 9, 2026
Clause 14.2 also allows the board to combine issued shares. For you, that means the next reverse split, should the price fall below one dollar again, no longer needs a shareholder meeting. And the people on the board changed often in 2026 — from January through August 2026, Ohmyhome reported five resignations from management and the board.
Valuation: What the November 9, 2026, Price Demands
We deliberately do not use the market value from the fundamental data here: it is based on 2.11 million shares, the count as of October 8, 2026, before the October 16 placement. Our own calculation is a floor: at least 5.13 million shares times $25.84 (close on November 9, 2026) gives at least about $132 million. Against that stood shareholders' equity of $2.53 million and first-half revenue of $1.92 million as of June 30, 2026. Even if you simply double the first-half revenue, the market is paying about 35 times the annual revenue of a business with an 8.7 percent gross margin and two customers — and that is before the up to 27 million shares from the nine-for-one exchange. A second yardstick is more sobering: at the IPO in March 2023, a share cost $4.00. After the 1-for-10 and 1-for-50 reverse splits, that equals $2,000 per share on today's basis. Anyone who bought then and held is down about 99 percent even after the November jump.
Upside and Risks at a Glance
What speaks for Ohmyhome:
- The loss-making property business is gone: the unit had negative net assets of $14.77 million as of March 31, 2026, and kept losing money in the first half of 2026 until the sale.
- The new marketing business generated revenue quickly: S$2.48 million in the first half of 2026 after S$323,525 in its founding half-year of 2025.
- Hardly any debt: S$0.85 million of liabilities against S$4.01 million of cash as of June 30, 2026, plus fresh money from the July and October 2026 placements.
- The Nasdaq minimum bid price requirement has been met again since September 15, 2026.
What speaks against it:
- The core business went for $1 after the parent waived S$19.0 million of receivables; the filings do not say who stands behind the buyer.
- Two customers delivered all revenue in the first half of 2026, one vendor accounted for all accounts payable; gross margin was 8.7 percent.
- On today's basis, the share count rose from 0.05 million at the end of 2024 to at least 5.13 million; warrants with a nine-for-one exchange (up to 27 million shares) and an equity line of up to $40 million at half the lowest price come on top.
- The company itself cites substantial doubt about its ability to continue as a going concern in the prospectus supplement of October 7, 2026; it lost money in every year from 2021 through 2025.
- The founders and control of the high-vote shares have changed hands, since the move to the British Virgin Islands the board may reverse-split on its own, and on November 9, 2026, alone the stock swung between $19.91 and $85.97.
A Human Conclusion
Back to the phoenix trap from the beginning. Its core is not that a fresh start is impossible — companies reinvent themselves, and sometimes it works. Its core is that the rising price makes you forget what lies in the ashes: a property platform that changed hands for one dollar after its parent forgave it S$19 million; a new business that lives off two customers and keeps just under nine cents of every revenue dollar; a share count that has grown a hundredfold in less than two years and could grow sixfold again through an exchange mechanism; and a prospectus in which the company itself doubts its survival. The phoenix of legend rises from its own ashes. At Ohmyhome, the first thing to rise is the share count. So the honest question for you is not "How much further can the stock run?" but: Would you buy this company if it were still called Ohmyhome and the stock stood at $2.92? If yes, you have a thesis. If not, you have bought a new name. What you make of it is your decision. And that is exactly as it should be.
Sources
All original documents used in this analysis — so you can check them yourself:
- Ohmyhome Limited — interim financial statements as of June 30, 2026 (6-K of September 10, 2026, Exhibit 99.1)
- Ohmyhome Limited — SEC annual report 20-F for 2025 (filed April 28, 2026)
- Ohmyhome Limited — SEC annual report 20-F for 2024 (filed April 29, 2025)
- Ohmyhome Limited — 6-K of June 18, 2026 (debt waiver and sale of Ohmyhome BVI)
- Ohmyhome Limited — 6-K of July 16, 2026 (Nasdaq minimum bid price) and of September 17, 2026 (compliance regained)
- Ohmyhome Limited — 6-K of July 17, 2026 (private placement with warrants), of July 21, 2026 (annual meeting, authorized capital) and of July 28, 2026 (registered direct offering)
- Ohmyhome Limited — 6-K of August 20, 2026 (1-for-50 share consolidation)
- Ohmyhome Limited — 6-K of October 7, 2026 (equity line of up to $40 million) and prospectus supplement 424B5 of the same day
- Ohmyhome Limited — notice of the extraordinary general meeting of October 26, 2026 (6-K of October 13, 2026, Exhibit 99.1)
- Ohmyhome Limited — 6-K of October 16, 2026 (private placement, warrants with nine-for-one exchange)
- Ohmyswift Limited (formerly Ohmyhome) — 6-K of November 9, 2026 (name change, continuation to the British Virgin Islands) with memorandum and articles, Exhibit 3.1
- Ohmyhome Limited — 6-K reports on management changes of October 27, 2025, January 9, 2026, February 13, 2026, April 24, 2026, June 15, 2026 and August 25, 2026
- Complete SEC filing history: EDGAR overview Ohmyhome (sec.gov)
- Fundamental data (prices, trading volume, revenue and results for 2021 and 2022; data as of November 10, 2026), cross-checked against the SEC filings.
- Reddit mentions: ApeWisdom (retrieved November 10, 2026); accessed via our in-house Reddit hype scanner.
Transparency & disclaimer: this analysis is journalistic commentary on publicly available information. It is not investment advice, not a regulated investment research product and not a solicitation to buy or sell securities. Equity investments carry substantial risk up to and including total loss. All information is provided without warranty; the as-of date for each figure is stated in the text. Positions held by the operator are disclosed daily; where one exists, it appears as a notice at the top of this analysis.
Our Bottom Line at a Glance
- Business model negative
- After selling the property platform for $1 (closed as of May 31, 2026, per 6-K), a digital marketing business with an 8.7% gross margin in the first half of 2026 remains; per the 20-F, clients buy the services on a non-exclusive basis.
- Customer concentration negative
- Two customers accounted for 67.08% and 32.92% of revenue in the first half of 2026, one customer for 99.99% of receivables and one vendor for 100% of accounts payable.
- Balance sheet & liquidity negative
- Hardly any debt (S$0.85 million as of June 30, 2026), but only $3.10 million of cash; the prospectus supplement of October 7, 2026, cites substantial doubt about the ability to continue as a going concern. Fresh money in 2026 came only from new shares.
- Dilution negative
- Share count on today's basis from 47,212 (end of 2024) to at least 5.13 million (October 16, 2026); warrants with a nine-for-one exchange (up to 27 million shares) and an equity line of up to $40 million at half the 180-day low.
- Governance negative
- Waiver of S$19.0 million of receivables before the $1 sale to an unnamed buyer, change of control over the Class B shares, five resignations from management and the board from January through August 2026, reverse splits possible by board resolution since the move to the BVI.
Ohmyhome is the phoenix trap in its purest form: a new name, a new domicile, a new business and a stock that went up almost ninefold in four trading days in November 2026. The filings show a core business that changed hands for one dollar, a marketing business with two customers and an 8.7 percent gross margin, a share count that has grown a hundredfold in less than two years, and a prospectus that doubts the company's survival. Whoever buys is betting on a fresh start that so far has been financed mainly by new shares. Not investment advice.
What Our Rating Means
Substance risk
We found at least one documented issue that threatens the company itself — regardless of how the stock is currently valued.
Red, because several documented substance risks come together: in its prospectus supplement of October 7, 2026, the company itself cites substantial doubt about its ability to continue as a going concern, all revenue of the remaining business came from two customers in the first half of 2026, and financing runs through shares on terms that can multiply the share count. Add the $1 sale after a S$19.0 million receivables waiver and a Nasdaq deficiency notice in July 2026. The decision is yours.
A journalistic assessment by our editorial team at the time of the deep dive, based on public sources — not investment advice and not a solicitation to buy or sell. Your personal circumstances (investment goals, risk capacity, taxes) cannot be taken into account. What our levels mean, how verdicts are formed, and what conflicts of interest exist →
Worth Noting
- The analysis was triggered by our in-house Reddit hype scanner; per ApeWisdom (retrieved 11/10/2026) 13 mentions in 24 hours, rank 43 after rank 613 a day earlier. Price references: $2.53 (10/06/2026, per 424B5), $2.92 (close 11/03/2026), $15.55 (close 11/04/2026), $25.84 (close 11/09/2026, intraday range $19.91 to $85.97).
- Data as of: the latest periodic report is the interim financial statements as of 06/30/2026 (6-K of 09/10/2026); all filings through the 6-K of 11/09/2026 were reviewed. Annual figures through 2025 cover the whole group including the property business; the first-half 2026 figures in the "Numbers" chapter cover only the continuing marketing business. Revenue and results for 2021 and 2022 come from fundamental data, from 2023 onward from the 20-F annual reports.
- Share count as a floor: whether warrants were exchanged or shares issued under the equity line after 10/16/2026 is not reported in any filing through 11/09/2026. The market value in the fundamental data (about $55 million) is based on 2.11 million shares and is therefore not used.
- Not to be confused with: Ohmyhome (OMH) has nothing to do with OneMain Holdings (ticker OMF). The new name Ohmyswift Limited does not yet appear in EDGAR as of 11/10/2026; the company is still listed there as "Ohmyhome Ltd".
Stock Watch
This analysis is as of November 11, 2026. Stock Watch will tell you what's changed at OMH since then.
Later $1 a month per stock — signing up is free, and you'll be the first to know when it launches.
The full analysis as a PDF for later
We will send you this analysis as a PDF — to print, file away, and read at your own pace. And we will add you to the free Stock Watch list for Ohmyhome Limited (OMH), so you hear about it when something material in this analysis changes.
Frequently Asked Questions
Ohmyhome Limited (Nasdaq: OMH) of Singapore, called Ohmyswift Limited since November 3, 2026, runs online marketing for advertisers through its subsidiary Ohswiftwing Pte. Ltd.: strategy, content, campaigns and purchased traffic. Its former property platform with brokerage, property management and renovation in Singapore and Malaysia was sold to Sterling Oat Ltd. for $1 in 2026.
According to the 6-K of June 18, 2026, the unit Ohmyhome (BVI) had negative net assets of $14.77 million as of March 31, 2026, declining revenue and continuing losses. Before the sale, the parent waived S$19.0 million of receivables from the unit on May 31, 2026. The purchase price was $1; the filings do not say who stands behind the buyer.
On October 26, 2026, shareholders approved renaming the company Ohmyswift Limited and moving its domicile from the Cayman Islands to the British Virgin Islands. Both took effect on November 3, 2026 (6-K of November 9, 2026). The stock continues to trade on Nasdaq under the symbol OMH; a new CUSIP number has been applied for.
Restated for the 1-for-10 (March 2025) and 1-for-50 (August 2026) reverse splits, the share count rose from 47,212 at the end of 2024 to 462,054 at the end of 2025 and to at least 5.13 million after October 16, 2026. The 3 million warrants of October 16 can be exchanged for nine shares each, or 27 million shares. On top of that comes an equity line of up to $40 million.
No. It posted a loss in every year from 2021 through 2025, S$9.20 million in 2025. In the first half of 2026, the continuing marketing business lost S$0.58 million on S$2.48 million of revenue; including the unit it sold, the loss was S$1.84 million. The new business had a gross margin of 8.7 percent.
Nasdaq sent Ohmyhome a deficiency notice on July 13, 2026, because the stock had closed below $1 for 30 business days. After the 1-for-50 reverse split in August, it closed above $1 for ten business days from August 31 to September 14, 2026; on September 15, Nasdaq confirmed compliance. In its prospectus supplement of October 7, 2026, the company also cites substantial doubt about its ability to continue as a going concern.
Found an error?
Did you spot a factual error, an outdated number, or a typo in this deep dive? Let us know briefly — your report goes straight to the editorial team.